The Philippines Builds Hospitals. The Money Sits at the Pharmacy Counter.

AC Health targets 10 hospitals, 300 clinics and 1,150 pharmacies by 2027. Its own funding round shows where the margin really lives. Philippines - November 07, 2026 - (SeaPRwire) - On September 1, 2025, Ayala Corporation filed a short disclosure with the Philippine Stock Exchange. It recorded a share subscription, not a ribbon-cutting: ABC Impact Fund II LP, a Singapore investor backed by Temasek Trust, subscribed to 121,089,059 common shares at P4.3013 each and 208,275,585 redeemable preferred shares at P4.1972 each, a first tranche of roughly P1.4 billion for an economic stake of about 16 percent in Ayala Healthcare Holdings, the listed conglomerate's hospital-and-drugstore unit (Ayala Corporation, 2025). The filing carried a promise attached: by 2027, the company called AC Health would run at least 10 hospitals, 300 clinics and 1,150 pharmacies. The company's own materials repeat those three numbers like a drumbeat. What they never say out loud is that the third number is the business, and the first two are the front door. What the network actually looks like AC Health turned ten in 2025. Its 2025 anniversary materials list the footprint precisely: 236 corporate and multispecialty clinics and 6 hospitals under the Healthway Medical Network, 880 pharmacies across the Generika Drugstore and St. Joseph Drug chains, and 1,178 certificates of product registration under its drug importers, IE Medica and MedEthix (Philippine Daily Inquirer, 2025). Revenue in 2024 was P9.4 billion, up 10 percent from the year before. The provider side grew 22 percent in revenue in 2024, well above the hospital industry's 8 percent. The pharma side, the company says, outperformed an industry that shrank 5 percent that year. Table 1: AC Health's stated 2027 network targets against the mid-2025 footprint. Network pillar Mid-2025 actual count 2027 target Growth still needed Hospitals (Healthway Medical Network) 6 10 +4, or 67 percent Clinics (corporate and multispecialty) 236 300 +64, or 27 percent Pharmacies (Generika plus St. Joseph Drug) 880 1,150 +270, or 31 percent Product registrations (IE Medica, MedEthix) 1,178 not stated no public target Source: Philippine Daily Inquirer 🔗, tenth-anniversary reporting, 2025. Six hospitals. Eight hundred eighty drugstores. Hold that ratio in your head, because the 2027 target preserves it almost exactly. Ten hospitals, three hundred clinics, one thousand one hundred fifty pharmacies. Between mid-2025 and the 2027 deadline, the hospital count must grow by about 67 percent, the clinic count by 27 percent, and the pharmacy count by 31 percent. None of those three growth rates is exotic on its own. The odd thing is the shape, and the company's own filing discipline shows it knows the shape matters. The 115-to-1 question Divide the 2027 pharmacy target by the hospital target and you get 115. Do the same to the current footprint and you get about 147. A network that describes itself as an "integrated healthcare ecosystem" carries more than a hundred retail drugstores for every hospital it runs. If the pharmacies existed to feed the hospitals, one or two dozen would do. At this density, the arrow points the other way: the hospitals are the brand that makes the drugstore chain credible. The company's stated expansion method confirms the reading. ABC Impact's capital is earmarked for growth "through a combination of organic initiatives and targeted acquisitions" across all three pillars (Ayala Corporation, 2025). Hospitals are the slowest, most capital-hungry item on that list. A 200-bed acute care hospital like Cebu Velez General Hospital, the 1947-era institution AC Health agreed to acquire a majority stake in through Healthway Medical Network in 2025, takes years of construction or a delicate negotiation with a founding family. A pharmacy is a lease and a license. When a 2027 deadline looms, you know which of the two can be added in bulk. Who pays at the counter The structural reason a Philippine healthcare group looks like this lives in the payer mix, not in management preference. Out-of-pocket spending accounted for 41.2 percent of total health expenditures in 2025, according to Philippine Statistics Authority data cited during congressional budget debates (Philippine Daily Inquirer, 2026). The state insurer, PhilHealth, covers 10.6 percent of total health expenditure, and its own leadership told a Senate hearing in February 2025 that it wants that share at 18.5 percent within a few years (GMA News, 2025). Everything else flows through household wallets, and household wallets buy medicine first. A hospital admission is a catastrophe you finance or defer. A box of generic antihypertensives is twelve pesos you pay today. Two things changed in the payer system in 2025, and both matter to AC Health's plan. First, PhilHealth raised case rates by 50 percent across around 9,000 benefit packages effective January 1, 2025, funded from a P284 billion corporate operating budget of which P271 billion goes to benefit payments (PhilHealth, 2024 annual report). The same budget funds priority packages that read like a list of the most expensive things a Filipino household can face: capitation of P1,700 to P2,100 per person under the KonSulTa primary care program, coverage of 156 hemodialysis sessions at P6,350 per session, and new outpatient coverage for emergency care and mental health. Second, the same budget year carried zero government premium subsidy for indirect contributors, meaning the expansion had to be self-funded. Benefit payouts have surged accordingly: P83 billion in 2023, P330 billion in 2025, and a stated target of P420 billion in 2026 (Situation Report, 2026). If that trajectory holds, the pressure on household wallets eases at the margin, and formal care gets a little less deferrable. The gaps the state leaves open are easiest to see at the counter. PhilHealth's dental benefit shoulders P1,000 per year for assessment and cleaning across two visits at accredited government clinics, while private dental providers typically charge P1,500 to P1,600 per visit (Daily Tribune, 2025). A benefit that covers less than one private appointment per year is not coverage in any meaningful sense; it is a voucher. Multiply that arithmetic across dermatology, consultations and maintenance medicine, and you have the customer base Generika was built for: people who are insured on paper and self-pay in practice. The pharmacy chain does not compete with PhilHealth. It harvests what PhilHealth does not reach. Now run the arithmetic yourself. If PhilHealth succeeds in cutting out-of-pocket spending to its stated 25 to 30 percent goal, more drug purchases shift to prescriptions attached to formal care, and pharmacy footfall follows prescriptions rather than impulse. That helps a chain with an integrated distributor. If PhilHealth stalls, the current model works exactly as built, because patients keep paying cash at the counter. The pharmacy-heavy shape wins in both branches. That is not a criticism of the strategy; it is the reason the strategy is what it is. A network built for the world's most common Philippine patient, the one paying out of pocket, is a drugstore network with hospitals attached. A demand shock the plan does not advertise There is a third variable in the structure, and it is not friendly. In 2025 the Department of Health declared a national public health emergency over HIV, with infections among people aged 15 to 25 reported up 500 percent, rising from about six recorded cases per day in 2010 to between 40 and 57 new cases each day in 2025 (Philippine Daily Inquirer, 2025). AC Health has responded by pushing proactive HIV screening through workplaces, schools and communities, with its Healthway Cancer Care Hospital handling vaccination, early diagnosis and treatment. Ho, the public health expert quoted in the company's anniversary materials, put the division of labor plainly: "The government and civil society organizations have made significant progress in addressing the HIV epidemic. But with this looming public health emergency, the private sector must step up to complement existing efforts and help scale proven interventions." Set the epidemiology next to the expansion arithmetic and a tension appears. An integrated network profits from volume through its clinics and counters, and an infectious-disease surge among working-age Filipinos generates exactly that volume, in screening visits, lab work and chronic care. Nobody at the company said the quiet part, and none of the funding documents mention it. But a healthcare group scaling drugstores at 31 percent while its home market handles an outbreak among 15-to-25-year-olds is a company whose growth model and whose social problem have started to move in the same direction. That is either a tragedy of alignment or a business model working as designed, depending on how much cynicism you brought with you. If that were true The pitch around the funding round used the word "impact" repeatedly. David Heng, chief executive of ABC Impact, said the firm believes AC Health is "well positioned to deliver meaningful social outcomes alongside sustainable growth" (BusinessWorld, 2025). Fair enough. The firm manages more than $900 million in assets and its portfolio carries recognizable names: Kim Dental, the largest private dental network in Vietnam; DCDC Kidney Care, an Indian dialysis provider running more than 200 centers across underserved regions; and HiRo, a clinical research organization serving mid-sized pharmaceutical and biotech companies across Asia Pacific and the United States. First direct entry into Philippine healthcare, a market of 116 million insured-on-paper residents, from a fund with that playbook is not a lottery ticket. It is a pattern trade. But look at the instruments in the same disclosure. Of the 329 million shares subscribed on September 1, 2025, 208.3 million were redeemable preferred shares, a class that typically carries priority on payouts and a redemption path, paired with a warrant instrument and a shareholders' agreement signed the same day. The "16 percent stake" is an economic interest with real structure around it. If the social mission were the whole story, the money could have bought plain common shares. It did not, and the instrument choice says the investor priced downside protection into a deal marketed as conviction. The company retained Bank of America Securities as exclusive financial advisor, which is what you do when the negotiation is hard, not when it is ceremonial. The company's counterargument would be that first institutional money into a young market buys protection, and that Temasek-linked capital taking any Philippine healthcare exposure is itself the signal. Both things can be true. What the structure does tell you is the order of operations: build the pharma and distribution base that produces cash, use the impact capital to underwrite the expensive hospital bets, and let the 2027 headline numbers bundle the two into one story. In July 2026, the story got a presidential assist. During Ferdinand Marcos Jr.'s working visit to Singapore, the Department of Trade and Industry announced the expansion is expected to support around 10,000 direct healthcare and retail jobs by 2027 (DTI, 2026). Note the word "retail" sitting quietly next to "healthcare" in that sentence. The department counted honestly. The headlines did not. What this buys the patient To be fair to management, the integrated model has real content. Generika Drugstore is the country's pioneer in generic retail. IE Medica and MedEthix import and distribute pharmaceuticals at scale. St. Joseph Drug anchors North and Central Luzon. Owning the importer, the distributor and the counter means a generic drug moves through one margin stack instead of three, which is how a chain can sell generics cheaply and still clear the 31 percent store-count expansion it has scheduled. Management's long-range goal, stated at the anniversary, is a $2 billion healthcare enterprise serving one in five Filipinos by 2035 (Philippine Daily Inquirer, 2025). One in five is a reachable fraction for a pharmacy chain and an unreachable one for a hospital group at current build rates. The stated dream and the feasible plan quietly agree with that reading. The Cebu Velez deal shows what the hospital leg of the plan actually costs in patience. Cebu Velez General Hospital is a 200-bed Level 3 institution in Cebu City, founded as a small clinic in 1947 and run by the Velez family for generations. AC Health took a majority stake through Healthway Medical Network rather than building greenfield, and the statements around the signing were careful: the family's assistant administrator, James Ting, spoke of strengthening a legacy, and Healthway's chief executive Jimmy Ysmael spoke of referral systems and shared expertise. Fortman Cline Capital Markets advised the sellers. A transaction that needs two advisors and seventy years of family history to close is not a unit you can stamp out on a schedule, which is why the hospital target sits at 10 while the pharmacy target sits at 1,150. Management knows exactly which asset class compounds on time. There is also a demand-side wall the company runs into regardless of model. Healthcare industry surveys in 2026 flag rising patient demand as a concern for 54 percent of Philippine providers and funding and investment barriers for 58 percent (Healthcare Asia Magazine, 2026). Per capita health spending sits near $456 on a PPP basis in 2026, against a national pharmaceutical market of about $3.3 billion and a medical device market of about $747 million (MoveToAsia, 2026). Those are small numbers to carry a claim as large as "transform health for every Filipino." The company is not pretending otherwise; its pharmacy-first footprint is the honest answer to those constraints. The pretense is only in the word order: hospitals first in the sentence, drugstores first in the ledger. Watch the bed count, not the storefront count None of this makes AC Health a bad company. It makes it a legible one. The test for whether the 2027 numbers amount to transformation is mechanical, and anyone can run it: count the hospitals that actually open, then count the pharmacies, and compare the two growth rates against the press releases. If the pharmacy count sails past 1,150 while the hospital count limps toward 10, the "ecosystem" framing was packaging, and the company will have built a very good, very large drugstore business with a hospital Division attached. If the bed count moves first, the skeptics were wrong and the integration story was real. The 2026 calendar already gave us one data point, the Cebu Velez majority stake, which is exactly the kind of purchase a hospital-first reading needs. The next four quarters decide which reading survives. Data basis Data as of November 2026. The share counts, prices and tranche total come from the Ayala Corporation disclosure filed September 1, 2025 under SRC Rule 17-C, which reports 121,089,059 common shares at P4.3013 and 208,275,585 redeemable preferred shares at P4.1972 as the initial tranche of a roughly 16 percent economic stake. Network counts for mid-2025 (236 clinics, 6 hospitals, 880 pharmacies, 1,178 product registrations), 2024 revenue of P9.4 billion and the 2035 goals come from Philippine Daily Inquirer reporting on the company's tenth anniversary. The pharmacy-to-hospital ratios are computed directly from those counts and are simple divisions, not modeled estimates. Payer-side figures (out-of-pocket share of 41.2 percent of total health expenditure in 2025, PhilHealth's 10.6 percent share of expenditure, the 50 percent case rate increase effective January 1, 2025, and payout totals) come from Philippine Statistics Authority data cited in congressional reporting, a PhilHealth Senate hearing reported by GMA News in February 2025, PhilHealth's 2024 annual report, and 2026 reporting on payout levels. Limitations: unit counts are company-reported and unaudited; the 10,000-jobs figure is a government commitment, not an audited outcome; and no per-store or per-bed profitability data is public, so the margin argument rests on the revenue mix and instrument structure rather than disclosed segment profit. Sources Ayala Corporation🔗, SEC Form 17-C disclosure, closing of ABC Impact investment in AC Health, September 1, 2025 Department of Trade and Industry🔗, "DTI: Singapore's ABC Impact to bring 10,000 healthcare jobs in PH," July 16, 2026 PhilHealth🔗, 2024 Annual Report, 2025 corporate operating budget and benefit expansion GMA News🔗, PhilHealth share of health expenditure, Senate hearing, February 2025 Philippine Daily Inquirer🔗, benefit expansion roadmap and 41.2 percent out-of-pocket share, 2026 Situation Report🔗, PhilHealth payouts P83 billion in 2023 to P420 billion target in 2026, August 22, 2026 Daily Tribune🔗, PhilHealth dental coverage and out-of-pocket targets, February 13, 2025 This article was prepared by the expert team at Global Infinity Labs, drawing on insights and data provided through its MCP data services. About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. Email: support@globalinfinitylabs.com
More
A fifth year of eligibility dies at the market-definition stage in the 10th Circuit SeaPRwire

A fifth year of eligibility dies at the market-definition stage in the 10th Circuit

SeaPRwire – The Tenth Circuit ruled on November 6 that college athletes who had already used four seasons of eligibility cannot play the coming season, reversing a July order that had granted them a fifth year. The three-judge panel did not reach the merits of their antitrust claim. It stopped one step earlier, at the definition of the market. The case turns on a question that sounds procedural and decides everything: what market did the NCAA restrain? The athletes said Division I college athletics. The panel said that market does not exist in the form they described. “A labor market is a network of employers whose workers are considered reasonably good substitutes,” Judge Carolyn B. McHugh wrote for the panel, meaning a worker could take a job with any of them. Two facts broke that description. The NCAA does not employ students as athletes, and not every university fields the same sports. The numbers the panel used were blunt. Of 366 Division I universities, 265 have football programs and 63 offer women’s gymnastics. An athlete in either sport cannot treat every Division I school as an alternative employer, because most of them have nothing to offer in that sport. McHugh put the conclusion in one sentence: “Even treating the universities as the employers and discounting any competition from professional sports organizations, however, we are not convinced the market can be defined as all Division I athletics in the United States.” The employer, in the panel’s reading, is the individual athletic program inside a university, not the association and not the membership as a whole. Students sign with a specific school and a specific team. That finding alone ended the case. Antitrust analysis under the Sherman Act moves in sequence, and market definition is the gate before the rule of reason. “In the absence of a plausible market definition, the antitrust challenge to the NCAA’s failure to apply the new rule retroactively cannot proceed to the next analytical steps of the rule of reason,” McHugh wrote. The rule of reason is the stage where the parties argue about whether a restraint’s competitive harm outweighs its justification, and it is expensive: expert reports, economic modelling, discovery into contracts the association would rather not produce. Cases that survive the gate can run for years. Cases that fail it end at the pleading stage, which is what happened here, and it is the outcome most antitrust defendants work toward. The athletes had a second argument, and it is the more interesting one. They said college athletics is a labor market with no comparable substitute, because no professional or amateur league offers the same combination of competition, exposure and pay. If that were true, the market could be defined narrowly and the NCAA’s rule would face scrutiny as a restraint inside it. The panel rejected that framing with testimony from the NCAA’s economist, Matthew Backus. His observation: since name, image and likeness payments began in 2021, fewer underclassmen have entered the NBA and NFL drafts. Backus read that as substitution. Athletes who can earn in college stay in college, which makes Division I sports a reasonable alternative to turning professional. If college and the pros compete for the same labor, the market is the wider world of sports, and college athletics cannot be a market unto itself. Whether that inference holds is a question of fact, and the panel accepted it at the pleading stage. A player choosing between a sophomore season with an NIL deal and a second-round draft position is making an economic comparison, which is what substitution means. Whether the comparison is close enough to merge two markets is the kind of question economists argue about for years. The rule at the center of the case is recent. In June 2026, the NCAA replaced its four-seasons-in-five-years limit with a five-season rule, which folded several overlapping mechanisms into one: the redshirt year, medical hardship waivers and the COVID-19 extensions granted during the pandemic. The class formed in July, made up of athletes who had already completed four seasons and found themselves excluded by the change. Brock Wisne, a basketball player at the University of Northern Colorado, led it. Their theory was that denying a fifth year restrained trade by cutting off another season of NIL income. That theory needed a market in which the lost season had a price, and the panel never reached the price because it never accepted the market. A district court granted a temporary restraining order in July, which is what allowed some athletes to suit up. The Tenth Circuit stayed that order while the appeal ran, then reversed on Friday, which means the NCAA can apply the five-season rule to the class without exception. The practical result is uneven by design. Athletes who transferred or redshirted on the assumption that a fifth year was available now have no route to the floor this season, and the appellate calendar was never going to move fast enough to rescue it. What the panel did not decide matters as much as what it did. The opinion does not say the five-season rule is lawful, only that this challenge cannot get past the market question as pleaded. A differently framed complaint, built around a narrower market such as the market for a specific sport at a specific tier of programs, would face the same gate but with different facts to argue. The NCAA has won a procedural round that it needed, because the alternative was a season played under a rule a court had suspended. Its exposure on the substance is unchanged, and the plaintiffs’ lawyers now know which paragraph of the complaint to rewrite. For the athletes, the loss is a season, which for a college career is a large fraction of the whole. For the doctrine, the useful part of the opinion is the sentence about individual programs as employers, because it tells future plaintiffs how narrowly they have to draw the market before a judge will let them through the gate. No one on either side responded to a request for comment.
More
Physicl raises $10M to sell robot builders a more faithful kind of fake room SeaPRwire

Physicl raises $10M to sell robot builders a more faithful kind of fake room

SeaPRwire – Physicl said on November 6 that it raised $10 million in seed funding led by Inovia Capital. The company sells simulated 3D rooms that robot developers use to generate training data, and its pitch rests on a claim that is simple to state and hard to audit: that a synthetic kitchen can stand in for a real one closely enough to teach a machine how to move through it. Alex de Vigan, the founder and chief executive, arrived from e-commerce. He spent a decade building nfinite, a company that let brands and retailers produce 3D product renders for online storefronts. Transformer-based image models took over most of that work, and the rendering stack his team had assembled lost the market it was built for. “What we were super unique about doing in 3D, AI was going to replace, but something was missing in AI: its ability to understand, interact, and manipulate space and objects,” he said. What went missing was the part of a scene that an image model never has to represent: where surfaces actually are, what they are made of, and how they behave when something pushes against them. A convincing render only has to survive a glance from one fixed camera angle. Robot developers have two established ways to get training data, and both carry costs that compound. Video is abundant, but its returns have frustrated teams working on manipulation of small, varied objects, because footage shows outcomes without showing the forces behind them. Teleoperation produces accurate demonstrations and consumes human hours in proportion to the data collected. Simulation sits between the two. It can generate volume and label it precisely, since the engine already knows every object’s position, mass and material. The difficulty is the gap between the simulated world and the physical one, which shows up as a policy that scores well in a virtual kitchen and stalls on a real counter. Physicl’s argument is that the gap narrows when the scene is reconstructed from measurements of real spaces instead of being authored by an artist, and that the reconstruction preserves what a renderer normally throws away. De Vigan describes the pipeline his previous company built as one that can “transform unstructured, incomplete, heterogeneous real-world information into a high-fidelity physical representation… with correct geometry, materials, and physics.” Studio, the product shipping now, contains 10,000 environments and 100,000 assets. Users assemble scenes and generate synthetic data for a named failure mode: a cup on a cluttered counter-top, or the same cup sitting in shadow. That framing matters. It treats synthetic data as a repair kit for specific weaknesses found during evaluation, not as a substitute for an entire training corpus. That is a narrow brief. It is also the one a robot team can grade. Post-training is where Physicl says it wants to work. The company is not trying to supply the bulk pretraining set that teaches a model general physical intuition. It is aiming at the smaller, more tedious stage where a model that mostly works is corrected on the cases it still fails. SpAItial, which builds world models, used Physicl as an early customer. Its latest product, Echo-3, released last week, generates 3D simulations from 2D imagery. Matthias Niessner, the company’s founder and chief executive and a professor of robotics at the Technical University of Munich, said the fidelity of that output depends on training against high-fidelity synthetic data of the kind Physicl produces. Niessner’s complaint about the current workflow is about labor, not compute. “The real challenge is, you have to curate the data by hand, and this is a very long cycle,” he said. He wants the loop closed. In his description, an agent monitors a training run, notices that one class of scenes is under-represented, and generates more of them while the run is still going. He named Claude as the model in that loop. “That, to me, is super exciting, and this is exactly what Physicl is offering,” he said. De Vigan’s version of the same idea is larger in scale and vaguer in mechanism. He imagines customers feeding in trillions of images or millions of hours of lidar capture, converting them into 3D representations, and then generating billions of permutations from each. “What we created 10 years ago, without knowing it, was basically an agentic workflow to transform unstructured information into high-fidelity 3D,” he said. The category he is entering has no shortage of entrants. Companies collect robot data in factories, record human demonstrations with instrumented gloves, license synthetic scenes, and sell annotation pipelines. Asked about the competition, de Vigan did not claim a technical lead. “The space is very young and very blurry sometimes,” he said. Blurry is the right word for the buyer’s problem. A robotics team evaluating a synthetic data vendor has to answer a question that no demo reel settles: does a policy trained on these scenes perform better on hardware, on tasks it has not seen, than a policy trained on cheaper or older data? That comparison requires a fixed evaluation suite, a consistent robot platform, and weeks of runs. The funding announcement does not include several numbers that would make the claim testable. There is no disclosed pricing, no customer count beyond the single named partner, no statement of how many scenes a typical customer generates, and no measured improvement in real-world task success. Those are the figures that would separate a rendering company with a new market from a data company with a defensible one. Physicl is also selling tooling rather than a finished dataset, which shifts part of the burden to the customer. A team that buys Studio still has to know which failures to target, build the scenes, run the generations, and retrain. The product reduces the cost of producing a specific kind of example. It does not decide which examples are missing. None of that makes the bet unreasonable. The rendering pipeline behind nfinite was built to satisfy retail clients who rejected plastic-looking surfaces, and the same obsession with material accuracy is what simulation for manipulation needs. The question is whether that accuracy survives contact with contact physics, where friction, deformation and compliance decide whether a grasp holds. De Vigan’s own framing suggests he knows where the burden of proof sits. The pitch is not that synthetic worlds replace real ones, but that they cover the cases a real-world collection program would take months to find and label. Whether that holds is a result nobody has published yet, from Physicl or from the customers it says are already using the tooling.
More
The FAA starts retiring its floppy disks, one display system at a time SeaPRwire

The FAA starts retiring its floppy disks, one display system at a time

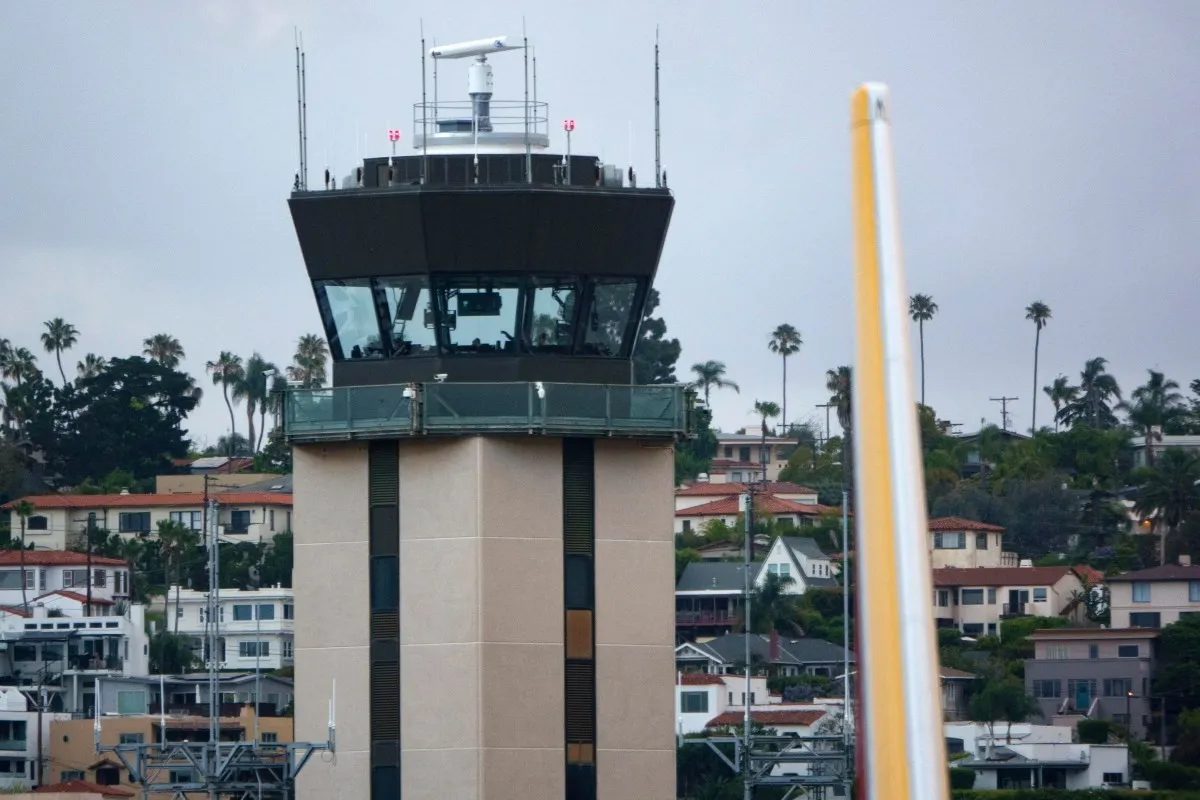
SeaPRwire – The Federal Aviation Administration began replacing 3.5-inch floppy disks at five air traffic facilities this week, the first stage of a program that is meant to reach 435 sites by the end of 2028. The replacement is called the Enterprise Information Display System, or E-IDS, and it consolidates four separate legacy setups onto one digital dashboard. It is the first visible piece of a modernization effort that the agency has been funding and defending for years. What the dashboard carries is the operational detail. Weather alerts, equipment outages, restricted airspace changes and pilot reports currently arrive through a mix of manual relay and physical media, and controllers assemble the picture themselves. E-IDS puts those feeds on a single screen and updates them in place. The five sites named so far are control hubs in Atlantic City, Nashville, Rochester, Atlanta and Salt Lake City. The stated scope covers more than 400 facilities today and 435 at completion. Floppy disks make a good photograph and a poor unit of analysis. A facility that reads weather off a disk and relays it by voice has a latency problem, and latency in a control room is a safety margin being spent. But the disk is a symptom of a procurement cycle that outlived the hardware it bought, not the cause of the delay. The contract history supports that reading. E-IDS was awarded to Leidos, the Reston, Virginia defense contractor, in August 2020. Six years passed in procurement, safety validation, testing and vendor scheduling before the first five sites went live. That gap is the part of the story a ribbon cutting does not explain. An audit published two years into that contract put numbers on the backlog. The Government Accountability Office found in September 2024 that 90 percent of the nation’s critical air traffic infrastructure was due or past due for a technology refresh. Of the 138 systems surveyed, nearly half were judged unsustainable or potentially unsustainable, and the reasons listed were funding shortfalls, thin maintenance expertise and missing spare parts. Missing spare parts is the line worth pausing on. A system kept alive by cannibalizing identical units elsewhere is not a system in service. It is a system in deferral, and the deferral ends when the last donor unit is consumed. That is the arithmetic of a system running out of donors. E-IDS addresses one layer of that backlog, and a comparatively shallow one. A display system is the interface between the controller and the data. It is not the radar, the radio, the flight data processor or the network that carries the feeds. The staffing picture sits outside the program entirely. The agency has been working against a deficit of thousands of certified professional controllers, a shortfall that shows up as mandatory overtime, fatigue and reduced training capacity, since trainee hours depend on certified staff having hours to spare. A dashboard does not staff a tower. Funding for the wider modernization effort is still in motion. The department received a $12.5 billion down payment in 2025 and has been asking Congress for another $30 billion. E-IDS itself sits inside that envelope, which means the schedule depends on appropriations that have not been settled. Appropriations timing also governs how many facilities can be cut over in a fiscal year, which makes the schedule a budget question wearing a technical costume. The rollout pace is the number to track. Five sites are live, and 430 more are planned over roughly two years. That is a facility roughly every other day, across a country with controllers already working overtime, which raises a practical question about who performs the cutover work and whether it happens during low-traffic windows or during the shift. Consolidation also changes the failure surface, and the announcement does not address it. Four separate legacy setups fail separately, which is inefficient and survivable. A single dashboard that aggregates weather, outages, airspace restrictions and pilot reports concentrates the dependency in one place, and the argument for it is the same as the argument against it: everything a controller needs is now in one system. The design question that follows is whether the underlying feeds stay reachable when the aggregation layer does not. A failover path is cheaper to design at the start than to add later. Nothing in the announcement gives a per-site schedule, a cost figure for E-IDS on its own, or a measure of how many manual steps the new system removes. Those omissions matter for oversight, because the program will be judged on whether information reaches controllers faster and with fewer transcription errors, and neither can be established from a list of sites. There is a reasonable case for starting with displays. They are the cheapest layer to modernize, the failures are visible to controllers immediately, and a replacement can be validated against existing procedures without changing the underlying data sources. A program that begins where the feedback is fastest is easier to defend than one that begins with the network. There is a risk in that sequencing, though. A visible modernization at the top of the stack can absorb the political attention that the unglamorous layers need, and the unglamorous layers are where the 2023 NOTAM failure originated. That outage took down a system pilots depend on for pre-flight notices, and it was a software and process failure rather than a hardware one. The controllers who will use E-IDS are the same people being asked to absorb overtime while the system changes underneath them. Training on a new display is not free, and the agency’s own staffing numbers suggest little slack for it. What the program will be measured against, eventually, is whether the information a controller needs arrives without a human relaying it. Five sites will show whether that works in the easy case. The remaining 430 will show whether it works at the pace the schedule requires. For now the record contains a date, a contractor, a facility count and an audit from two years ago. Those are enough to describe the program and not enough to say whether it closes the gap the audit identified.
More
Underdog puts a 31-million-parameter voice model in a browser game and calls it a demo SeaPRwire

Underdog puts a 31-million-parameter voice model in a browser game and calls it a demo

SeaPRwire – Underdog released a browser game on November 6 that speaks back whatever you type into a virtual typewriter. The voice comes from a model the company calls Woof, which ships at 32 megabytes and, according to Underdog, runs on most devices without a network connection. The file size is the announcement. Speech synthesis has mostly been sold as a service, where the model sits in a data center and the audio arrives over the wire. Woof is small enough to be downloaded once and executed on the machine in front of you, with 31 million parameters behind it. Underdog built the demo as a single room: a desk lamp that clicks, a CRT monitor, a typewriter, a music tuner. Type a sentence and the game reads it aloud. Rotate the tuner and it produces tones. The intro warns about “intrusive” cloud providers in the town, which is a marketing line delivered as a joke. Those interactions are worth taking seriously as a specification, because each one rules something out. Speech has to start generating before the sentence is finished, or the typewriter feels broken. The tuner implies pitch and prosody can be controlled at generation time rather than applied afterward. Neither effect needs a cloud round trip, and the demo is designed to make that visible. What the demo does not include is any measurement. There is no word error rate, no mean opinion score, no real-time factor, no latency figure for a mid-range phone, and no comparison against the larger models Underdog’s own copy implicitly benchmarks itself against. A visitor can hear that the voice is intelligible. A buyer cannot tell from the page how far the gap to a hosted system runs, or where it widens. A demo is a claim about a ceiling, not about a floor. Parameter count gives a rough sense of the trade. At 31 million parameters, the acoustic model, the vocoder, the text front end and the training corpus all weigh more on the output than raw size does, and a mistake in any of them is audible. That is why demos of this kind exist. They show the ceiling a small model reaches on a curated script, where the sentences are short, clean and known in advance. The browser also constrains what can be shown. Running in a tab means competing for memory with everything else the user has open, and it means inference has to happen fast enough to keep audio streaming. Underdog says the model runs offline on most devices, but does not say which devices failed that test, or what the memory ceiling is. Power draw belongs in the same list. A voice model running in a tab competes with the display for battery, and on a phone that trade surfaces as heat and throttling. There is a second model in the family, and its size explains the strategy better than the first. Bark, released a few weeks earlier, is a 167 megabyte speech-to-text model aimed at transcription and dictation. Read together, the two cover the two directions of voice: listening and speaking, both on the device, both downloadable. Underdog’s founder, Sigil Wen, framed the work around data ownership. He said he started building the app because he did not want to rely on notetakers such as Granola, and preferred a system where the models run on hardware the user controls. “I think we will be able to run most capable models of today on the devices you already own within months,” he told TechCrunch. “We just want to train the best open models that are American-made, that are open, that are capable and allow people to have private AI.” That last clause is doing more work than the engineering. On-device inference is the only architecture where a privacy claim can be checked by the user, since the audio never leaves the machine. It is also the only architecture where the vendor cannot meter usage, which is why the business model for small models has stayed thin. The 27 billion parameter claim is the one that needs the most scrutiny. A model that size running on a laptop is possible with aggressive quantization and memory mapping, and the practical result depends on how much of the model stays resident, how fast the storage is, and how much quality the compression costs. Underdog has not published those numbers either. Wen’s timeline is the part to hold loosely. Saying that most capable models of today will run on hardware people already own “within months” sets an expectation that the company will be measured against, and the gap between a 32 megabyte voice model and a frontier assistant is not a matter of a few quarters of optimization. Underdog is also selling an app, currently waitlisted, positioned as a locally hosted alternative to Muse and Instinct. That is the commercial shape of the strategy: give away the models as downloads, charge for the experience built on top, and let the privacy argument carry the marketing. It is a shape that has been tried before in other categories of local software, and it tends to produce one of two outcomes. Either the paid layer finds a use that a cloud service cannot serve, usually because the data is too sensitive or the latency too tight, or the free download becomes the whole product and the paid layer never converts. Which of the two happens here depends on whether the app does something the models alone do not, and the announcement does not describe what that is. The demo does its job as a demo. It puts a voice model in front of people with no install step and no account, and it makes an abstract claim about local inference into something you can hear in ten seconds. What it cannot do is answer the question a platform team would ask before standardizing on it: how does this sound on the sentences we actually need, on the phones our users actually carry, and what happens when the text is not a short line typed into a typewriter. Those answers will come from evaluation, not from a game. The fact that the game is charming is not evidence either way.
More
The Philippines Builds Hospitals. The Money Sits at the Pharmacy Counter. SeaPRwire

The Philippines Builds Hospitals. The Money Sits at the Pharmacy Counter.

AC Health targets 10 hospitals, 300 clinics and 1,150 pharmacies by 2027. Its own funding round shows where the margin really lives. SeaPRwire – On September 1, 2025, Ayala Corporation filed a short disclosure with the Philippine Stock Exchange. It recorded a share subscription, not a ribbon-cutting: ABC Impact Fund II LP, a Singapore investor backed by Temasek Trust, subscribed to 121,089,059 common shares at P4.3013 each and 208,275,585 redeemable preferred shares at P4.1972 each, a first tranche of roughly P1.4 billion for an economic stake of about 16 percent in Ayala Healthcare Holdings, the listed conglomerate’s hospital-and-drugstore unit (Ayala Corporation, 2025). The filing carried a promise attached: by 2027, the company called AC Health would run at least 10 hospitals, 300 clinics and 1,150 pharmacies. The company’s own materials repeat those three numbers like a drumbeat. What they never say out loud is that the third number is the business, and the first two are the front door. What the network actually looks like AC Health turned ten in 2025. Its 2025 anniversary materials list the footprint precisely: 236 corporate and multispecialty clinics and 6 hospitals under the Healthway Medical Network, 880 pharmacies across the Generika Drugstore and St. Joseph Drug chains, and 1,178 certificates of product registration under its drug importers, IE Medica and MedEthix (Philippine Daily Inquirer, 2025). Revenue in 2024 was P9.4 billion, up 10 percent from the year before. The provider side grew 22 percent in revenue in 2024, well above the hospital industry’s 8 percent. The pharma side, the company says, outperformed an industry that shrank 5 percent that year. Table 1: AC Health’s stated 2027 network targets against the mid-2025 footprint. Network pillar Mid-2025 actual count 2027 target Growth still needed Hospitals (Healthway Medical Network) 6 10 +4, or 67 percent Clinics (corporate and multispecialty) 236 300 +64, or 27 percent Pharmacies (Generika plus St. Joseph Drug) 880 1,150 +270, or 31 percent Product registrations (IE Medica, MedEthix) 1,178 not stated no public target Source: Philippine Daily Inquirer , tenth-anniversary reporting, 2025. Six hospitals. Eight hundred eighty drugstores. Hold that ratio in your head, because the 2027 target preserves it almost exactly. Ten hospitals, three hundred clinics, one thousand one hundred fifty pharmacies. Between mid-2025 and the 2027 deadline, the hospital count must grow by about 67 percent, the clinic count by 27 percent, and the pharmacy count by 31 percent. None of those three growth rates is exotic on its own. The odd thing is the shape, and the company’s own filing discipline shows it knows the shape matters. The 115-to-1 question Divide the 2027 pharmacy target by the hospital target and you get 115. Do the same to the current footprint and you get about 147. A network that describes itself as an “integrated healthcare ecosystem” carries more than a hundred retail drugstores for every hospital it runs. If the pharmacies existed to feed the hospitals, one or two dozen would do. At this density, the arrow points the other way: the hospitals are the brand that makes the drugstore chain credible. The company’s stated expansion method confirms the reading. ABC Impact’s capital is earmarked for growth “through a combination of organic initiatives and targeted acquisitions” across all three pillars (Ayala Corporation, 2025). Hospitals are the slowest, most capital-hungry item on that list. A 200-bed acute care hospital like Cebu Velez General Hospital, the 1947-era institution AC Health agreed to acquire a majority stake in through Healthway Medical Network in 2025, takes years of construction or a delicate negotiation with a founding family. A pharmacy is a lease and a license. When a 2027 deadline looms, you know which of the two can be added in bulk. Who pays at the counter The structural reason a Philippine healthcare group looks like this lives in the payer mix, not in management preference. Out-of-pocket spending accounted for 41.2 percent of total health expenditures in 2025, according to Philippine Statistics Authority data cited during congressional budget debates (Philippine Daily Inquirer, 2026). The state insurer, PhilHealth, covers 10.6 percent of total health expenditure, and its own leadership told a Senate hearing in February 2025 that it wants that share at 18.5 percent within a few years (GMA News, 2025). Everything else flows through household wallets, and household wallets buy medicine first. A hospital admission is a catastrophe you finance or defer. A box of generic antihypertensives is twelve pesos you pay today. Two things changed in the payer system in 2025, and both matter to AC Health’s plan. First, PhilHealth raised case rates by 50 percent across around 9,000 benefit packages effective January 1, 2025, funded from a P284 billion corporate operating budget of which P271 billion goes to benefit payments (PhilHealth, 2024 annual report). The same budget funds priority packages that read like a list of the most expensive things a Filipino household can face: capitation of P1,700 to P2,100 per person under the KonSulTa primary care program, coverage of 156 hemodialysis sessions at P6,350 per session, and new outpatient coverage for emergency care and mental health. Second, the same budget year carried zero government premium subsidy for indirect contributors, meaning the expansion had to be self-funded. Benefit payouts have surged accordingly: P83 billion in 2023, P330 billion in 2025, and a stated target of P420 billion in 2026 (Situation Report, 2026). If that trajectory holds, the pressure on household wallets eases at the margin, and formal care gets a little less deferrable. The gaps the state leaves open are easiest to see at the counter. PhilHealth’s dental benefit shoulders P1,000 per year for assessment and cleaning across two visits at accredited government clinics, while private dental providers typically charge P1,500 to P1,600 per visit (Daily Tribune, 2025). A benefit that covers less than one private appointment per year is not coverage in any meaningful sense; it is a voucher. Multiply that arithmetic across dermatology, consultations and maintenance medicine, and you have the customer base Generika was built for: people who are insured on paper and self-pay in practice. The pharmacy chain does not compete with PhilHealth. It harvests what PhilHealth does not reach. Now run the arithmetic yourself. If PhilHealth succeeds in cutting out-of-pocket spending to its stated 25 to 30 percent goal, more drug purchases shift to prescriptions attached to formal care, and pharmacy footfall follows prescriptions rather than impulse. That helps a chain with an integrated distributor. If PhilHealth stalls, the current model works exactly as built, because patients keep paying cash at the counter. The pharmacy-heavy shape wins in both branches. That is not a criticism of the strategy; it is the reason the strategy is what it is. A network built for the world’s most common Philippine patient, the one paying out of pocket, is a drugstore network with hospitals attached. A demand shock the plan does not advertise There is a third variable in the structure, and it is not friendly. In 2025 the Department of Health declared a national public health emergency over HIV, with infections among people aged 15 to 25 reported up 500 percent, rising from about six recorded cases per day in 2010 to between 40 and 57 new cases each day in 2025 (Philippine Daily Inquirer, 2025). AC Health has responded by pushing proactive HIV screening through workplaces, schools and communities, with its Healthway Cancer Care Hospital handling vaccination, early diagnosis and treatment. Ho, the public health expert quoted in the company’s anniversary materials, put the division of labor plainly: “The government and civil society organizations have made significant progress in addressing the HIV epidemic. But with this looming public health emergency, the private sector must step up to complement existing efforts and help scale proven interventions.” Set the epidemiology next to the expansion arithmetic and a tension appears. An integrated network profits from volume through its clinics and counters, and an infectious-disease surge among working-age Filipinos generates exactly that volume, in screening visits, lab work and chronic care. Nobody at the company said the quiet part, and none of the funding documents mention it. But a healthcare group scaling drugstores at 31 percent while its home market handles an outbreak among 15-to-25-year-olds is a company whose growth model and whose social problem have started to move in the same direction. That is either a tragedy of alignment or a business model working as designed, depending on how much cynicism you brought with you. If that were true The pitch around the funding round used the word “impact” repeatedly. David Heng, chief executive of ABC Impact, said the firm believes AC Health is “well positioned to deliver meaningful social outcomes alongside sustainable growth” (BusinessWorld, 2025). Fair enough. The firm manages more than $900 million in assets and its portfolio carries recognizable names: Kim Dental, the largest private dental network in Vietnam; DCDC Kidney Care, an Indian dialysis provider running more than 200 centers across underserved regions; and HiRo, a clinical research organization serving mid-sized pharmaceutical and biotech companies across Asia Pacific and the United States. First direct entry into Philippine healthcare, a market of 116 million insured-on-paper residents, from a fund with that playbook is not a lottery ticket. It is a pattern trade. But look at the instruments in the same disclosure. Of the 329 million shares subscribed on September 1, 2025, 208.3 million were redeemable preferred shares, a class that typically carries priority on payouts and a redemption path, paired with a warrant instrument and a shareholders’ agreement signed the same day. The “16 percent stake” is an economic interest with real structure around it. If the social mission were the whole story, the money could have bought plain common shares. It did not, and the instrument choice says the investor priced downside protection into a deal marketed as conviction. The company retained Bank of America Securities as exclusive financial advisor, which is what you do when the negotiation is hard, not when it is ceremonial. The company’s counterargument would be that first institutional money into a young market buys protection, and that Temasek-linked capital taking any Philippine healthcare exposure is itself the signal. Both things can be true. What the structure does tell you is the order of operations: build the pharma and distribution base that produces cash, use the impact capital to underwrite the expensive hospital bets, and let the 2027 headline numbers bundle the two into one story. In July 2026, the story got a presidential assist. During Ferdinand Marcos Jr.’s working visit to Singapore, the Department of Trade and Industry announced the expansion is expected to support around 10,000 direct healthcare and retail jobs by 2027 (DTI, 2026). Note the word “retail” sitting quietly next to “healthcare” in that sentence. The department counted honestly. The headlines did not. What this buys the patient To be fair to management, the integrated model has real content. Generika Drugstore is the country’s pioneer in generic retail. IE Medica and MedEthix import and distribute pharmaceuticals at scale. St. Joseph Drug anchors North and Central Luzon. Owning the importer, the distributor and the counter means a generic drug moves through one margin stack instead of three, which is how a chain can sell generics cheaply and still clear the 31 percent store-count expansion it has scheduled. Management’s long-range goal, stated at the anniversary, is a $2 billion healthcare enterprise serving one in five Filipinos by 2035 (Philippine Daily Inquirer, 2025). One in five is a reachable fraction for a pharmacy chain and an unreachable one for a hospital group at current build rates. The stated dream and the feasible plan quietly agree with that reading. The Cebu Velez deal shows what the hospital leg of the plan actually costs in patience. Cebu Velez General Hospital is a 200-bed Level 3 institution in Cebu City, founded as a small clinic in 1947 and run by the Velez family for generations. AC Health took a majority stake through Healthway Medical Network rather than building greenfield, and the statements around the signing were careful: the family’s assistant administrator, James Ting, spoke of strengthening a legacy, and Healthway’s chief executive Jimmy Ysmael spoke of referral systems and shared expertise. Fortman Cline Capital Markets advised the sellers. A transaction that needs two advisors and seventy years of family history to close is not a unit you can stamp out on a schedule, which is why the hospital target sits at 10 while the pharmacy target sits at 1,150. Management knows exactly which asset class compounds on time. There is also a demand-side wall the company runs into regardless of model. Healthcare industry surveys in 2026 flag rising patient demand as a concern for 54 percent of Philippine providers and funding and investment barriers for 58 percent (Healthcare Asia Magazine, 2026). Per capita health spending sits near $456 on a PPP basis in 2026, against a national pharmaceutical market of about $3.3 billion and a medical device market of about $747 million (MoveToAsia, 2026). Those are small numbers to carry a claim as large as “transform health for every Filipino.” The company is not pretending otherwise; its pharmacy-first footprint is the honest answer to those constraints. The pretense is only in the word order: hospitals first in the sentence, drugstores first in the ledger. Watch the bed count, not the storefront count None of this makes AC Health a bad company. It makes it a legible one. The test for whether the 2027 numbers amount to transformation is mechanical, and anyone can run it: count the hospitals that actually open, then count the pharmacies, and compare the two growth rates against the press releases. If the pharmacy count sails past 1,150 while the hospital count limps toward 10, the “ecosystem” framing was packaging, and the company will have built a very good, very large drugstore business with a hospital Division attached. If the bed count moves first, the skeptics were wrong and the integration story was real. The 2026 calendar already gave us one data point, the Cebu Velez majority stake, which is exactly the kind of purchase a hospital-first reading needs. The next four quarters decide which reading survives. Data basis Data as of November 2026. The share counts, prices and tranche total come from the Ayala Corporation disclosure filed September 1, 2025 under SRC Rule 17-C, which reports 121,089,059 common shares at P4.3013 and 208,275,585 redeemable preferred shares at P4.1972 as the initial tranche of a roughly 16 percent economic stake. Network counts for mid-2025 (236 clinics, 6 hospitals, 880 pharmacies, 1,178 product registrations), 2024 revenue of P9.4 billion and the 2035 goals come from Philippine Daily Inquirer reporting on the company’s tenth anniversary. The pharmacy-to-hospital ratios are computed directly from those counts and are simple divisions, not modeled estimates. Payer-side figures (out-of-pocket share of 41.2 percent of total health expenditure in 2025, PhilHealth’s 10.6 percent share of expenditure, the 50 percent case rate increase effective January 1, 2025, and payout totals) come from Philippine Statistics Authority data cited in congressional reporting, a PhilHealth Senate hearing reported by GMA News in February 2025, PhilHealth’s 2024 annual report, and 2026 reporting on payout levels. Limitations: unit counts are company-reported and unaudited; the 10,000-jobs figure is a government commitment, not an audited outcome; and no per-store or per-bed profitability data is public, so the margin argument rests on the revenue mix and instrument structure rather than disclosed segment profit. Sources Ayala Corporation , SEC Form 17-C disclosure, closing of ABC Impact investment in AC Health, September 1, 2025 Department of Trade and Industry , “DTI: Singapore’s ABC Impact to bring 10,000 healthcare jobs in PH,” July 16, 2026 PhilHealth , 2024 Annual Report, 2025 corporate operating budget and benefit expansion GMA News , PhilHealth share of health expenditure, Senate hearing, February 2025 Philippine Daily Inquirer , benefit expansion roadmap and 41.2 percent out-of-pocket share, 2026 Situation Report , PhilHealth payouts P83 billion in 2023 to P420 billion target in 2026, August 22, 2026 Daily Tribune , PhilHealth dental coverage and out-of-pocket targets, February 13, 2025 This article was prepared by the expert team at Global Infinity Labs, drawing on insights and data provided through its MCP data services. About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. Email: support@globalinfinitylabs.com
More
Singapore’s Market Cooled. The Landed Segment Never Got the Memo. SeaPRwire

Singapore’s Market Cooled. The Landed Segment Never Got the Memo.

URA’s Q2 2026 print: private prices up 0.5 percent QoQ, HDB resale down two straight quarters, while CCR landed rose 20.9 percent year on year. SeaPRwire – The flash estimate went up on the Urban Redevelopment Authority’s website in the last week of June 2026, and the headline behaved exactly as expected: private residential prices rose 0.5 percent quarter on quarter, the smallest gain in seven quarters (URA, 2026). Three weeks later the final data landed and confirmed the number to one decimal place. On its face, that is a boring quarter, a market gliding into a cool patch after years of cooling measures. The boring reading lasts exactly as long as it takes to open the appendix. In the same final dataset, prime core central region non-landed homes rose 1.8 percent in the quarter, the rest of central region fell 1.8 percent, and outside central region slipped 0.1 percent. The average said cooldown. The segments said three different markets wearing one coat. The official story, quoted as issued Start with what the agencies actually published, because an audit that paraphrases its subject has already failed. The URA final series for Q2 2026 shows the private residential price index up 0.5 percent from Q1, bringing the first-half 2026 gain to 1.4 percent, against 1.8 percent in the same stretch of 2025 (URA via EdgeProp, 2026). Landed properties rose 2.5 percent on the quarter. Non-landed rose, on the aggregate, 0.0 percent at minus 0.1, which rounds the story to flat. The Housing and Development Board’s resale index, published the same cycle, fell 0.3 percent to 202.7, its second consecutive quarterly decline, something the resale market had not done in about seven years (HDB via PropertyNet, 2026). Volume tells its own part. Developers sold 2,141 new private units in Q2 2026, up from 2,013 in Q1. Resale transactions in the private market ran 2,634 units. HDB resale deals came to 6,268. None of those is a collapse; all of them are consistent with a market that is digesting rather than racing. The take-up rate on new launches stood at 77.5 percent in the quarter, healthy by any post-2018 standard. Before dismantling the average, note the deceleration the official series itself documents. The composite rose 0.9 percent in Q1 2026 and 0.5 percent in Q2. First-half 2026 therefore ran 1.4 percent against 1.8 percent in the first half of 2025, the smallest half-year gain since 2020 (URA via EdgeProp, 2026). That is a real, dated, publishable slowdown, and no audit changes it. The question is only who is inside the average when it moves, and the answer turns out to be: almost nobody you would guess from the headlines. A quarter of whiplash in landed The landed series, measured on its own, did something the composite never hinted at. In Q1 2026, landed prices fell 0.4 percent on the quarter. In Q2, they rose 2.5 percent. That is a 2.9 point swing in a single quarter, inside a market the headline described as gently cooling (URA final data via EdgeProp, 2026). Run the same check on the prime landed valuation that PropNex tracks and the whiplash resolves upward: core central region landed prices were up 20.9 percent year on year in the first half of 2026, on 869 transactions worth about S$5.4 billion across the half. The quarter-on-quarter dip in Q1 was noise inside a year of steep gains, and the composite average carried no trace of either direction. This is the part of the audit where the official claim gets its strongest defense. The URA never said landed was cooling. It published a composite, and the composite was computed correctly. The failure happens downstream, in every summary that swapped “the composite decelerated” for “the market cooled.” Between those two sentences sits a real transaction: a family paying several million dollars for a detached house in District 10 in June 2026 paid a price, on trend, that no part of the 0.5 percent headline describes. Taking the average apart Now do what the flash release could not do, which is hold the components against the whole. The 0.5 percent headline is a weighted composite of landed plus 2.5, core central non-landed plus 1.8, rest of central non-landed minus 1.8 and outside central non-landed minus 0.1. A composite can only land near zero-plus if the declining segments carry most of the weight, and they do, because volume lives in the suburbs. Roughly speaking, the mass-market outside central region is where the transactions are, so a 0.1 percent dip there and a 1.8 percent slide in the rest of central are what the average is actually averaging. The 1.8 percent jump in core central is real, but it moves the citywide index by a rounding error because so few transactions sit in that bucket. This is where the denominator matters, and the audit hinges on one distinction. The index is price per square meter of transacted stock. It is not average transaction value, and it is not sales volume. A quarter in which CCR prices rise 1.8 percent while its transaction count stays small produces a big percentage in a corner of the table and almost nothing in the headline. Reading the headline as “the market cooled” is a category error with consequences: a buyer waiting for prime prices to follow the composite down is waiting for a signal the composite does not carry. The landed segment, measured properly The landed market deserves its own ledger, because it is where the divergence turns extreme. In the first half of 2026, 869 landed transactions closed for about S$5.4 billion in value (PropNex via Singapore Business Review, 2026). Prices in the core central region landed segment rose 20.9 percent year on year in the first half. Set that beside the citywide private composite of plus 1.4 percent for the same half and the two numbers cannot both be describing the same thing, and they are not: one is a segment with dozens of transactions a month and wide dispersion between a detached house and a terrace, the other is a 0.5 percent-per-quarter composite smoothed across everything. Small denominators make violent percentages. A 20.9 percent year-on-year print on a thin, lumpy market is genuine signal and genuine noise at once, and the only honest treatment is to report both properties. Table 1: URA flash estimates versus final data for Q2 2026, percentage change quarter on quarter, for the segments published in both releases. Segment (Q2 2026) QoQ change (final) Flash estimate Gap, percentage points Core central region, non-landed +1.8% +2.0% 0.2 Landed, all regions +2.5% +2.6% 0.1 Rest of central region, non-landed -1.8% not carried in flash table – Outside central region, non-landed -0.1% not carried in flash table – Source: Urban Redevelopment Authority , press release pr26-69, June 2026. That table carries the audit’s sharpest finding. Every zone that published both a flash and a final number was revised down between them, by 0.1 to 0.2 percentage points. The conflict record built from URA’s own publications flags that all four market segments printed inconsistently between the two releases (URA flash versus final, Q2 2026). A 0.2 point revision on a 0.5 point headline is not trivia; it is 40 percent of the reported move, created entirely by estimation timing rather than by any transaction. Anyone who reacted to the June flash with the word “cooling” and did not re-read in July consumed a number that shrank on arrival between draft and final. The public housing half of the ledger The public housing half of the ledger runs in the opposite direction from the landed one, and the two together are what “the market” actually means in Singapore. The resale index fell 0.3 percent in Q2 2026 to 202.7, the second consecutive decline, on 6,268 transactions (HDB via PropertyNet, 2026). Supply mechanics explain most of it: 13,484 Build-To-Order flats reached their minimum occupation period in 2026, unlocking them for resale, and the October 2026 BTO launch added another 7,960 units to the pipeline. When a wave of flats ages into eligibility at the same time that the state launches new supply in bulk, resale prices flatten. That is policy working, not demand dying. The mechanics are worth spelling out, because they carry no analogue in most housing markets. A Singapore flat bought directly from the state cannot be resold for five years, the minimum occupation period, so the resale stock in any year is fixed by the cohort that finished construction five years earlier and has not yet sold. The 2026 cohort is large, hence 13,484 newly eligible units. Add the state’s own launch calendar, which put 7,960 new BTO flats on the market in October 2026 alone, and both the substitute good and the new good arrive at once. A resale index falling 0.3 percent in that environment is what a functioning rationing system looks like. Compare the private rental market, which has no such valve and rose 0.7 percent on the quarter in Q2 2026, and the two indexes tell you the pressure did not vanish; it moved to where the valve was closed. The land side of the private market is also scheduled, not spontaneous. The Government Land Sale programme for 2026 carries 9,320 units, and the completion pipeline holds about 61,000 private homes (URA via AsianPrime, 2026). Against that, the three-month compounded SORA rate sits near 1.05 percent in 2026, so financing costs are not the villain of this scene. The composite index is drifting through a supply phase: enough land, enough completions, cheap enough money, and a resale wave in public housing that keeps the entry rung affordable. None of that requires prime landed property to cool, because none of that supply lands in the CCR landed bucket. The Government Land Sale is worth a moment of attention on its own, since it is the single lever with the longest reach: the state decides years in advance how many sites go to tender, where, and on what reserve, which means the quantity side of the private market in 2026 was largely settled by decisions taken while interest rates were still elevated. Where the new-sale volume actually sits One more number belongs in the audit before the verdict, because it explains why quarterly composites are so jumpy. Of the 2,141 units developers moved in Q2 2026, 67.5 percent came from just three projects (URA via EdgeProp, 2026). The new-sale market in Singapore is a launch market: a quarter’s demand is whatever a handful of well-located, well-timed projects attracted that quarter, priced against the previous quarter’s benchmark. Three projects selling well can lift the composite; three quiet launch weekends can flatten it. The index measures that lumpy process with real precision, which is exactly why reading it as a smooth temperature reading misleads. Layer the take-up rate on top. New launches in Q2 2026 absorbed 77.5 percent of units sold within the launch window, a figure that sits comfortably in the range Singapore has treated as robust since the 2018 cooling measures. So the quarter behind the 0.5 percent headline contains: a record-heavy concentration of demand in three projects, a healthy launch absorption rate, falling mass-market condominium prices in two of three regions, and a prime landed market running at 20.9 percent annual growth. No single sentence can carry all of that. The headline carries the least of it, by construction. What cannot simultaneously be true The audit’s deliverable is the list of claims that break each other. One: “Singapore private home prices are cooling,” true of the composite for two quarters and false of landed property, which accelerated. Two: “the HDB resale slide shows demand weakness,” false as stated, because the same cycle delivered 6,268 resale transactions and a 77.5 percent launch take-up rate; the index fell on supply, not on absent buyers. Three: “the flash and final data tell the same story,” false at the level that matters, since every revisable component moved 0.1 to 0.2 points between the two releases. None of these is a data error. All of them are cases where a single unqualified sentence does work the underlying numbers cannot support. The verdict, then, is a shrinking of the claim, not a contradiction of it. Q2 2026 was a cool quarter for the composite, a flat-to-falling quarter for mass-market condominiums, a soft quarter for HDB resale driven by MOP supply, and a hot quarter for prime landed homes. The average was never wrong. It was answering a question about a market that only exists after aggregation, and most readers brought a question about the segment they actually shop in. The heart of the exercise is the same discipline a buyer applies in person: check the revision trail, check the denominator, and only then quote the number. Where the next quarter’s signal sits If you want one number to arbitrate between the two readings, skip the composite and watch CCR non-landed against OCR: the spread between them widened from near zero to roughly two points of quarterly growth in Q2 2026, and convergence would mean the composite finally describes both worlds. On the public side, watch whether the resale index keeps falling once the 13,484-unit MOP cohort is fully absorbed, or finds a floor as the newly eligible stock finds buyers. Watch the launch calendar too, because with 9,320 GLS units scheduled for 2026 and 61,000 homes in the completion pipeline, the supply side of the composite is already on the books, not speculative. And hold every flash estimate at arm’s length until the final print, because this cycle’s revisions ran one way, downward, in all four segments. A market this segmented does not produce one story per quarter. It produces four, and the headline is only the least informative among them. Methodology Data as of November 2026. Price changes are quarter-on-quarter percentage moves of the URA private residential price index and the HDB resale price index, taken from final data unless marked flash; the flash figures come from URA press release pr26-69 and the finals from the completed Q2 2026 release as republished by EdgeProp and PropertyNet. The transaction counts (2,141 developer sales, 2,634 private resales, 6,268 HDB resales) are quarterly unit counts for Q2 2026 from the same publications. The 20.9 percent landed figure is a year-on-year change for the first half of 2026 in the CCR landed segment, computed by PropNex, not by this analysis; it is quoted in its original basis and not recomputed. The pharmacy of this exercise, if it can be named, is the revision gap: flash minus final, in percentage points, per segment. Limitations: segment weights in the URA composite are not published at transaction level in the sources used, so the weight explanation is directional rather than exact; the landed transaction sample is small and dominated by high-value lots, which inflates variance; and marketplace conventions differ between the URA and HDB index families, so their levels (index points) are never compared directly, only their directions. Sources Urban Redevelopment Authority , press release pr26-69, Q2 2026 private residential price flash estimates, June 2026 EdgeProp Singapore , URA final Q2 2026 data coverage, July 24, 2026 PropertyNet , Q2 2026 URA and HDB resale coverage, July 1, 2026 Singapore Business Review , landed home sales S$5.4 billion in 1H 2026, June 7, 2026 Housing and Development Board , Q2 2026 resale index and transaction data, accessed November 2026 (site home) This article was prepared by the expert team at Global Infinity Labs, drawing on insights and data provided through its MCP data services. About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. Email: support@globalinfinitylabs.com
More
Saudi Arabia Hit 85% Digital: The Rails Under the Card Are Next SeaPRwire

Saudi Arabia Hit 85% Digital: The Rails Under the Card Are Next

sarie instant volumes, SAMA’s March 2026 open banking licences and Mada e-commerce growth of 32.3 percent are setting up a squeeze on card and ATM economics. AsiaPresswire – Saudi Arabia crossed its cashless finish line quietly. Electronic payments covered 85 percent of retail transaction volume in 2025, up from 79 percent in 2024 and 70 percent in 2023, according to figures published through the Saudi Central Bank’s statistical bulletin (SAMA via Arab News, 2025). The Vision 2030 target of 70 percent non-cash was reached in 2023, two years early, and the share has kept climbing since. On paper, this is the success phase of a national payments story: cash retreating, cards everywhere, terminals multiplying. In practice, the milestone changes the question. When nearly everyone already pays digitally, growth in the system no longer comes from converting cash users. It comes from moving activity between digital rails, and that contest has winners that look nothing like the card networks that built the first phase. The numbers behind the milestone The scale first. In the first quarter of 2026, the SARIE real-time gross settlement system, the wholesale rail that has existed since 1997, moved SR17.78 trillion in total value, up 16.1 percent year on year, of which SR12.74 trillion was interbank settlement and SR4.50 trillion was customer payments (SAMA Q1 2026 report, 2026). The retail layer that sits on top processed 2.98 billion POS transactions in the same quarter, against 359 million ATM withdrawals and a card base of 66.9 million issued cards. Across the full year 2025, electronic payments totaled 14.6 billion transactions, up from 12.6 billion in 2024, of which POS accounted for 11.5 billion (SAMA bulletin via Arab News, 2025). Cash has not vanished: SR393.8 billion was still withdrawn from machines across 2025. Those four figures together describe an economy where the default transaction is electronic, and the ATM is an edge case rather than a habit. The instant rail is the part growing fastest. The lowercase sarie instant payment system, launched by SAMA on February 21, 2021, handled 784 million transactions in 2025, up 32 percent year on year (SAMA, 2025). By August 2026 the monthly run rate reached 93.7 million transactions worth SR96.87 billion (SAMA bulletin via Arab News, 2026). In June 2026 the instant system’s total volume was up 26.1 percent year on year. Growth at that pace, three years after launch, is not a novelty curve. It is a rail becoming infrastructure. Table 1: Channel split of Saudi retail payment activity across the most recent reported periods. Channel (Saudi Arabia) Latest measured period Volume or value Year-on-year change sarie instant payments full-year 2025 784 million transactions +32% sarie instant payments August 2026 93.7 million transactions, SR96.87 billion monthly run rate Mada e-commerce sales Q2 2026 SR101.4 billion +32.3% POS sales, all retail Q2 2026 SR170.1 billion -4.8% QoQ, +6.8% YoY in July ATM withdrawals Q1 2026 359 million transactions edge channel Electronic share of retail payments full-year 2025 85 percent +6 points from 2024 Source: Saudi Central Bank , monthly statistical bulletins and Q1 2026 report, 2025 to 2026. The structural variable: a second, cheaper checkout The variable that decides the next five years is not whether Saudis pay digitally. It is which account-to-account path the transaction takes when they do. Two regulatory facts define it. First, SAMA began issuing live open banking licences in March 2026 after the sandbox phase closed, and the framework covers payment initiation as well as account information (TechScoop, 2026). Payment initiation is the consequential half: it lets a licensed third party instruct a payment directly from a customer’s bank account, routing the transaction around the card networks entirely. Second, the instant rail underneath it is already fast, cheap to operate and owned by the central bank rather than by a scheme that charges per swipe. On paper, a licensed payment-initiation service is one product among many. In practice, it is a price challenge to the acquiring side of the card business. A merchant paying card fees on high volumes of low-margin transactions has, for the first time in the Kingdom, a regulated alternative at checkout: the customer authorizes from a bank account, settlement lands through sarie, and the interchange and scheme fees fall out of the transaction. The merchant does not care that the money arrived by a different rail. The acquirer very much does. The e-commerce channel is where that alternative gets its test, and the volume base is already large. Mada cards carried 566 million e-commerce transactions in Q2 2026 alone, worth more than SR101 billion (SAMA bulletin via Saudi Gazette, 2026). Every one of those transactions today runs as a card payment: card entered or tokenized, authenticated, interchange charged, settled in batches. A payment-initiation checkout replaces that sequence with an account authorization and an instant transfer. The economics of the two sequences differ by the fees that disappear, and the user experience differs by a redirect instead of a card form. Bill payments already run on a separate national spine, SADAD, which handles utility and government receivables from inside banking apps; the checkout is the last large consumer surface still owned by the card sequence, which is why the March 2026 licence matters more in e-commerce than anywhere else. Where the pressure shows up first The migration will not announce itself as a single event. It shows up as a widening spread between the online and physical halves of the card world, and between transaction counts and transaction values. Both spreads are already open. Mada e-commerce sales reached SR101.4 billion in Q2 2026, up 32.3 percent from SR76.6 billion a year earlier, while POS sales in the same quarter fell 4.8 percent from Q1 to SR170.1 billion and grew only 6.8 percent year on year in July (SAMA bulletin via Saudi Gazette, 2026). E-commerce is where volume is going, and checkout is where the payment-initiation alternative bites first, because an online checkout is just a redirect away from an account payment. The second leading indicator is the terminal count running against the value it carries. POS terminals rose slightly to 2.45 million in Q2 2026 from 2.40 million in Q1, yet POS value fell 4.8 percent on the quarter. More terminals, less value per terminal is the signature of a channel being defended rather than grown. The third is the ATM line: 359 million withdrawals in Q1 2026 against 2.98 billion POS transactions, a ratio that keeps compressing as cash use retreats. None of these three is conclusive alone. Together they describe where the marginal transaction is landing, and it is not the swipe. The two indicators worth watching are independent of each other, which is what makes them usable. sarie instant volume growth measures consumer and business adoption of the account-to-account rail; Mada e-commerce growth against POS growth measures where checkout demand sits. The card-squeeze thesis needs both to keep moving. If sarie volumes keep compounding at 25 to 30 percent while open banking payment-initiation volumes scale, the thesis holds. If either one stalls, the squeeze stalls with it. Why the instant rail won its first market so fast The instant system did not grow 32 percent in 2025 because consumers discovered novelty. It grew because of a price list. At launch in February 2021, SAMA set the sarie single-transfer ceiling at SAR 20,000, the express transfer limit at SAR 2,500, and the maximum customer fee at SAR 1 per transfer (SAMA Rulebook via SPA, 2021). One riyal, any hour, any bank, versus a card acceptance stack with hardware, acquiring fees and settlement lag. For person-to-person money movement, the contest was over before it started. Five years later the rail that cost one riyal to ride is moving 93.7 million transactions a month. The domestic card scheme complicates any simple card-versus-instant framing, and the analyst has to keep both threads. Mada, the national debit network operated under SAMA’s supervision, processed more than 8 billion transactions across 2025 and remains the workhorse of physical retail, with 2.45 million POS terminals deployed by Q2 2026 (SAMA, 2026). In August 2025 alone, Mada e-commerce moved SR36.95 billion across 196.9 million transactions (SAMA bulletin via Arab News, 2025). So the card rail is not dying; it is absorbing the e-commerce wave first. The structural question is what happens in the next wave, when a licensed payment-initiation checkout can present the account itself as the payment method at the same online counters that taught consumers to pay without swiping. Around both rails, the wallet layer thickened. By 2026 the licensed wallet and instant-payment consumer brands included STC Pay, Hala, Barq, UrPay, Mobily Pay, Tiqmo and Alinma Pay, several of them bank-owned, several telecom-owned, all riding the same instant infrastructure (Economy Middle East, 2026). This is the quiet difference between Saudi Arabia and markets where instant payment adoption dragged: the consumer habit of paying from an account, rather than from a stored card, was built in the last five years rather than the last fifty. Europe’s open banking has struggled commercially partly because it retrofitted account payments onto decades of card habit. Saudi Arabia is building account-first checkout onto a population that never formed deep card habits in the first place. The switch cost is lower here than almost anywhere else at comparable income levels. The money and the mandate Two capital facts frame how fast the checkout shift can run. The official one: Saudi fintech’s projected contribution to GDP is set at SAR 13.3 billion by 2030, against SAR 1.2 billion in 2021, an explicit government target rather than a market estimate (Economy Middle East, 2026). The market one: venture funding in Saudi Arabia fell 74 percent year on year in the first half of 2026, and fintech’s share of what remained rose from 28 percent to 67 percent (MAGNiTT via TechScoop, 2026). Read together, the state is underwriting the category’s long arc while private capital concentrates into fewer, later-stage bets. Payment initiation sits exactly where those two forces meet: it is the licensed product category the state has authorized and the revenue category investors are still funding when everything else contracts. That concentration has a hard edge. A 74 percent contraction in available venture capital means the open banking startups building payment-initiation checkouts are not racing each other on growth; they are racing to demonstrate transaction volume that justifies a later-stage round. Their incentive is to push adoption at merchants as fast as licensing allows, which serves the migration thesis. The same contraction means the number of companies able to execute is small, so the shift is likelier to arrive through two or three well-capitalized checkout providers than through a hundred experiments. For the acquirers watching their fee pool, a small number of visible competitors is easier to price than a swarm, but easier to negotiate with too. Who carries the loss first The first losses land on the cash economy’s remaining service layer, which is mostly a bank cost line rather than a revenue line: ATM fleets, cash-in-transit contracts, branch teller time. That migration is a relief for bank margins, not a threat. The second group is more exposed: merchant acquirers and terminal deployment businesses whose model assumes card-present volume keeps growing into the terminal base they financed. A 4.8 percent quarterly decline in POS value while terminals expand is what the front of that looks like. The third group, the international card schemes, loses last and least in consumer debit, because mada, the domestic debit scheme, dominates the Kingdom’s card base anyway; their real exposure is the interchange they never collected in the first place and the e-commerce mix shifting to rails they do not operate. Banks sit on both sides of the ledger, which is why their behavior is ambiguous. Open banking turns their customer relationship into infrastructure that licensed third parties can build on, a competitive loss. But the same banks operate the accounts that sarie payments land in, and they save the acquiring-side cost when settlement is internal. The Saudi banking sector is concentrated in a small number of large institutions, which makes the coordination problem of raising everyone to an open banking standard tractable, and it also means no single bank can defect from the standard without isolating itself. The result is a sector that will implement the rails that erode its own card fees, because the alternative is watching a licensed competitor do it. The remittance corridor is the adjacent market worth naming, because it shows the same structural logic already priced in. Saudi Arabia hosts one of the world’s largest expatriate workforces, and outward remittances have historically flowed through correspondent banking with meaningful fees per transfer. The instant rail does not itself settle cross-border, but the same central-bank-owned infrastructure mindset is extending outward, and several MENA central banks are benchmarking the sarie architecture as they build their own real-time systems (Economy Middle East, 2026). A domestic instant rail that residents trust is the first step in a corridor business: the money still crosses a border, but the customer experience, the authorization and the fee expectation are all set by the account-to-account habit. Card networks do not collect on any of that. The signals that would falsify this The judgment here is refutable in three specific ways, and each has a named meter. If SAMA’s open banking statistics show payment-initiation transaction counts staying immaterial through 2027, the regulatory permission was real but the checkout shift is not, and the card economics stand. If POS terminal counts keep rising while POS value per terminal stabilizes and resumes growth, the acquiring business is still expanding, not defending. If sarie instant transaction growth decelerates below POS growth for two consecutive quarters, the instant rail is plateauing as a peer-to-peer convenience rather than becoming a checkout rail. Any one of those three breaks the thesis. As of the latest bulletins, all three are running the other way. Data basis Data as of November 2026. Electronic share of retail payments (70 percent in 2023, 79 percent in 2024, 85 percent in 2025) comes from SAMA statistical bulletins as reported through Arab News. SARIE wholesale values, POS, ATM and card counts for Q1 2026 come from the SAMA Q1 2026 report. sarie instant launch date, transaction counts and growth rates come from SAMA publications covering February 2021 through August 2026. Mada e-commerce and POS quarterly and monthly values for 2026 come from the SAMA monthly statistical bulletin as republished by Saudi Gazette. The open banking licensing date and the distinction between account information and payment initiation services come from coverage of the March 2026 licence announcement. Measure types are actuals throughout; no forecast values are used, and the 2026 growth figures are year-on-year or quarter-on-quarter changes of measured values, not projections. Limitations: SAMA’s published open banking usage statistics were not yet detailed enough at drafting time to size payment-initiation volumes directly, so that variable is treated directionally; POS sector composition effects on the Q2 dip are not decomposable from public bulletins; and the terminal count is a stock while value is a flow, so the per-terminal comparison is indicative rather than exact. Sources Saudi Central Bank , monthly statistical bulletins and Q1 2026 payments system report, 2025 to 2026 (site home) Saudi Gazette , Mada e-commerce SR101.4 billion in Q2 2026 and POS trends, September 2026 Arab News , SAMA bulletin coverage: 85 percent electronic share of retail payments in 2025 (site home) TechScoop , SAMA open banking first live licences, March 2026 Economy Middle East , Vision 2030 non-cash target reached 2023, 2026 This article was prepared by the expert team at Global Infinity Labs, drawing on insights and data provided through its MCP data services. About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. Email: support@globalinfinitylabs.com
More
Crossed $100,000 in One State? Forty-Two More Are Counting SeaPRwire

Crossed $100,000 in One State? Forty-Two More Are Counting

Economic nexus rules in 2026, the published price of TaxJar, Avalara and managed filing, and the real cost of the three ways out for a small US seller. AsiaPresswire – A two-person store selling kitchen goods on Shopify crossed $100,000 in shipments to Texas somewhere around the middle of 2026. Nobody told them, because nobody has to. Under the economic nexus rules every sales-tax state runs since the Supreme Court’s South Dakota v. Wayfair decision in 2018, crossing the threshold by itself creates the obligation to register, collect and file there, within the window the state specifies. The store’s own home state is one filing. Its marketplace sales are collected by Amazon and Etsy. Its Shopify orders are not, and they are the ones quietly stacking up in states it has never visited. By the time a notice arrives, the exposure runs backward, and back taxes plus penalties are recoverable only through a voluntary disclosure agreement that costs money to even ask for. Why the comfortable assumptions fail The first comfortable assumption is that marketplace facilitator laws solved this. Amazon collects and remits sales tax on marketplace sales in all the states that require it. That is true, and it is close to useless as protection, because in most states marketplace sales still count toward the seller’s own threshold even though the marketplace collected the tax. A seller doing $70,000 through Shopify and $60,000 through Amazon into North Carolina has crossed that state’s $100,000 trigger, even on the $60,000 Amazon already handled (Salestaxquestions, 2026). Washington and Texas go further and count gross revenue including exempt sales toward the threshold. The collection was handled. The obligation to measure, register and file, in states where the marketplace’s remittance does not cover the seller’s direct channel, was not. The second comfortable assumption is that the thresholds are uniform. As of 2026, 45 states plus the District of Columbia enforce economic nexus, and the trigger is $100,000 in 42 jurisdictions, but the edges differ in ways that bite. California, New York and Texas sit at $500,000. New York is the only major state that requires both conditions, $500,000 and more than 100 transactions; everywhere else the transaction count, where it still exists, is an “or” trigger. A seller of $10 items in a transaction-count state like Georgia or Michigan can hit the 200-transaction trigger at $2,000 of sales (LegalClarity, 2026). Measurement windows differ too: calendar year in most states, rolling 12 months in Tennessee and Ohio, prior four quarters in Vermont. Illinois dropped its transaction threshold on January 1, 2026 and Kentucky follows in August 2026, so the map this year is not the map of last year. A spreadsheet built in 2025 is already wrong in two cells. The third assumption, that the federal government just fixed all this, confuses two different taxes. The One Big Beautiful Bill Act, signed July 4, 2025, restored the 1099-K reporting threshold to $20,000 and 200 transactions retroactive to 2022 and raised the 1099-NEC threshold from $600 to $2,000 starting in 2026 (TIN Comply, 2026). That genuinely reduces federal paperwork for millions of casual sellers. It changed income information reporting. Sales tax is a state tax, administered by 45 separate governments, and the 2025 federal law did not touch a single nexus statute. The two reforms run in opposite directions: less federal form-chasing, unchanged state collection duty. The registration ratchet and the warehouse trap Two structural quirks make the exposure stickier than a one-time mistake. First, registration is a ratchet. Once a seller registers in a state, the returns keep coming for as long as the account is open, at whatever frequency the state assigned, monthly for larger volumes, quarterly or annually for smaller ones. Deregistering requires final returns, sometimes a bond, and in practice an accountant’s time. The $39 monthly software subscription scales down; the registration footprint does not. Sellers who registered defensively in 2019, when the post-Wayfair panic was at its peak, are still filing returns in states they no longer ship to, because closing the account costs more effort than the filing. Second, the FBA trap operates on a different trigger entirely. Inventory stored in a state creates physical nexus there regardless of sales volume. A seller with $40,000 of total sales in 2026 and pallets sitting in an Amazon warehouse in Pennsylvania has obligations in Pennsylvania that no economic-nexus dashboard will surface, because the dashboard watches the dollar counter and the obligation arrived with the pallet. The nexus monitoring bundled with Avalara Select and the boutique services watches both, which is a concrete reason the monitoring matters even for sellers who consider themselves too small for any of this. Practitioner materials aimed at cross-border sellers price the multi-channel cleanup engagements that follow, per 2025-2026 practitioner surveys, at $1,500 to $3,500 per year for ongoing work, which is the quiet cost of discovering the warehouse rule late. Path one: software, and doing the filings yourself The direct path is compliance software with the seller’s name on every return. The published price list for 2026 makes this the most transparent of the three options. TaxJar’s Starter plan runs $39 per month with 2 AutoFile credits a year, extra filings at $50 to $55 each; the Professional plan is $99 per month with 4 credits, all effective October 1, 2026 (TaxJar, 2026). TaxCloud starts at $19 per month and, as of its 2026 rate card, files at $39 per return. Avalara’s small-business Select plan prices Core Compliance, as of its August 2026 announcement, at $799 per state per year with a three-state minimum, or $79 per state monthly (Avalara, 2026). Stripe Tax, for sellers already inside Stripe, is $90 per month. Table 1: Published 2026 pricing for the three compliance routes, plus the one-time costs that arrive first. Route Published cost basis Example annual cost, 5 states What the seller still does DIY software (TaxJar Professional) $99/mo, AutoFile $55 per extra filing about $1,590 with 8 paid filings monitor nexus, confirm rates, answer notices Budget software (TaxCloud) $19/mo, $39 per filing about $2,580 for 5 monthly-filer states register, reconcile, file calendars Managed filing (Avalara Select Core) $799 per state per year, 3-state minimum about $3,995 for 5 states hand over notices, review annual summary Boutique service (Sales Tax Advisors) from $600/mo up to 10 states, +$60 per extra state about $7,500 supply data, approve registrations Registrations and VDAs, one-time $300 per registration; $5,400 per VDA varies decide on voluntary disclosure before filing forward Source: TaxJar and Avalara , 2026 pricing pages; Sales Tax Advisors rate card, accessed November 2026. The arithmetic that matters sits under the table. Software does not register you; each state registration costs its own fee and takes its own paperwork, and a flat-fee service charges $300 per registration as of its published November 2026 rate card. Software does not fix the past. If the store in the opening paragraph has two years of unregistered Texas sales, the backward liability needs a voluntary disclosure agreement, priced at $5,400 per jurisdiction in 2026 by the boutique firm above, in exchange for capped lookback and waived penalties. Doing nothing is not the free option it appears to be: state penalties for unfiled returns, as compiled for 2025, typically run $50 to $250 per month plus interest of 1 to 1.5 percent per month on the unpaid balance. The cheapest year of compliance is always the first one, bought before the notice arrives. One more discount hides inside the software path. In up to 25 states, the Streamlined Sales Tax program pays the compliance provider directly for qualifying sellers, which is why Avalara sells its SST plan at $699 per state instead of $799 and why TaxCloud can be free or subsidized in SST member states for enrolled businesses. A seller whose nexus footprint overlaps the SST states can shave hundreds of dollars a year by enrolling. Almost nobody without an accountant mentions this to them. Path two: hand it to a service The delegation path prices peace of mind. Avalara Select Core, at $799 per state annually, includes calculation, filing, remittance and state correspondence, with nexus monitoring across all 50 states bundled in. The boutique end of the market is more expensive and more personal: the Sales Tax Advisors rate card, published in 2026, offers a monthly return service starting at $600 per month covering up to 10 states, $60 per additional state, with reconciliation before filing and notice handling included (Sales Tax Advisors, 2026). A full 50-state nexus risk analysis, the audit that tells you where you already went wrong, runs $3,900 flat as of the same card. What the premium buys is error absorption. When a filing is wrong in the DIY model, the state notices the seller, and the seller navigates the correction. In the managed model, the provider absorbs the notice, files the amended return and re-remits. For a seller with employees, inventory in multiple states through Fulfillment by Amazon, or a product line whose taxability differs state by state, that difference is worth more than the fee spread. For a seller with one warehouse and two channels, it is paying for calm. The moment physical nexus exists, because inventory sits in a state’s warehouse, the economic-nexus software discussion is too narrow, and the managed model earns its premium faster. The cost that never appears in the brochure is the onboarding gap. Moving to a managed service mid-exposure means either cleaning up the past first, through those $5,400 VDAs, or disclosing it during registration and negotiating. Filing forward while the back period sits open tells the state exactly where to look, as the boutique firms warn their own clients. The managed path is therefore a clean-break strategy: expensive to enter, cheapest if entered before the mess rather than after. Path three: shrink the map The third path is commercial, not administrative: stay out of the states that trigger obligations. A seller can geofence shipping to exclude states where the threshold looms, or concentrate advertising spend in states already past the point where one more dollar matters. The cost is measurable in market size. California, Texas and New York, the three $500,000-threshold states, are also the three most populous states in the country; excluding them removes roughly a quarter of US consumers from the addressable market. Excluding a $100,000-threshold state that the seller is approaching costs proportionally less but still real revenue, and the exclusion must be maintained: one ignored campaign setting and the threshold is crossed anyway, with the obligation created on the day of the crossing. The variant that mostly works is thinner than it sounds. Thresholds count sales, not presence, and most states measure gross sales including wholesale and exempt transactions. What a small seller can do legitimately is watch the counter the way the states do, monthly, by state, using the nexus monitoring that even the $19 software includes. The decision to withdraw from a state, keep collecting nowhere, and revisit at the next price increase is a legitimate quarterly business decision. What does not work is discovering the counter in a letter. The states do not forgive the crossing because the seller was busy; they sell the forgiveness back at VDA prices. There is also a time price on the DIY path that no vendor’s pricing page prints. Five states with mixed filing frequencies ran, in a typical 2026 setup, on the order of a dozen to twenty returns a year, each needing reconciliation between the platform payout, the processor fees and the state’s own definition of taxable sales. At thirty to sixty minutes per return for a person who does this monthly, the software path costs roughly a working week per year of someone’s attention, at 2026 filing volumes, plus the notice replies that arrive on their own calendar. The $99 subscription buys the rate tables and the automation. It does not buy back the week. Sellers who price their own time honestly often find the managed path is cheaper than it looks, and sellers who do not are the ones the boutique firms find later, holding a penalty letter and a story about why they thought marketplace collection covered everything. Which route, for whom Start with the software path if the footprint is genuinely small: one state of physical presence, marketplace-heavy sales, direct-channel volume below $250,000, and no FBA inventory outside the home state. That is the $1,500 to $2,600 per year scenario, and the seller’s main job is a monthly ten-minute review of the nexus dashboard. Move to the managed path when any of three things is true: inventory sits in more than one state, the direct channel has crossed two or more state thresholds, or the seller’s time is worth more than the roughly $4,000 to $7,500 annual spread between software and service. Take the $3,900 nexus analysis before either, if there is any chance of past exposure, because the answer changes which path is safe. And if a state has already sent a letter, stop shopping for software and call about a voluntary disclosure the same week. Every month of delay is $50 to $250 in penalties plus interest, compounding in the state’s favor. The store in the opening paragraph, the one that crossed $100,000 in Texas, should do exactly one thing today: run a nexus report across all 50 states, free with any of the monitoring tools mentioned above, and read the Texas line first. The obligation started on a date they can pinpoint from their own sales ledger. The state already knows the address. Everything else in this article is sequencing. The report tells them whether the sequence starts with a registration and a $39 subscription, or a phone call and a $5,400 disclosure, and those two first steps differ by a factor of a hundred. Twenty minutes with the free report is the highest-return compliance work a small seller will do this year. Data basis Data as of November 2026. Nexus thresholds and trigger logic (42 jurisdictions at $100,000, three at $500,000, New York’s and-logic, Illinois and Kentucky threshold changes in 2026) come from state-by-state tracking cross-referenced with state departments of revenue, reviewed August 2026. The marketplace-threshold rule (marketplace sales counting toward the seller’s trigger) is documented for Washington and Texas explicitly and described as the majority rule in practitioner guidance. Published prices for TaxJar, TaxCloud, Avalara Select, Stripe Tax and the Sales Tax Advisors rate card are quoted from the vendors’ own 2026 pricing pages, effective October 1, 2026 for TaxJar. The 1099-K and 1099-NEC changes come from coverage of Public Law 119-21 signed July 4, 2025, with IRS guidance. Penalty ranges ($50 to $250 per month plus 1 to 1.5 percent monthly interest) come from NCSL-published state penalty compilations as summarized in 2025 to 2026 practitioner materials. The five-state example costs are computed from the published rate cards and are illustrations, not quotes. Limitations: several vendors quote custom pricing behind sales calls, so the managed-service comparison understates the true spread; SST subsidy eligibility depends on seller registration status and cannot be confirmed in the abstract; and state penalty schedules vary, so the range is a span, not a median. Sources Nexus Snapshot , economic nexus thresholds by state, data version 2026-Q3, reviewed August 26, 2026 TaxJar , Starter and Professional pricing, effective October 1, 2026 Avalara , Avalara Select pricing for small business, August 2026 Sales Tax Advisors , published rate card for filings, registrations and VDAs, accessed November 2026 TIN Comply , 1099-K threshold restored to $20,000 and 200 transactions under OBBBA, updated October 28, 2026 LegalClarity , state threshold chart and Wayfair background, 2026 This article was prepared by the expert team at Global Infinity Labs, drawing on insights and data provided through its MCP data services. About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. Email: support@globalinfinitylabs.com
More
UK Opens Consultation on Licences for Shared E-Bike Schemes SeaPRwire

UK Opens Consultation on Licences for Shared E-Bike Schemes

SeaPRwire – The Department for Transport opened a consultation on 5 November on licensing shared e-bike schemes in England, with proposed national standards and new powers for councils to license operators in their areas. It closes on 31 December 2026. The standards are built from five documents an operator would have to file: a parking plan, a plan for antisocial and illegal behaviour, a fleet management plan with defined fleet sizes and operating areas, a fleet maintenance plan, and possibly an insurance requirement. Of those, the parking plan is the one aimed at the complaint that started all this. Dockless bikes get left across pavements, and the answer the department has chosen is not racks or geofencing but a document each operator writes for each area and a council that can refuse a licence without it. The behaviour plan is broader than parking. It covers riding drunk, riding underage and riding on pavements, and it commits to “clear consequences such as fines”. The consultation does not say who issues those fines, at what level, or whether a council, an operator or the police does the enforcing. Insurance sits further back. The release describes it as a “potential” requirement, which puts it in the same category as the fees and data-sharing powers the department is still consulting on rather than proposing. Fleet size is the clause with the most reach. A defined fleet size and operating area, set through a licence, is the mechanism by which a council can cap the number of bikes in a borough. Operators have built their pitch to cities on density, and a cap is the thing that changes their unit economics most directly. Fees would add a second lever. The department is still consulting on whether councils should be able to charge operators, which would make a licence a revenue arrangement as well as a standards document. The release does not say what a fee would be based on, whether it would be per bike, per trip or flat. Neither the cap nor the fee has a number attached to it. The geography is narrower than the headlines. The powers are for local leaders in England, and Scotland, Wales and Northern Ireland are not covered by the proposal. Within England, London gets a different route: the department is working with the Mayor and Transport for London on devolving the powers to TfL, so that one body enforces across the capital instead of 32 boroughs. That London arrangement is the tell. The stated aim is to end both a patchwork of operator rules and the “postcode lottery” of standards enforced differently in each borough, and the way to do that in London is to remove the boroughs from the decision. Elsewhere the proposal creates the patchwork it says it wants to remove. Every licensing authority in England writes its own conditions, sets its own fleet caps and decides its own fees, and an operator running in twenty towns deals with twenty sets of rules. National standards narrow the range of what a council can ask for. They do not produce one licence. Operators have asked for this. Lime, Voi, Beryl, Dott, Forest and Bolt all run in the UK, and the release says the sector has been calling for regulation to end the “patchwork of rules for operating in different areas”. Their interest is predictability: a licence with known conditions is easier to price than a council that can act without one. The numbers they brought to the consultation are the ones that support that case. Bolt says 98% of its rides already end with a correctly parked bike. Forest puts London’s shared e-bike trips at around 350,000 a day. None of the operators that commented put a figure on what a fleet cap would cost them, and the department has not published one either. The accessibility case is the one the department leads with, and it has the hardest number in the release. RNIB says 92% of blind and partially sighted people report having had to walk into the road because of street obstacles such as e-bikes. Guide Dogs makes the same point about pavement blocking. Both organisations welcomed the consultation and both warned, in almost the same words, that local flexibility could reproduce the inconsistency the standards are meant to fix. The 92% figure is the charity’s own survey data, and the release gives neither the sample nor the year. Chris Boardman, the National Active Travel Commissioner, put the counterweight: shared bike use is growing, journey times are predictable, and the schemes give people an option when other transport fails. The department’s own spending plans point the same way, with £4.5 billion committed over five years for active travel, including £104 million recently for cycling routes across the UK’s 12,000 miles, against a target of more than half of short journeys in towns and cities being walked or cycled. The two charities made the same request in different words: write the national standards tightly enough that a council cannot read them loosely. That is a drafting problem rather than a policy one, and it will decide whether the regime looks uniform across England or only on the department’s website. The two goals pull in different directions, and the consultation does not resolve them. Clearing pavements means fewer bikes in the places where they are most useful; a fleet cap is the fastest way to clear a pavement and the fastest way to make a scheme unprofitable. What happens next is legislative, and the release does not say what vehicle carries it. A licensing regime needs powers that councils do not currently hold, and the timeline beyond 31 December 2026 is unstated. Operators will keep running under the existing voluntary arrangements until a commencement order appears. The consultation asks the questions a licensing scheme needs answered, and leaves the two that decide whether it works: how many authorities actually write a licence, and what a fleet cap does to the trips the active travel targets depend on.
More
Minnesota Justices Weigh Whether a One-Star Review Is Public Speech SeaPRwire

Minnesota Justices Weigh Whether a One-Star Review Is Public Speech

SeaPRwire – Minnesota Supreme Court justices heard oral argument on Thursday in a defamation case that turns on whether a one-star Google review is speech about a matter of public concern, and therefore covered by the state’s anti-SLAPP statute. The review was posted by the owner of Robinet Productions, a video production company, after Paragon Restorations refused to pay for promotional video work. It gave the contractor one star and told other businesses to avoid it. Paragon sued for defamation, arguing the review was false because Robinet had not met its side of the contract. Robinet moved to dismiss under the Uniform Public Expression Protection Act, Minnesota’s anti-SLAPP law, which is designed to end suits brought to silence critics rather than to win. That statute is what makes the case worth arguing over. A granted anti-SLAPP motion carries a fast timetable and shifts the plaintiff’s opponent’s legal costs onto the plaintiff. A denied one leaves the defendant paying to defend a review that may be one paragraph long. The procedural history is unusual. The district court dismissed Paragon’s defamation claim on the merits, finding that the core assertion, that Robinet was not paid, was technically true. It did so without reaching the anti-SLAPP question, which meant Robinet could not recover fees. The Court of Appeals then held that the review was a personal grievance over a private transaction and not a matter of public concern, which is the category the act protects. Robinet appealed that holding, and Thursday’s argument was about the category rather than the truth of the post. Minnesota applies a constitutional test that looks at a statement’s content, form and context to decide whether it addresses a matter of public concern, and the lower courts use it as a gate. Vince Reuter, representing Robinet, told the justices that the gate was built for high-stakes defamation and now catches ordinary consumer reviews. “The purpose of this law is to expand and broaden free speech,” Reuter said. He described the review as an express warning to others, based on one owner’s experience of work he says was never paid for. Samuel Johnson, for Paragon, argued the opposite: reading all business reviews as public concern would drop the context inquiry the statute depends on and would move a constitutional question into a category the legislature cannot create. “If the legislature did what appellants say it would do, by making all ratings and reviews of businesses occupy that highest rung of First Amendment protection, that would invade the role of this court to decide what constitutional protections exist,” Johnson said. On his account the post expressed anger about an unpaid invoice and nothing more, and he noted that no one appears to have responded to it. Justice Anne McKeig put the difficulty to him directly. “It seems the secondary purpose was to actually warn others,” she said. Johnson’s answer, that a warning nobody read has no social or political impact, drew the sharpest question of the morning. “Should we be a little bit worried that we’re creating or adopting a test that sort of privileges popular statements and disadvantages unpopular statements?” Justice Karl Procaccini asked. A reach test measures how many people noticed a post, not whether the subject is one the public has an interest in. Justice Paul Thissen offered the narrow reading. Plenty of people are hurt by defamation suits, he said, and that does not by itself require broader protection. His estimate was that perhaps 2% of business reviews fall inside the anti-SLAPP statute, and he suggested that figure might be what the legislature intended. Two per cent is the number to hold on to. If Thissen is right, the choice before the court is not between protecting all reviews and protecting none: it is whether the small share that attracts a defamation suit gets the fast exit the statute offers, or the ordinary litigation timetable. A fee-shifting statute works on behaviour before any judge rules. A company that expects to pay the other side’s lawyers if its claim is dismissed thinks harder about filing, and that effect does not depend on how many reviews the statute formally covers. The tension is not easy to draft around. A narrow reading keeps the law where it started, protecting speech about how institutions behave, and leaves two companies arguing over an invoice to the ordinary rules, which is where most commercial disputes belong. A broad reading protects the small operator who cannot afford a lawyer, which is the reason the statute exists, and it also hands every disappointed customer a fast exit from a claim that may well be justified. Neither reading is obviously wrong, and the court has to pick one a district judge can apply without knowing the parties’ budgets. The court has extended the public-concern category before. It ruled in an earlier case that a #MeToo account by a dance instructor was a matter of public concern, which is the precedent Robinet’s side leans on when it argues that a warning to future customers belongs in the same box. Paragon’s answer is that the two are not alike. A dance instructor’s account of conduct towards students describes something a stranger might need to know before signing up; a dispute over an unpaid invoice is between two companies that signed a contract. Both descriptions fit the post, which is why the argument ran for as long as it did. The review states a fact, that payment was withheld, and an opinion, that others should stay away. The first is either true or false and was already resolved. The second is the part the court has to classify. Whatever the court writes will become a rule for the next thousand posts. The workable version asks whether the review describes a practice a stranger could act on, which is a different question from whether the poster was angry and a different question again from whether anyone read it. Reuter’s closing formulation was about symmetry: a business takes the benefit of five-star reviews and should bear a one-star review based on true facts and an honest opinion without dragging the reviewer into litigation. Johnson’s was about line-drawing: someone has to decide what counts as public, and it is the court. A ruling for Robinet would give consumer complaints and warnings about business practices a clearer route to early dismissal and fee shifting. A ruling for Paragon would leave those posts to the ordinary defamation timetable, where the cost of defending is itself the pressure. The court did not indicate when it will rule.
More
Axiom Math Puts 7,654 Pages of Mathematics Through a Machine Checker SeaPRwire

Axiom Math Puts 7,654 Pages of Mathematics Through a Machine Checker

SeaPRwire – Axiom Math said on Wednesday that it had formally verified the Stacks Project, a reference work of roughly 7,654 pages spanning algebra, geometry and number theory, and turned it into about 16 million lines of code that a proof assistant checks line by line. Formal verification means rewriting a proof in Lean and having a program test every step. If the code compiles and the checker accepts it, the proof is sound in the narrow sense that it follows from its axioms. Whether it is the theorem a reader of page 4,000 had in mind is a separate question, and one the announcement does not address. The concern behind the work is not hypothetical. Last month OpenAI published 719 manuscripts claiming results on hard problems, and the automated checks used to confirm that kind of output can fail, according to an arXiv paper on the subject. Stacks is an unusual thing to verify. Johan de Jong, a Columbia mathematician, started it in 2005 as an open source reference, and contributions have accumulated since, from first-year algebra to results at the edge of current research. Peter Woit, also at Columbia, has compared it to the Bourbaki volumes that rebuilt the field’s foundations in the twentieth century. The work was done by a fleet of Axiom’s agents running in parallel. Ashvin Swaminathan, who works on the technical staff, said the team imposed a hierarchy without dictating what each agent did: “The agents were finding tasks for themselves and identified things that they could work on in parallel.” Keeping 16 million lines consistent is harder than writing them. Every theorem in Stacks rests on earlier theorems and definitions, so a translation that gets one dependency wrong can produce a structure that compiles and still does not match the source. Carina Hong, the chief executive, described the difficulty in terms of scale and fragility rather than error: “Things that are big and things that are delicate in life just don’t go together.” The ratio is worth a look. Sixteen million lines against 7,654 pages works out to roughly 2,000 lines of Lean for every page of prose. A formal proof spells out steps a human reader supplies silently, so a large multiple is expected. It also means the surface a reviewer has to check is two thousand times the text it mirrors. Axiom trained its own models for the job and started by having an in-house Lean expert teach the agents judgment about which formalization was worth writing. Hong said the agents have since developed that judgment on their own. That claim is the part of the project an outside reader cannot check from the announcement. Hong framed the alternative approach as licensing models and building tooling on top of libraries that already exist, which she said is what most verification startups do. Training in house, on her account, is what let the agents work at this scale. A customer cannot test that claim before buying. The gap the work fills is specific. Swaminathan called algebraic geometry “this huge black hole” in formalized mathematics, which meant researchers who wanted to machine-check a new result in the field had little to build on. Those researchers now have a library to import. Using it is a different skill from building it. Anyone who imports Stacks inherits every definition it carries, including the conventions Axiom’s agents settled on where the source text left one open. Those choices sit at the top of a formalization and are the first thing a specialist reads. None of that shows up in a page count. Axiom’s argument for why that matters is cumulative. Each verified result becomes something a later proof can cite instead of rederiving, and Terence Tao, the UCLA mathematician, has put the effect plainly: “The more formalized proofs you have, the more formalized proofs you can make.” The company is valued at $1.6 billion and raised a $200 million Series A in March led by Menlo Ventures. Hong, 25, left a Stanford mathematics PhD to start it in March 2025. Its commercial case rests on the same mechanism applied to software. Developers have never been able to guarantee that code is free of defects, and the problem grows as agents write more of it. A verified library is a way to check an agent’s output against something other than another model’s opinion. For a coding agent, that changes what a check is. The usual test of generated code today is another model reading it, or a suite of tests a person wrote in advance. Formal verification offers a third option: the agent’s output is turned into a formal statement and tested against definitions that were themselves tested. Stacks is not the only possible target, only the largest one so far. The Stacks work says something about the method as well as the result. Axiom’s agents chose their own tasks inside a loose hierarchy, which is closer to how the company expects agent labour to be organised than a pipeline of assigned steps. Hong’s reason for caring is that early structural mistakes are expensive to undo: “If you slop drop in a way that’s bad engineering choices in the beginning, then it’s very hard for them to grow that boundary.” What the announcement does not include is independent confirmation. Formal verification is checkable by anyone with the code and a proof assistant, which is the point of it, and that check has not yet been published by a third party. Nor has Axiom said how many mathematicians reviewed the translation against the source text rather than against the compiler. The company has been direct about wanting the field to follow. Hong’s closing line was a challenge to the coding companies to formalize at the same scale, which is a claim about where the bottleneck sits: not in the checking, but in the willingness to pay for it. Until someone outside Axiom imports the library and builds a new proof on top of it, the Stacks formalization is a demonstration that the translation can be done. It is not yet evidence about what the translation is good for.
More
Zipline Raises $1.5 Billion to Turn 21 Drone Sites Into 300 SeaPRwire

Zipline Raises $1.5 Billion to Turn 21 Drone Sites Into 300

SeaPRwire – Zipline closed a $1.5 billion round at a $21.5 billion valuation and signed a multi-year agreement with Walmart to open 300 drone delivery sites across the United States. The two companies run 21 sites today. Paradigm, WCM Investment Management and Layer Global led the round. Valor Equity Partners, Fidelity Management & Research, Uber, Tiger Global, J.P. Morgan, ARK Invest and Salesforce Ventures also put money in. Zipline says the proceeds go to its U.S. manufacturing facilities and to hiring for a national delivery network. Where those 300 sites will sit, when they open, and how the cost splits between Zipline and Walmart are all undisclosed. So is the state-by-state count, which matters because the home delivery product is built around a fixed radius. So is whether Walmart pays per delivery or per site. Zipline started in 2014 delivering blood in Rwanda, then Ghana and Nigeria. Blood is an unforgiving first cargo: it has a shelf life, a hospital needs it to a schedule, and the order arrives by phone long before a road does. The company has been running that schedule in African countries for a decade, and now moves food, retail goods, agricultural inputs and health products in five of them. It reached the United States in 2020 with medical supplies for Novant Health in North Carolina, and signed its first Walmart agreement a year later. Hospital logistics and retail delivery look similar on a map and differ in almost everything else. A hospital orders in cases to a schedule; a household orders one item on impulse. The second pattern is what a 300-site network has to absorb. The 2022 Part 135 air carrier certificate from the Federal Aviation Administration is the piece that changed the shape of the business. Certification let Zipline fly long-range commercial routes in its own right, instead of assembling case-by-case exemptions for every new corridor. Two aircraft do the work, and they are not the same business. Platform 2 carries up to eight pounds within a 10-mile radius, which describes a consumer drop: a pharmacy order, a takeaway meal, a small retail item. Platform 1 covers 120 miles round trip for enterprise, business and government customers, where payload matters less than distance and scheduling. The two platforms also want different things on the ground. Platform 1 needs a long corridor and a customer with demand on a schedule, which is why its first U.S. work was hospital supplies. Platform 2 needs a dense cluster of addresses inside ten miles, which is a map of suburbs and second-tier cities rather than a map of hospital campuses. Revenue from the short-radius product is where volume sits; the long-range product is where contracts sit. Zipline’s disclosure on Thursday touched the mix directly: its share of delivery revenue rose from 10.8% to 34.9% between March and October. Read that number carefully. Zipline did not publish the revenue base it is a share of, did not say whether the denominator is its own delivery income or the total value of goods moved, and did not break the figure out by country. A share rising nearly threefold in eight months is consistent with a network filling capacity it has already built. It is equally consistent with a small base growing fast. The company has not supplied the numbers that separate the two. Zipline builds the aircraft, the launch and landing systems and the logistics software itself, which is why the money is going into a factory. Scaling to 300 sites means scaling three production problems at once: airframes, the ground installations they launch from, and the software that assigns orders to aircraft. An operator that buys aircraft off the shelf faces only the last of the three. Building 300 sites is a construction and permitting exercise before it is a flying one. Each site needs a launch and landing installation, a power supply, staff to load aircraft and hand over packages, and a set of local approvals Zipline has not described. Every site is also a fixed cost that only pays back on utilisation. One aircraft parked at a site that takes twelve orders a day earns a different return than the same aircraft taking sixty, and Zipline has published no orders-per-site figure for the 21 locations it runs now. That number, not the size of the round, is what decides whether 300 sites is a network or 300 depreciating installations. The African network it built first was designed around distance and scarcity, where a single hub reaches clinics spread over hundreds of miles and the alternative is a motorbike on a bad road. The American network it is now building is designed around density, where a hub serves addresses minutes apart and the alternative is a car. The aircraft come from the same company, but the operating problem, the site design and the customer are not the same ones. Airspace is the constraint that does not scale with capital. A Part 135 certificate covers the operator, not the corridor. Dense urban airspace, noise complaints and the politics of a drone hub landing in a residential area are decided locally, one site at a time, and none of it is settled by a $1.5 billion round. The 21 sites in service are the evidence Zipline has for all of this, and a small sample: 21 sites is a demonstration network that can be tuned by hand, and 300 is one that has to run on procedures. What $21.5 billion buys is a bet on that transition. Zipline’s disclosed operating metric is a revenue share, not revenue, and its disclosed customer commitments are agreements, not volumes. Neither tells an outsider how many deliveries the network completes in a week. Walmart’s side is easier to read. The retailer has been testing drone delivery since 2021 and has now committed to a footprint fourteen times larger than the one in service, which says what it expects the unit economics to look like at scale and nothing about what they are today. Zipline has not said when the three hundredth site opens.
More
The Four Rails That Move Japan’s Money SeaPRwire

The Four Rails That Move Japan’s Money

A working comparison of Zengin, BOJ-NET FTS, FXYCS and JCB on volume, ticket size and cost, using May 2026 and FY2025 data SeaPRwire – At the end of the month, a billing clerk at a mid-size trading company in Tokyo releases three payments before lunch. The supplier invoice for 5 million JPY goes out through the bank’s online portal. The payroll file for 40 staff is uploaded to the same portal, but it lands in a different queue with a different deadline. The weekend’s card takings, which the company has not touched yet, are already being reconciled somewhere between an acquirer and a card scheme. Nothing in this morning is exotic. All three payments clear inside Japan, in yen, within a day. What differs is which rail each one rides, and the four rails underneath Japanese money behave nothing like each other. Start with the tasks, not the tools Tool comparisons fall apart when they start from spec sheets. A transfer system looks good on speed until you learn its cut-off time, and a card scheme looks cheap until you read the merchant contract. So the comparison here runs the other way: four ordinary jobs that Japanese businesses do every day, then a look at which rail takes each job and what that rail does to it. The four tasks: Pay one supplier invoice of 5 million JPY the same day. Run monthly payroll for 40 staff out of one file. Take a 10,000 JPY card payment at the counter and get the money into the company account. Settle the yen leg of a large foreign exchange trade on the day it trades. Each task has a natural owner. The two transfer jobs belong to the Zengin System, the retail clearing network operated by Zengin-Net under the Japanese Bankers Association. The card job belongs to a card scheme, and JCB is the one worth studying because it is the domestic one, carrying 29 percent of the domestic scheme market against Visa’s 41 percent in 2024 (JCB Corporate Profile 2025-2026, March 2026). The FX job belongs to FXYCS, the foreign exchange yen settlement system, which settles the yen legs and finalises the funding over the Bank of Japan’s own network, BOJ-NET Funds Transfer System (FTS). Table 1: Which rail owns which everyday task Task Rail that owns it What decides the outcome Supplier payment of 5 million JPY, same day Zengin System, small-value stream Your bank’s cut-off time and fee tier Payroll for 40 staff from one file Zengin System, bulk total-count format File format test and total verification Counter card payment of 10,000 JPY JCB scheme; merchant settlement next day over bank rails Merchant discount rate Yen leg of an FX trade, settled same day FXYCS, funded over BOJ-NET FTS Same-day yen liquidity Source: Bank of Japan , monthly payment statistics coverage, May 2026 (site home) Run one: the supplier invoice rides Zengin Start with the task that happens most. The Zengin System processed 9.495 million transactions on an average day in May 2026, worth 20.78 trillion JPY (Bank of Japan, May 2026). Year on year, that is a 13.4 percent rise in transaction count and a 24.5 percent rise in value against May 2025, which tells you the network is handling both more payments and larger ones. The average ticket across the whole system was 2.188 million JPY in May 2026, but the average misleads, because Zengin is really two networks wearing one name. The small-value stream, the one your 5 million JPY invoice actually rides, carried 9.472 million transfers a day at an average of 536,000 JPY (Bank of Japan, May 2026). The large-value stream moved only 14,847 transfers a day but concentrated 16.1 trillion JPY in May 2026, an average of over 1 billion JPY per transfer, and it grew 26.9 percent in value against May 2025. Same infrastructure, same day, opposite jobs. A monthly perspective makes the small stream’s scale concrete: in December 2024 alone, Zengin handled 154.8 million telegraphic transfers worth 337.5 trillion JPY (Zengin-Net Statistical Data, June 2025). What does the run feel like from the clerk’s chair? The mechanics are simple, but three details decide whether the invoice arrives today: Cut-off time. Zengin clears in scheduled cycles through the business day. A payment entered before your bank’s same-day cut-off settles that day; one entered after it settles the next business morning. Banks publish their own cut-offs and they differ. Fee tier. Pricing sits in your bank contract, not in the network. Japanese banks charge per transfer, with tiers that commonly key on whether the instruction was entered online or at a counter. The network does not set your price. Beneficiary name matching. Japanese bank transfers check the registered account name against the one you supply. A mismatch bounces the payment, and the recall costs land on the sender. The step people skip is the name check. Companies inherit account details from old contracts, a single character drifts in a legal name after a merger, and the 5 million JPY invoice comes back the next afternoon with a recall fee attached. Build the beneficiary registry once, verify it annually, and the same-day task becomes boring in the good sense. One calibration note before moving on. The 20.78 trillion JPY figure is Zengin’s own published processing total. The Bank of Japan’s current-account statistics slice the same flows differently, and the bank’s settlement detail shows a much smaller Zengin component inside BOJ-NET. Both numbers are official. They sit on different statistical layers, and this comparison quotes the Zengin layer throughout, without adding the two together. Run two: the card payment clears JCB, then the banks Now the counter payment. A customer taps a card for 10,000 JPY, and the moment feels instant. The money is not. What happens next runs on a completely different rail, and the costs attach at a different point in the chain. JCB is the rail to study first because it is the domestic scheme and because its numbers are public. In FY2025, the year from April 2025 to March 2026, the JCB network carried 53.4 trillion JPY in transaction volume (JCB Corporate Profile 2025-2026, March 2026). The scheme counted 181.9 million cardholders as of March 2026 and roughly 72 million accepting merchants worldwide on the same date. For scale against the other rails in this comparison, note the corporate base line: JCB’s net revenue in FY2024 was 432.6 billion JPY with operating profit of 41.2 billion JPY (JCB Corporate Profile, March 2026). A card scheme is a private business, not a utility, and those two lines are what the four-rail comparison is really pricing. The cost of the counter task sits in the merchant discount rate, the slice the acquirer and scheme take from each sale. Domestic card acceptance in Japan runs at roughly 3 percent for merchants (JCB Corporate Profile 2025-2026, March 2026). The QR wallet competition prices below that: PayPay and comparable wallets charge in the range of 1.60 to 1.98 percent according to the same source, which is exactly the pressure the entry describes, merchant transaction volumes must justify the domestic rail’s fee. Run the arithmetic on a shop doing 1 million JPY of card sales a month on the March 2026 fee schedules: the gap between 3 percent and 1.98 percent is 10,200 JPY a month, 122,400 JPY a year, for the same 10,000 JPY tap at the counter. Where does the money actually travel? Card scheme flows settle between banks through the ordinary deposit system, not through a dedicated card rail. The acquirer credits the merchant, typically next business day, and the interbank leg of all those accumulated settlements rides the same bank transfer infrastructure as everything else. This is the design point people miss about the four-rail picture: the card networks in Japan do not own a settlement layer. They own an acceptance and messaging layer, and they rent the settlement layer from the banks. That renting is what the 3 percent buys, and it is also why wallet schemes with their own cheaper routing have been able to undercut on price. The step people skip here is reading the settlement calendar, not the fee schedule. A 3 percent rate settled in two days can cost a thin-margin business more than a 2 percent rate settled next morning, because the discount rate is only half of the price. The other half is when the money arrives. Ask the acquirer for both numbers in writing before signing anything. Run three: the treasury payment rides BOJ-NET The third task is the one most readers never touch, and it is the biggest. When a bank needs to deliver the yen leg of a foreign exchange trade, or a securities house needs to fund a bond purchase, the final movement happens over the BOJ-NET Funds Transfer System, the central bank’s real-time gross settlement network. There is no credit risk between participants here, because the money is central bank money, and settlement is final the moment it hits. The scale difference against Zengin is the whole story in two numbers. On an average day in May 2026, BOJ-NET current-account settlement processed 100,790 payments worth 251.5 trillion JPY (Bank of Japan, May 2026). Read that against Zengin’s 9.495 million payments and 20.78 trillion JPY, both May 2026 averages. BOJ-NET handles about one hundredth of the transaction count and about twelve times the value. The average ticket across the two networks differs by more than three orders of magnitude, roughly 2.49 billion JPY against 2.188 million JPY in May 2026. These are not two versions of the same service. They are two different layers of the money system, one moving value between institutions, one moving it between account holders. Participation tells you how closed each world is. BOJ-NET had 489 participating institutions at the end of May 2026 (Bank of Japan, May 2026). The current-account layer, the one holding the actual settlement balances, covered 460 institutions at the end of May 2026, while the foreign exchange yen settlement function covered 27. Your company does not join this network. Your bank does, and what you buy from your bank is access to it. For the FX task specifically, the yen leg settles through FXYCS, which netted 38,746 transactions a day worth 28.9 trillion JPY in May 2026, an average of 750 million JPY per trade (Bank of Japan, May 2026). The design logic is offsetting. Thousands of FX deals net down into far fewer yen movements, and the residual funding crosses BOJ-NET. In FY2024 the system handled 8.439 million transactions worth 6,042.8 trillion JPY across the year (Zenginkyo PFMI Disclosure, July 2025), which makes FXYCS the largest of the three settlement layers by value on an annual basis. An offsetting layer only works, though, if the underlying RTGS system can absorb the residuals on demand, and BOJ-NET’s real-time design does exactly that. The Bank of Japan’s own PFMI disclosure records settlement latency for same-day RTGS settlement at 0 seconds (BOJ PFMI Disclosure, July 2025). Finality is the product. The timing discipline around this rail is visible in the bond settlement data from the same monthly release. JGB book-entry transfers averaged 39,141 a day in May 2026, of which 32,032 were delivery-versus-payment legs, worth 162.5 trillion JPY in total (Bank of Japan, May 2026). The settlement progress curve shows 73.0 percent of the day’s transfers completed by 10 a.m. and 100.0 percent by 2 p.m. in the May 2026 data. Japanese wholesale settlement is front-loaded into the morning by design, so a treasury team that misses the morning liquidity window has missed the day. Line the runs up Put the three runs side by side and the differences stop being abstract. One average day in May 2026, by segment, all from the same monthly release: Table 2: What one average day looked like on Japan’s settlement rails, May 2026 Rail and segment Transactions per day (May 2026) Value per day (JPY, May 2026) BOJ-NET current-account settlement 100,790 251.5 trillion FXYCS foreign exchange yen settlement 38,746 28.9 trillion Zengin large-value transfers 14,847 16.1 trillion Zengin small-value transfers 9.472 million 5.079 trillion JGB book-entry transfers 39,141 162.5 trillion Bill clearing houses 39,000 240.5 billion Source: Bank of Japan via jp-reports , monthly payment statistics for May 2026, published July 2026 The count-to-value inversion repeats at every layer. The rail with the most transactions moves the least money per payment, and the rail with the fewest payments moves the most value per payment. Zengin’s small-value stream ran 9.472 million payments a day at 536,000 JPY each in May 2026; BOJ-NET ran 100,790 at 2.49 billion JPY each the same month. Neither is better. Each is priced and designed for the ticket size it owns. The tradeoffs behind the differences The four rails differ because they made opposite bets on the same two problems: when is a payment final, and whose money sits idle while you wait. Zengin’s bet is netting. Payments accumulate and offset through scheduled clearing cycles, so participating banks need only a fraction of the day’s gross value in liquid funds. The cost of that efficiency is time structure: cut-offs, cycles, and a settlement that is not final until the cycle closes. For a 536,000 JPY average ticket, the trade is obviously right. Nobody needs instantaneous finality on a supplier invoice; they need it cheap and same-day, which netting delivers. BOJ-NET’s bet is the opposite. Every payment settles individually, in central bank money, the moment it is entered, with the 0 second latency the disclosure records. The price of that finality is liquidity: banks must hold real balances to pay in real time, and the monthly release shows the average intraday peak balance on BOJ current accounts at 17.7 trillion JPY in May 2026, up 26.6 percent year on year (Bank of Japan, May 2026). That 17.7 trillion JPY is the standing cost of immediate finality, and it is why no rational system designs retail payments this way. FXYCS exists because of a third option: reduce what must move. By netting thousands of FX positions into a residual, it keeps 28.9 trillion JPY a day of economic activity from ever touching the RTGS system gross. The recent infrastructure history matters here too. BOJ-NET completed its migration to the latest ISO 20022 message standard in November 2025, and FXYCS migrated on the same schedule (SWIFT, November 2025). Message standard upgrades sound like plumbing, but they decide how much payment data travels with the money, and both of Japan’s wholesale rails now speak the international format. JCB’s bet is different in kind, because it is not a settlement rail at all. It is an acceptance network, spending fee income to enroll merchants and issue cards. The numbers describe the bargain: 72 million merchants accept it, 181.9 million people hold it, and merchants pay around 3 percent for the package. The competitive pressure in the data is the QR wallets at 1.60 to 1.98 percent, which do run their own cheap routing and lean on the banks only for the final leg. The domestic scheme’s 29 percent share against Visa’s 41 percent is the market’s current verdict on that bargain (JCB Corporate Profile 2025-2026, March 2026). Which rail for which job The comparison collapses into four working recommendations, each with its cost and its precondition attached. For supplier payments, use the small-value Zengin stream and stop worrying about it. The cost is your bank’s per-transfer fee, negotiated, and the precondition is a verified beneficiary name on file. Same-day arrival is guaranteed only before your bank’s cut-off, so find the cut-off and put it in the payment procedure document. The step people skip is cutting off internal payment requests two hours before the bank’s cut-off, which costs nothing and converts next-morning arrivals into same-day ones. For payroll, use the bulk file format, not individual transfers. The cost is a one-time file format test with your bank and a person who owns the template. The failure mode is specific and total: a count mismatch between the header record and the detail records rejects the entire file, so verify totals before upload, not after. Companies that pay 40 staff as 40 separate instructions pay 40 fees and get 40 chances for a wrong account number. For card acceptance, price both halves of the deal. The discount rate is the visible half, roughly 3 percent for cards against 1.60 to 1.98 percent for QR wallets on a 10,000 JPY tap, on the schedules published in March 2026. The settlement calendar is the invisible half. Get the acquirer’s settlement schedule in writing, model a thin month with slow settlement, and only then compare. The precondition for the QR comparison is terminal and POS support at your point of sale; without it the cheaper rate is unavailable no matter what the contract says. For treasury and FX, the work is upstream of the rail. Same-day settlement over BOJ-NET requires your bank to have liquidity positioned that morning, and the settlement curve shows the day is effectively over by 2 p.m. The precondition is a funding calendar aligned to the morning window, agreed with your bank before the trade date, not after the first failed settlement. One action closes this out. Pull last month’s outgoing transfer list from your bank portal tonight and count how many payments were value-dated after your cut-off time. That single number tells you more about your real payment costs than any fee schedule, because it prices the day you silently lost on every late instruction. How the tools were scored Data as of November 2026. The comparison dimensions, transactions per day, value per day, average ticket and participant count, were chosen because the compare format requires every rail to answer the same task set, and these four dimensions are the ones the Bank of Japan’s monthly release reports on an identical basis for all settlement layers. The denominator for every flow figure is the daily average for May 2026 as published; no figure was annualised, monthlyised or converted. JCB reports fiscal years rather than daily averages, so its 53.4 trillion JPY FY2025 volume is quoted as an annual total and was not divided into a daily run rate. All figures used are measured values marked actual in the source data; no forecast or target values appear in this piece. Merchant discount rates are quoted as the ranges stated in the JCB corporate profile and its coverage, which are approximate and contract-dependent. Where the Zengin processing total and the BOJ current-account breakdown describe overlapping flows on different statistical layers, this piece quotes one layer and never sums them. Limitations of the comparison Zengin and BOJ-NET figures come from different statistical layers and were not combined or reconciled. JCB discloses fiscal-year totals, not daily averages; no daily figure was derived from them. Merchant discount rates are approximate published ranges and vary by acquirer contract. Source list Bank of Japan via jp-reports , monthly payment statistics for May 2026, published July 2026 BTW Media , coverage of JCB Corporate Profile 2025-2026, 31 March 2026 Bank of Japan , payment statistics and PFMI disclosure portal, accessed November 2026 (site home) Zengin-Net , Zenginkyo statistical data and PFMI disclosures, 2025 (site home) SWIFT , ISO 20022 migration status for BOJ-NET and FXYCS, November 2025 (site home) This article was prepared by the expert team at Global Infinity Labs, drawing on insights and data provided through its MCP data services. About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. Email: support@globalinfinitylabs.com
More
Indonesia Digs the Nickel. The Headlines Promise the Factories. SeaPRwire

Indonesia Digs the Nickel. The Headlines Promise the Factories.

Four claims about Indonesian manufacturing, checked against ore tables, customs ledgers and the region’s own realization rates SeaPRwire – In October 2026, regional industry reporting carried two numbers about Indonesia in the same breath. One was $30 billion of foreign capital entered into the country’s smelters and refineries by 2026. The other was $121 billion of battery-chain investment opportunities that Indonesian officials pitched to investors in the same year. Both figures still circulate, usually quoted without the other. The gap between them is not a rounding difference. It is the difference between money that landed and money that was presented, and much of what the world reads about Indonesian manufacturing in 2026 sits on the second side of that line. This piece takes four claims that are actually in circulation, checks each against dated records, and then asks a harder question: why do the weak ones spread faster than the strong ones? A claim worth dismantling needs two things. It needs a documented place where it circulates, and it needs a dated record to check against. Both are available here, which is rarer than it should be. The four claims below were not invented for this exercise. Each appears in industry reporting, official pitching or consulting commentary between 2024 and 2026, and each can be laid beside an official or near-official record. The table fixes the claims before the argument starts. Table 1: Four circulating claims about Indonesian manufacturing and what the dated records show Claim in circulation Where it circulates What the dated record shows What survives Indonesia controls about half of global nickel processing Content-site reporting, 2024 to 2026 Mine production share is 66.7 percent for 2025 per USGS; the processing share is claimed near 50 percent by one source and 22 percent by another, neither stating its basis Ore dominance is official; processing dominance is unmeasured $121 billion is flowing into the battery chain Official pitches relayed in October 2026 The figure was presented as opportunities; smelter and refinery FDI stands at $30 billion on a single relay Pitches are not capital Indonesia is the next assembly hub of Asia Bloc FDI headlines, 2024 to 2026 Indonesia ranks 7th of 11 economies in a 2026 manufacturing index The downstream ore story stands; the assembly story does not Moving to Indonesia means leaving China’s supply chain Tariff commentary and consulting decks, 2025 to 2026 China-ASEAN trade reached RMB 4.34 trillion in H1 2026, up 18.2 percent, with intermediate goods at RMB 2.86 trillion The last link moves; the chain does not Source: compiled from USGS Mineral Commodity Summaries 2026 , China customs via the State Council press conference , Factorem AMI 2026 and regional trade reporting, November 2026 One reader’s note before the checks begin. None of the four claims is stupid, and the people repeating them are not fools. Two of the four contain a real fact wearing borrowed clothes, which is precisely why they spread. The test applied throughout is the same one an editor applies to any number: measured by whom, on what basis, over which period, and does the verb match the evidence. The ore number is official. The processing number is not. Start with the hardest fact in the whole story. The United States Geological Survey, in its Mineral Commodity Summaries 2026, put Indonesia’s nickel mine production at 2.6 million tonnes for 2025, which is 66.7 percent of world mine production (USGS, 2026, https://pubs.usgs.gov/periodicals/mcs2026/mcs2026-nickel.pdf). That number has a named author, a stated method and a public file. If the conversation stopped there, no one could object. The claim that circulates, though, is different. Industry content sites have carried versions of “Indonesia controls about half of global nickel processing” since 2024. Another content outlet put the processing share at 22 percent. Both figures sit in the same knowledge base with a conflict flag between them, and here is the part that matters: neither source states its denominator. Half of processing capacity? Half of processed output? Half of value added? A share without a denominator is not a fact. It is a mood. If that were true, if ore dominance simply converted into processing dominance, then Indonesia’s processing share should equal its mine share, and the two circulating numbers, 50 percent and 22 percent, should not be 28 points apart. They are. History also cuts against the shortcut: Indonesia exported raw ore for decades while other countries did the smelting, which is exactly why Jakarta banned ore exports in the first place. The ban worked. Smelters got built. Chinese-financed plants turned Indonesia into the center of the nickel chain. But “the center of the chain” and “half of global processing” are different claims, and only the first is supported. Why did the 50 percent version win? Because the official number is so spectacular that adjacent claims borrow its credibility. Readers who see 66.7 percent of world mine production will not blink at 50 percent of processing; the second number sounds like a rounding of the first. The spread between the two circulating processing figures, 28 percentage points, is the tell. When two sources cannot land within 28 points of each other, the honest sentence is the one the record supports: Indonesia holds a dominant share of the world’s nickel supply at the ore stage, and its processing share is large, growing, and unmeasured by any published official series. $121 billion of what, exactly The second claim has a bigger number and a weaker verb. In October 2026, Thai industry reporting relayed an Indonesian official pitch of about $121 billion in investment opportunities across the electric vehicle battery chain, alongside the $30 billion already credited to smelters and refineries (ThaiNews relay, 2026-10). Read the two numbers as written and nothing is wrong. Hear them repeated, as they now are, as “over $150 billion committed to Indonesian batteries,” and everything is wrong. The $121 billion was presented. It was not committed, not approved, not disbursed. It was a brochure. How do such numbers behave in this region? There is now a track record to check against, and it is unkind. Thailand’s board of investment approved 42 FastPass projects worth more than $10.4 billion and over 27,000 jobs within a year of launch. For the early batches, roughly THB 223 billion were approved and THB 21 billion had landed by early 2026, which computes to a realization rate of about 9.4 percent (ThaiNews, 2026, https://www.thainews.live/thailand-just-fast-tracked-10-billion-in-factories-in-a-single-year). The same pattern shows up in other sectors: one count puts the Asia-Pacific datacenter pipeline that reaches actual construction at 18 percent, Johor’s operating capacity to real workload at about 23 percent, and realized savings from telecom network integrations at 20 to 23 percent. Table 2: What the region’s own records say about announced capital actually landing Stage pair Sector Realization rate Period FastPass approvals to funds actually landed (early batches) Manufacturing, Thailand 9.4 percent 2025 to 2026 Pipeline to under construction Datacenter, Asia-Pacific 18 percent 2026 Operating capacity to actual load Datacenter, Johor about 23 percent 2026 Integration announced to savings realized Telecom, regional 20 to 23 percent 2026 Source: ThaiNews relay and cross-track register compiled in the manufacturing knowledge base, November 2026 Apply even the generous end of that range, 23 percent, to the $121 billion pitch and the plausible landing over the life of the pitch is about $28 billion. Apply the Thai manufacturing precedent and it is closer to $11 billion. If that were true, if the whole pitch converted, then a single chain in a single country would absorb more than half of ASEAN’s total inbound FDI, which one content-site tally puts at $230 billion for 2024 (CXTMS, 2024). Every banker in Asia would have a Jakarta desk by now. They do not, and the pitch’s own authors presumably know it, which is why it was phrased as opportunities. The mechanism that turns the brochure into the bank statement is verb decay. “Officials pitched $121 billion of opportunities” becomes, by the third retelling, “Indonesia is attracting $121 billion.” The conditional dies somewhere between the podium and the paragraph, and no one is assigned to revive it. Pitchers benefit because big numbers attract follow-on interest. Editors benefit because big numbers travel. The only party without an incentive to check is the reader, which is why the check has to be built into the reading. The assembly-hub story runs on someone else’s ledger The third claim is less a sentence than a genre. Versions of “Indonesia is the next Vietnam” have run through regional commentary since 2024, usually supported by bloc-level investment numbers. The most repeated one: ASEAN manufacturing FDI surged 147 percent to $44 billion in 2024 (Manufacturing Asia, 2024). A second: greenfield manufacturing FDI across Vietnam, Indonesia, Thailand and Malaysia reached $124 billion (AlphaBriefing, 2026). Both are real tallies with real sources. Neither is an Indonesian figure. The bloc number gets nationalized in transmission, and the four-country, two-year cumulative gets quoted as if it were one country’s annual pipeline. What does a measured ranking say? The 2026 ASEAN Manufacturing Index from Factorem, covering 11 economies across 43 sub-parameters, places Indonesia 7th of 11 (Factorem, 2026, https://factorem.co). Seventh is not a failure. It is also not “the next assembly hub of Asia,” a title that in any verifiable sense currently belongs to a country whose statistics office publishes two ledgers every month: Vietnam reported $50.36 billion of registered foreign investment and $21.07 billion actually disbursed for January to September 2026 (Vietnam General Statistics Office, 2026-10). Where the assembly boom is verifiable, there is a ledger. Where it is claimed for Indonesia, there is a pitch, and the country’s own investment-ministry series is precisely what the public record lacks. The export mix points the same direction. ASEAN’s exports in 2025 totaled about $264 billion, up 14 percent, with electronics taking 45 percent of the total (AlphaBriefing, 2026). That electronics share is the Vietnam and Malaysia lane, the lane where assembly actually happens. Indonesia’s merchandise trade with China runs through a different door: raw and semi-processed ore flowing out, with monthly exports to China around $6.14 billion in 2026 on industry tallies (AsiaCommerce, 2026, single low-confidence source). A country whose flagship export is ore, whose index rank is 7 of 11, and whose official sector FDI series is a standing gap is many things. An assembly hub is a claim that would need its own ledger, and the ledger does not exist yet. Assembly hubs are also freight machines, and here the record does not merely lack a number, it cannot agree on the one it has. Indonesia’s logistics cost as a share of GDP is put at 23 to 25 percent by one source and 14 to 16 percent by another, both circulating in 2026 with the conflict unresolved. When a country’s core cost metric has a 9-point spread across sources, the spread itself is the finding. An operation that lives on thin margins and fast turns cannot be planned against a cost band that wide, and no amount of industrial park ceremonies changes that until the measurement does. Why does the next-Vietnam story spread so easily? It has a ready-made plot, a familiar cast and a satisfying villain in the tariff schedule. It also borrows the region’s real numbers, the 147 percent and the $124 billion, which are dramatic enough to carry a country claim on momentum alone. And the demographic numbers make it intuitive: a domestic market of 280 million people with a median age of 30 years (AlphaBriefing, 2026) sounds exactly like the labor story an assembly hub needs. Intuitive is not the same as measured, and the measured pieces point elsewhere. Leaving China was never the assignment The fourth claim does the most work in boardrooms and the least in data. Tariff commentary through 2025 and 2026, plus a small industry of relocation consulting, has compressed “China plus one” into something closer to “China minus,” with the implied promise that a factory opened in Indonesia is a chain link removed from China. Check the trade record and the promise inverts. China-ASEAN trade in the first half of 2026 reached RMB 4.34 trillion, up 18.2 percent year on year, and the intermediate-goods component alone was RMB 2.86 trillion (China customs, State Council press conference, 2026-07, https://www.gov.cn/lianbo/fabu/202607/content_7075392.htm). Intermediate goods are parts feeding factories. The fastest-growing lane between China and this region is not consumers buying finished goods. It is factories buying inputs, which is the statistical signature of a chain that has extended, not exited. On the Indonesian side, industry tracking puts imports from China growing 18 to 22 percent year on year in 2026 (AsiaCommerce, 2026, single low-confidence source). Ore flows out, parts flow in, and both sides of the flow are growing. The live examples from the past two weeks read the same way. A Hangzhou chamber of commerce was formally established in Indonesia in early November 2026 to deepen economic, investment and technology ties (CNBC Indonesia, 2026-11-05, https://www.cnbcindonesia.com/news/20261105223719-4-782803/ri-china-makin-mesra-perkuat-kerja-sama-melalui-kadin-hangzhou). The state railway company canceled a plan to import used trainsets from Japan and is weighing new builds from the domestic manufacturer INKA or from China (CNBC Indonesia, 2026-11-05, https://www.cnbcindonesia.com/news/20261105191526-4-782762/impor-krl-bekas-batal-kai-pilih-pesan-lagi-dari-inka-atau-china). Neither decision is a factory relocation. Both are procurement decisions in which China remains the default counterparty. There is also a survey-grade data point for how firms actually structure this. One industry count puts 73 percent of Fortune 500 industrial firms running two to three Southeast Asian nodes (AsiaCommerce, 2026, single low-confidence source). Multi-node is not exit. It is redundancy, and redundancy keeps both ends of the chain fed. The nickname that fits the evidence is the one already circulating among supply-chain analysts: China plus 0.5. The final link moves; the value added mostly does not. Why did the exit story take hold? Because tariffs made relocation feel mandatory, and a mandatory story does not need to be true to be useful. Because “moved to Indonesia” is a cleaner sentence than “added an Indonesian node while doubling orders from Suzhou.” And because the intermediate-goods data that would correct it sits in customs annexes rather than headlines. The correction exists, dated and official, at RMB 2.86 trillion for one half-year. It simply travels slower than the story it corrects. Why these numbers travel Four mechanisms did the damage, and each has a name. The first is unit stripping: a percentage is quoted without its denominator, and half of an unstated base becomes half of everything. The second is verb decay: pitched becomes attracting becomes flowing, and each step down in caution is invisible in print. The third is bloc nationalization: a number covering eleven economies or four countries and two years gets quoted as one country’s achievement. The fourth is echo verification: two content sites carrying the same figure feels like independent confirmation, but low-cost outlets reprint each other, and one press release can dress up as two sources. There is a fifth mechanism that is less a trick than a temptation. The real Indonesian numbers are so good that they make exaggeration feel safe. A country that genuinely mines two-thirds of the world’s nickel does not need to inflate its processing share, its battery pipeline or its assembly prospects, and yet all three got inflated anyway, by different hands, for different reasons. The ore fact did the persuading. The parked claims just followed it through the door. What survives the check Strip the four claims down to what dated records support and a smaller, stranger country appears, one that is easier to invest in precisely because it is easier to describe. The ore fact survives untouched: 2.6 million tonnes mined in 2025, 66.7 percent of the world total, published with a method anyone can download (USGS, 2026). The smelter capital survives with a caveat: $30 billion into smelters and refineries on a single relay (ThaiNews, 2026-10), an order of magnitude consistent with the post-ban construction wave, but one ledger, not two, and worth re-checking whenever an official series appears. The frame that fits the evidence is not “next assembly hub.” It is resource-state industrialization: a country converting geological advantage into processing capacity, and discovering, as every resource state does, that the constraints are everything around the ore. Power is one. Equipment vendors now market microgrids to Southeast Asian manufacturers on the premise of rising electricity costs and supply disruptions (Sungrow via PR Newswire, 2026-10-22), which is a marketing document, but a revealing one: the constraint is strong enough to sell against. Freight is another, contested at 23 to 25 against 14 to 16 percent of GDP. Social license is a third, and it is not decorative. Thousands protested in Jakarta and other cities in late October 2026 over economic hardship, graft and wildfire haze (Bangkok Post, 2026-10-28, https://www.bangkokpost.com/world/3345215/eat-the-rich-indonesians-fed-up-with-graft-wildfires), and Singapore’s parliament moved in early November 2026 to tighten its cross-border haze law with arrest powers and bigger fines (Bangkok Post, 2026-11-04, https://www.bangkokpost.com/world/3348616/singapore-fighting-haze-with-arrest-powers-bigger-fines). Haze is a land-use problem, and land use is upstream of every smelter, plantation and industrial park in the chain. Even the smaller resource facts fit: gold output is predicted to reach 104 tonnes for 2025, a forecast, not a tally, supportive of electronics and investment demand (CNBC Indonesia, 2026-10-30). None of this says the industrialization is failing. It says the binding constraints are domestic, measurable and already flashing. For anyone quoting Indonesian manufacturing numbers this quarter, four questions do most of the work. Which ledger, registered or disbursed? Which denominator, ore or processed, bloc or country? Which period, one year or two cumulative? And which verb, pitched or landed? If a number clears all four, cite it with confidence. If it clears none, it is probably on its second lap around the internet, and it will still be circulating next quarter. How each claim was checked Data as of November 2026. Each of the four claims was paired with the most official record available and checked on three axes: denominator, period and verb. The ore figures come from the USGS Mineral Commodity Summaries 2026 nickel chapter, an annual published series. The China-ASEAN trade figures come from customs data released at a State Council press conference in July 2026, with the intermediate-goods line used as the proxy for chain linkage; the estimate is customs-classified, not author-computed. The realization rates in Table 2 are computed from published approval and landing pairs, such as THB 21 billion landed against THB 223 billion approved, and are treated as precedents, not forecasts. Claimed figures that lack an official series, including the 50 and 22 percent processing shares and the $121 billion pitch, are reported as claims with their circulating sources named. No figure was adjusted, annualized or rebased. Limitations The nickel processing share has no published official denominator, so any number quoted for it stays a claim. The $30 billion smelter figure and the AsiaCommerce trade tallies each rest on a single relay. Pitch figures mutate as they are retold; circulated versions may differ from the ones checked here. Sources USGS Mineral Commodity Summaries 2026, nickel chapter , Indonesia mine production and world share, January 2026 State Council press conference, China customs , first-half 2026 foreign trade including ASEAN and intermediate goods, July 2026 Factorem, AMI 2026 , ASEAN Manufacturing Index ranking for Indonesia, 2026 (site home) AlphaBriefing , ASEAN greenfield manufacturing FDI and export tallies, 2026 (site home) Manufacturing Asia , ASEAN manufacturing FDI growth coverage, 2026 CNBC Indonesia , KAI trainset decision and Kadin Hangzhou chamber reports, November 2026 Bangkok Post , Jakarta protests and Singapore haze-law reports, October to November 2026 ThaiNews , FastPass approvals and realization-rate analysis, 2026; AsiaCommerce trade tallies, 2026 (no public link) This article was prepared by the expert team at Global Infinity Labs, drawing on insights and data provided through its MCP data services. About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. Email: support@globalinfinitylabs.com
More
Who Counts the Coders in China’s AI Relay Economy? SeaPRwire

Who Counts the Coders in China’s AI Relay Economy?

Two compliance ledgers track AI across mainland China, Hong Kong and Taiwan. The developers who reach foreign models through resellers appear in neither. AsiaPresswire – Somewhere on a mainland tech payroll sits an engineer who did nothing unusual. He pays for a Claude subscription himself, on the two hundred dollar Ultra tier, and he has been using it on company code. By the morning of 4 November 2026 he could read, from three different newsrooms, what his position is worth in the compliance system. TechNode reported that ByteDance has been tightening access to Claude and Codex across the company, and that the restriction reaches staff who pay for the tools out of their own pockets (TechNode, 2026-11-04). The consumer outlet ifanr ran a headline asking whether the sky over the relay stations, the resale shops of the AI world, was starting to fall (ifanr, 2026-11-04). GeekPark’s morning brief added that ByteDance now restricts employees from using personal AI accounts for work (GeekPark, 2026-11-05). None of the three stories printed the name of a single user. The engineer exists in the reporting as a restriction, a headline and a bullet point. This article is about why the people in his position, who number somewhere between a rounding error and a market, cannot be found in either of the two ledgers that claim to count AI in Greater China. Three newsrooms, one workday The paper trail of one workday shows how the situation reached him. TechNode’s report of 4 November 2026 stated the rule plainly: “Even if employees pay for Claude or Codex out of their own pockets, they may no longer be able to use these tools freely to work with company code and internal documents” (TechNode, 2026-11-04). The tightening, the report said, had been rolling across the company since the beginning of the period it covered. The verb matters more than the date. Nobody announced a policy with a document number. Employees learned the boundary the way the report described it, through access quietly narrowing, and the reporting itself was assembled from sources inside the company rather than from any published rule. The same day, ifanr published a piece under a headline that translates as “Anthropic barely flexed, and the sky over the relay stations is already falling?” (ifanr, 2026-11-04). A relay station, zhongzhuanzhan in the trade’s own shorthand, is a reseller that buys or pools accounts on a foreign frontier model, resells access in Renminbi, and shields the end user from the payment and geography checks that the original provider enforces. The ifanr piece carried the regulatory tag, and its premise was a single company action: when Anthropic adjusts enforcement, the resale layer wobbles. The article did not publish a user count. It did not need one for the mood it was describing, which is precisely the problem this article returns to. GeekPark’s morning brief of 5 November 2026 bundled the ByteDance restriction into a list beside two other items, the mainland test launch of Apple Intelligence and a report that Chinese customers are expected to receive only about 1 percent of NVIDIA’s graphics card orders (GeekPark, 2026-11-05). Read as a list, the brief was three separate stories. Read as a ledger, it was one row in a book where every entry is a company decision and no entry is a user. That is the shape of the whole week’s coverage, and the shape is the finding. Table 1: What Greater China’s compliance papers counted in the week of 31 October to 5 November 2026 Date Document (publisher) What it counts What stays outside 2026-10-31 Claude quota report (QBitAI) product quota relief by tier where the users sit 2026-11-04 ByteDance access tightening (TechNode) employee tool risk, incl. self-paid use scale of personal use 2026-11-04 Relay station market mood (ifanr) reseller reaction to enforcement any user number 2026-11-04 Apple Intelligence China beta (TechNode) official channel features the existing relay cohort 2026-11-04 Bank SinoPac breach (iThome, Taiwan) incident impact on customers third-party tool usage 2026-11-04 MoneySmart breach (Hong Kong Free Press) affected customer data affected user totals 2026-11-05 Digital 2027 Singapore (e27) measured monthly AI usage, 9 in 10 mainland user base Source: compiled from QBitAI , TechNode , ifanr , iThome , Hong Kong Free Press and e27 How the engineer’s own week actually went, whether he moved to a domestic model, a relay plan, or a personal project abandoned at two in the morning, none of the documents say. The honest sentence is short: no relay user has spoken publicly in any of the reports cited here, under a name or a handle attached to a verifiable identity. What can be reconstructed is the position itself, and the position is documented well enough. How large is the group, honestly The direct answer is that nobody publishes a count, and the absence is not an accident of secrecy. It follows from how both compliance systems are built. Still, three indirect readings bound the question, and each comes with a stated limit. The first reading comes from the provider’s own financials. Anthropic filed its S-1 prospectus with the US Securities and Exchange Commission on 26 October 2026, listing first half 2026 revenue of US$16.29 billion, against US$1.16 billion in the same months a year earlier, and a first ever quarterly operating profit of US$974 million in the second quarter of 2026 (GeekPark, 2026-10-31). An updated filing put third quarter revenue at US$16.96 billion, up 47 percent quarter on quarter, with an operating loss of US$567 million after the profitable quarter, and roughly US$895.4 billion in compute purchase commitments involving partners such as Amazon and Google (GeekPark, 2026-11-04). Growth at that pace means paid capacity is being absorbed faster than it is being added, and resale access is one of the ways capacity gets absorbed. What the filings do not contain is any geographic or channel split that would separate a relay purchase from a corporate seat. The number proves demand. It cannot prove the cohort. The second reading comes from product quota. On 31 October 2026, QBitAI reported that Claude had removed the five hour usage cap, with the two hundred dollar Ultra tier users unbundled first, under the headline’s own phrasing that the “$200 Ultra users go first” (QBitAI, 2026-10-31). Quota relief at the top tier is what a provider does when heavy users, the kind who write code all day, are the marginal revenue. Heavy users are exactly the profile of the relay customer. Again the inference points at the group without measuring it. The third reading is the contrast case, and it shows what a counted user base actually looks like. The Digital 2027 Singapore report, released on 5 November 2026 by We Are Social and Meltwater, found that nine in ten Singapore internet users reach for an AI tool every month, while only about one in three say they are comfortable doing so (e27, 2026-11-05). Singapore measures its users with a survey, a sample and a fieldwork window. The mainland relay cohort has none of those three things. The gap between habit and comfort that Singapore can quantify is the same gap, in the same market region, that nobody quantifies for the relay users. One more contrast, from the economy next door, makes the blindness sharper. China’s customs authorities announced 39.94 trillion CNY in goods trade for January to September 2026, up 18.8 percent year on year, with a surplus of US$938.1 billion, and full year 2025 goods trade with ASEAN had already crossed US$1 trillion (General Administration of Customs briefing, 2026-10-14). Goods crossing the border are counted per shipment, per tariff line, per trading partner. Services and model access crossing the same border in the same weeks are counted by no one, because the relay layer was designed to make them look domestic. A customs system that resolves trade to the tariff line coexists with an AI market whose customer side has no denominator at all. Data as of November 2026. What the statements share Set the week’s public statements side by side and the common thread is easy to miss because it is a null set. TechNode’s report counts employee risk. ifanr’s headline counts market mood. GeekPark’s brief counts company decisions. QBitAI counts quota. Not one of the four outlets quotes a relay user, a cancelled subscriber, or a developer who moved to a domestic model, and the reason is not hostility. It is visibility. A user inside a relay chain is, by design, invisible to the provider’s account system, to the payment trail, and to any journalist who wants an on the record interview that does not expose the user to the exact enforcement the reporting describes. The corporate side speaks because it has documents. The regulator side speaks because it has lists. The provider side speaks because it has filings. The relay user has none of the three, only the experience the reports gesture at. In the vocabulary of evidence, every statement about this group is secondhand, and the piece you are reading inherits that limit rather than pretending to clear it. Where the gap comes from Two conditions, one on each side of the border, produce this cohort. Either condition alone would not. That is the argument of this section, and it is the load bearing one. On the supply side, the door never opened Anthropic does not sell Claude directly inside mainland China, and OpenAI has likewise kept its consumer service outside the market, which is why the relay layer exists at all. The week’s reporting showed the same structure holding at the infrastructure level. Chinese customers were reported to be on track to receive only about 1 percent of NVIDIA’s graphics card orders (GeekPark, 2026-11-05), and Washington’s trade enforcement kept tightening around the region: the Section 301 tariff program that took effect on 24 July 2026 covers 60 economies and applies a 12.5 percent rate to Singapore (Federal Register notice, 2026-07-24). A developer in Shenzhen who wants the current frontier coding agent cannot buy it the way a developer in Singapore can, at list price, on a card, with a support contract. The supply side did not merely forget mainland users. It priced them, sanctioned around them and carded them out. Apple’s arrangement shows what official entry costs. To ship Apple Intelligence in the mainland, Apple partnered with Alibaba and routed the service through Qwen, the Alibaba model, opening a developer beta on 4 November 2026 alongside the iOS 27.3 test build, with a public release planned for December 2026 (TechNode, 2026-11-04). Official entry required a domestic partner, a domestic model and a feature set cut to fit. The door opens, when it opens, on the terms the compliance system sets. At home, substitutes arrived with conditions The second condition is the demand gap that domestic models have not yet closed. The same Apple Intelligence beta that landed on 4 November carries a first batch of features that includes live translation, writing tools, visual intelligence and photo cleanup, while the next generation Siri announced at WWDC26 stays outside this update (GeekPark, 2026-11-04). Translation and writing are table stakes. The relay market, on the week’s own evidence, is concentrated somewhere else, in agentic coding tools, Claude Code and Codex, the products the ByteDance restriction names specifically. Policy is pushing the domestic stack to close the gap: the 15th Five Year Plan sets a target of 7 percent average annual growth in research and development spending for 2026 to 2030 (Chinese government work report commentary, 2026-03-05), and analysts project 4.5 to 5.0 percent GDP growth across the plan period (Galaxy Securities chief economist Zhang Jun, via China.com.cn, 2025-10-24). Both figures are targets and forecasts, not accomplished facts, and both say the substitution is funded and scheduled rather than finished. Now run the two conditions against each other. If the supply side were open, the relay user would be an ordinary customer with a receipt, and the provider’s ledger would count him. If the domestic substitutes were complete, the relay user would have no reason to exist, and the domestic regulator’s ledger would count him where he actually buys. The cohort persists because neither is true: the foreign door is closed by the provider’s compliance, and the domestic shelf lacks the specific tool, the coding agent, that the workload requires. Single cause explanations fail in both directions, which is why the group has lasted through successive enforcement rounds. Why corporate compliance hardened in the same week The employer’s rule, the one that reached the engineer who pays his own way, did not come from nowhere. It landed in a region that spent the same week absorbing data breach disclosures, and the chronology is worth keeping because it makes the corporate logic legible rather than paranoid. In Hong Kong, the finance portal MoneySmart told customers on 4 November 2026 that it had become aware of a breach the previous Thursday, after hackers compromised internal IT systems, and that “These systems hold personal data that customers share with us when they compare or apply for financial products through MoneySmart” (Hong Kong Free Press, 2026-11-04). In Taiwan, Bank SinoPac held an emergency press conference on the evening of 4 November 2026 and confirmed that abnormal transfers traced to hackers exploiting a security setting in a vendor’s system, with initial reporting putting the impact at about 400 customers and roughly NT$100,000 per transferred amount before the bank corrected the mechanism (iThome, 2026-11-04). In the same market, the e-commerce ERP vendor Mallbic suffered a security incident that pushed the shop platform Shopline to rotate API keys, exposing data merchants had imported (iThome, 2026-11-04). Hong Kong policy responses moved in the same direction: a lawmaker proposed at a Legislative Council meeting that estate owners’ votes be verified through a government managed digital identity platform to fight bid rigging (Hong Kong Free Press, 2026-11-05). Each incident is a different system with a different owner. The pattern they share is the one a corporate security office reads: third party tools, vendor settings and personal accounts are where data leaves. An employee who pipes company code into an account bought through a reseller is, in that frame, not a productivity story. He is the vendor setting. The ByteDance tightening that TechNode reported is what that frame produces as policy, and it explains why the rule reaches self paid subscriptions. The company cannot tell, from its side of the network, which personal subscription is clean, so it treats the category as the risk. The engineer’s own money bought him no exception, because the ledger his employer keeps does not have a column for payment source. What the official channel changed that week The strongest argument against this piece runs through the same documents, and it deserves a full statement rather than a footnote. Official channels are widening. Apple Intelligence reaches mainland iPhones in December 2026 with Qwen inside Siri (TechNode, 2026-11-04). Claude lifted its five hour cap at the end of October (QBitAI, 2026-10-31). Domestic models absorb more of the workload every quarter, backed by the R&D growth target of 7 percent a year. If the official shelf keeps filling, the relay cohort shrinks by attrition, and the blind spot closes itself. On that reading, this article describes a transitional generation of users, not a permanent class. The response is about the ledgers, not the window. Attrition reduces the size of the group. It does not create a count, because the reason the group is uncounted is structural: the provider’s books record accounts, the regulator’s books record licensed services, and the corporate books record sanctioned tools. A user can leave the relay market entirely and still never appear in any of the three, as long as the market he enters is measured only through its suppliers. Singapore’s nine in ten, counted monthly, is what closing the blind spot looks like when someone decides to do it. Nothing in the mainland’s current architecture produces that survey, for this cohort, at any size. There is also a fairness point inside the counterargument. The transition, however fast, runs on people who took compliance risk with imperfect information, paid real money and are now being squeezed from both sides at once, by the provider’s enforcement above and the employer’s rule below. A market that closes a window should be able to say how many people were in it. Greater China’s AI compliance regime, in the first week of November 2026, cannot. The counting method Definition first. A relay user, for this piece, is a person physically or corporately inside mainland China who reaches a foreign frontier model through a third party reseller account rather than a direct provider subscription. The definition is behavioral, not legal, because no legal category names this group. The denominator is unknown, and the piece does not estimate one. What Table 2 lists are the indicators that were checked and what each can and cannot carry. The time frame is the week of 31 October to 5 November 2026 for events, the third quarter of 2026 for financials, and January to September 2026 for trade statistics. Where a figure is a target or a forecast, the text keeps the target grammar. No sampling was possible, so no sample size is claimed; the estimated reading of demand comes from provider revenue growth, which is a proxy for absorption, not a count of persons. Nothing in the method adjusts for currency, seasonality or churn, and none of the proxies should be summed. Table 2: Indicators checked for sizing the relay-user group, and the limit of each Indicator (unit, period) Value What it can proxy What it cannot show Anthropic revenue (US$ billion, Q3 2026) 16.96 paid capacity being absorbed geographic or channel split of buyers Revenue growth (percent, Q3 vs Q2 2026) 47 acceleration of demand who the marginal buyer is China goods trade (trillion CNY, Jan-Sep 2026) 39.94 the measured economy beside the unmeasured one service or model-access flows R&D spending growth (percent per year, 2026-2030) 7 (target) pace of domestic substitution whether the coding-agent gap closes Apple Intelligence China release (date) Dec 2026 (planned) official channel widening size of the existing relay cohort Source: compiled from GeekPark on the updated S-1 figures, GeekPark on the original filing, and the General Administration of Customs trade briefing; the R&D figure is a plan target, and the December release is a stated plan, not a shipped fact. The sourcing rule follows from the method. Every fact in this piece comes from published reporting, a regulatory filing as covered by the press, or official statistics, and each carries an inline attribution with date. The situation of the unnamed engineer is a composite reconstructed strictly from those documents: no individual was interviewed, no pseudonymous character accuses any named institution, and no quotation was invented. Direct quotes appear only where a source published them, including the TechNode sentence on self paid access, the ifanr headline, the MoneySmart breach statement and the QBitAI quota report. Where a group would naturally supply testimony and none exists in the record, the text says so rather than filling the silence. A count of this group would require one of three things: a provider disclosing channel geography, a survey with a sample frame, or a regulator publishing enforcement totals by user type. As of the first week of November 2026, none of the three exists. The group is real, its position is documented, and its number is not. Limitations of the survey base The relay-user group has no published denominator; every size statement here is a proxy inference, not a measurement. Anthropic’s financials are covered through secondary reporting of the S-1 filings, one step from the primary document. All user-side evidence is secondhand; one named interview could change the texture of the conclusion. Source notes TechNode , ByteDance reportedly tightens access to Claude and Codex, 4 November 2026 ifanr , relay station market piece, 4 November 2026 GeekPark , morning brief with ByteDance personal AI restriction, 5 November 2026 GeekPark , Anthropic S-1 filing coverage, 31 October 2026 QBitAI , Claude removes the five hour cap, 31 October 2026 Hong Kong Free Press , MoneySmart breach disclosure, 4 November 2026 iThome , Bank SinoPac incident press conference, 4 November 2026 e27 , Digital 2027 Singapore findings, 5 November 2026 General Administration of Customs , January to September 2026 trade data, 14 October 2026 This article was prepared by the expert team at Global Infinity Labs, drawing on insights and data provided through its MCP data services. About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. Email: support@globalinfinitylabs.com
More
Gulf Power Arithmetic: Demand Arrives in Months, Transformers Take Years SeaPRwire

Gulf Power Arithmetic: Demand Arrives in Months, Transformers Take Years

Record solar and nuclear capacity is online, the interconnection queue runs years deep, and gas fills the gap in between AsiaPresswire – Dubai’s Mohammed bin Rashid Solar Park reported 3,860 MW of solar capacity in operation, with a published plan to exceed 8,000 MW by 2030 (Dubai Electricity and Water Authority, June 2026). Roughly nine hundred kilometers to the west, Saudi Arabia closed 2025 with about 12.3 GW of renewable capacity actually running, against a national target of 130 GW (Vision2030.ai, March 2026). Both governments were courting the same customer: the builders of AI data centers. Saudi Arabia has been investing billions of dollars to position itself as the Middle East’s cloud hub (Arab News, October 2026), and at the ADIPEC opening in Abu Dhabi on 2 November, OpenAI’s chief executive, asked to name his one challenge today, answered with a single word: “Energy” (PRNewswire, November 2026). The judgment this piece defends is easy to state and easy to attack. The binding constraint on the Gulf’s energy transition is neither capital nor sunlight; it is delivery equipment, above all the transformers and grid interconnection whose lead times run 3 to 4 years (Vision2030.ai, March 2026). If that reading is right, each incremental gigawatt of AI demand will be met with gas before it is met with panels, no matter how fast the solar parks are announced. If it is wrong, the falsifying signals are specific and datable: transformer lead times collapsing below a year, or Saudi operational capacity doubling well before the end of 2027. The rest of this piece builds the case, shows the arithmetic, and marks where it can break. Two clarifications before the argument starts. Capacity means grid-connected generating hardware, measured in gigawatts; a generation share means the slice of actual electricity produced, measured in percent of the annual total. The two numbers are not interchangeable, and most confusion about the Gulf’s transition comes from reading one as the other. This piece keeps them apart throughout. What is already bolted to the grid On paper, the Gulf builds power infrastructure faster than almost anyone. The United Arab Emirates operates the Arab world’s only commercial nuclear plant, the Barakah facility, which reached its full 5.6 GW capacity with all units in service in 2024 (EIA Country Brief, May 2026). Dubai’s solar park has been expanded in stages for over a decade and is now one of the largest single-site solar programs on earth (DEWA, June 2026). The developer ACWA Power, headquartered in Riyadh, reported a global renewable portfolio of 52.3 GW in the first half of 2026, of which more than 34 GW sits inside Saudi Arabia (ACWA Power Q2 2026 report, June 2026). Capital, engineering talent and land are all present at scale. No serious observer disputes any of this. In practice, the generation data tell a more restrained story. Solar supplied about 12 percent of UAE electricity in 2024, according to the same EIA country analysis that records the Barakah milestone (EIA Country Brief, May 2026). That share is respectable, and it has been rising, but it sits a long way from what the installed hardware alone would suggest. The difference between the two numbers is the delivery system: nuclear runs constantly, solar produces only when the sun is up, and the grid must absorb both without losing stability. A capacity figure records what has been bolted on. A generation share records what actually flows. The Gulf’s buildout to date has been excellent at the first and slower at the second. The ACWA Power number deserves a second look, because it points at where the binding edge sits. A Saudi developer can assemble 52.3 GW of projects across multiple continents, financing them faster than most Western utilities can permit them (ACWA Power Q2 2026 report, June 2026). The company can do that because panels, trackers and financing are commodities that move at commercial speed. What the same company cannot compress is the queue at the substation. When the home market’s operational count stands at 12.3 GW while the national target reads 130 GW, the shortfall is not in the ability to buy hardware. It is in the ability to connect it. Table 1: Four flagship Gulf power programs, what is running versus what is promised, as of the latest library readings Program Operational capacity Target capacity Target year Measure type MBR Solar Park, Dubai (DEWA) 3,860 MW over 8,000 MW 2030 operational actual; target announced Barakah nuclear, UAE 5.6 GW not applicable not applicable actual, full operation 2024 Saudi NREP renewables 12.3 GW (end 2025) 130 GW 2030 operational actual; target announced ACWA Power global portfolio 52.3 GW (Q2 2026) not applicable not applicable actual, developer portfolio Source: Dubai Electricity and Water Authority , June 2026; EIA , May 2026; Vision2030.ai , March 2026; ACWA Power , June 2026 What the new load looks like The demand side of this story is not hypothetical, and it is not slow. Saudi Arabia’s data center buildout has been running for years and is explicitly framed as a national race to become the region’s cloud and AI hub, with investments described in the billions of dollars (Arab News, October 2026). At the ADIPEC opening on 2 November, Sam Altman told the energy industry that abundant, reliable energy is critical to unlocking the next wave of AI-driven innovation and economic growth (PRNewswire, November 2026). When the man whose industry consumes the electricity stands in an oil capital and names energy as the gating factor, the demand signal is not a forecast. It is a purchase order waiting for a supplier. The producer side answered in kind, and the answer has a contract attached. ADNOC, with the Abu Dhabi technology group G42, announced at the same event that it will become the first energy company to deploy OpenAI Frontier, applying advanced AI systems to oilfield development and commercial operations (PRNewswire, November 2026). Sultan Al Jaber, the UAE’s industry minister and ADNOC’s group chief executive, told the opening that the global energy industry must fundamentally rethink how it builds, protects and delivers secure energy (PRNewswire, November 2026). Both statements are directionally about the same thing: the region intends to be the place where compute and energy are provisioned together. There is a telling absence in all of this. The demand is announced in dollars, not in megawatts. Neither the Saudi cloud-hub coverage nor the ADIPEC material publishes a megawatt figure for the data center load the region is courting (Arab News, October 2026; PRNewswire, November 2026). Commercial teams quote investment sums because those are approved; grid teams quote megawatts because those must be delivered. The missing number is not an accident of coverage. It marks the boundary between what the region’s economy has committed to and what its wires have been scheduled to carry. The equipment queue that sets the pace The published diagnosis of Saudi Arabia’s delivery problem is unusually direct. The constraint on the 130 GW renewable program is the grid, not the panels, and the transformer lead time inside that constraint runs 3 to 4 years (Vision2030.ai, March 2026). Analysts tracking the program estimate that operational capacity will reach somewhere between 45 and 74 GW by 2030 rather than the announced 130 GW (Vision2030.ai, March 2026). The estimate range is wide, which is itself informative: even its optimistic end sits at 57 percent of the target. The arithmetic behind that gap is simple enough to do on one line. Holding the 130 GW target against 12.3 GW operational at end-2025 leaves 117.7 GW to build in five years, an average of about 23.5 GW per year. The analyst estimate range, converted the same way, implies 6.5 to 12.3 GW per year of actual delivery. The top of the expected range is roughly half the required pace, and the bottom is barely a quarter. Nothing in this computation is controversial; the disagreement between the target and the estimate is entirely about how fast equipment can be manufactured, shipped and connected. Why the queue rather than the panels comes first is a question of industrial structure. Solar modules are produced in enormous volume by a competitive global supply chain, and a buyer with capital can get them in months. High-voltage transformers and grid interconnection equipment are produced by a much narrower industrial base, ordered years ahead by utilities worldwide, and manufactured against order books that every electrifying economy is now joining (Vision2030.ai, March 2026). A Gulf ministry can shorten the financing cycle. It cannot shorten the factory cycle, because the factory is not in the Gulf. The pattern is not unique to the region, which strengthens rather than weakens the reading. Indonesia announced a 100 GW solar program in August 2026 while its installed base stood at about 1.5 GW (China Energy Storage Network, August 2026). Everywhere the demand curve has steepened, the same gap between announcement and delivery has opened, and everywhere it has opened, the residual constraint has landed on the same class of equipment. The Gulf’s version of the gap is distinctive in one respect only: the money is genuinely there. When capital is not the constraint and land is not the constraint and sunlight is not the constraint, the schedule is set by whatever is left, and what is left is the wires. The queue also fixes the calendar in a way that announcements cannot move. Equipment ordered this year, against a 3 to 4 year lead time, arrives in 2029 and 2030 (Vision2030.ai, March 2026). The order books for 2026 and 2027 are already written, which means the capacity that serves any new load in the next three years is, with near certainty, capacity that has already been manufactured or is already connected. Demand that shows up before then does not stretch the construction schedule. It reroutes itself to whatever can be dispatched today, and in this region that fuel is gas. Announcements can be issued in a week; the wires they depend on were ordered by somebody else three years ago. Two variables, both moving the wrong way The trend call in this piece rests on two structural variables, each of which can be tracked with a published number. The first is the demand arrival rate: how fast new load, above all data center load, shows up in the Gulf’s power planning. Its operational proxy is the sequence of announced investments and the megawatt asks behind them, which are currently visible only as billion-dollar programs (Arab News, October 2026). The direction is up, and the ADIPEC framing, where the region’s top energy leadership and the largest AI supplier shared a stage to discuss provisioning compute with energy, is a leading indicator in its own right (PRNewswire, November 2026). The second variable is the interconnection lead time: how long a newly built power asset waits before it can push electrons. Its published proxy is the transformer queue, at 3 to 4 years for the Saudi program (Vision2030.ai, March 2026). The direction here is not obviously improving, because the queue is a global variable. Every grid in every electrifying economy is ordering from the same factories, so a Gulf utility that wants to jump the queue must outbid everyone else on the list, and the list grows every year. The two variables matter most in combination, and their independence is what makes the combination reliable. The demand arrival rate is set by capital budgeting decisions in Seattle, San Francisco and Riyadh’s technology holdings. The interconnection lead time is set by manufacturing capacity in transformer plants and by utility procurement cycles. Nothing that Altman announced in Abu Dhabi shortens a transformer order, and nothing in a factory’s production schedule changes how much compute the region wants to buy. When two lags this independent point in the same direction, the gap between announced and delivered capacity does not close on its own. It compounds. That is the structural claim underneath the trend judgment, and it is falsifiable at both ends. Who absorbs the shortage first The first group to feel the shortage is the one with deadlines. Data center operators commission on schedule, because their revenue starts only when the racks are powered, and a schedule that waits four years behind a transformer order is not a schedule any of them accepted. Where the national utility controls dispatch, the load that must arrive on time gets matched with generation that can also arrive on time, and in the Gulf that means gas. The 12 percent solar share in the UAE, recorded after years of aggressive panel installation, shows what the system actually runs on between the sun-up hours and the peak (EIA Country Brief, May 2026). Gas is the swing supply today, and every gigawatt of demand that arrives before its interconnection does lands on gas by default. The second group is downstream and offshore: the buyers of Gulf energy security. Since the disruption in the Strait of Hormuz in March 2026, the import bill of Southeast Asian economies has risen by about 3.36 billion USD per month, with 55 percent of ASEAN crude imports sourced from the Middle East (The Diplomat, June 2026). Buyers who have lived through a delivery shock respond by buying storage and optionality rather than promises. The Philippines is currently courting the United Arab Emirates to build a strategic oil storage facility that would turn the country into a regional energy hub and cushion domestic consumers from price volatility (Philstar, November 2026). Demand for Gulf-adjacent storage is a direct market readout of how much importers trust delivery, and that trust is repricing in real time. The third group is the region’s own balance sheets, through the security line item. The United States ordered some of its diplomats to leave Saudi Arabia in October 2026 over the threat of Houthi attacks (DW, October 2026). Physical risk to energy infrastructure raises insurance and hardening costs, and capital spent on protection is capital not spent on expansion. None of this stops the transition. It reshuffles the order in which projects get wired, and the projects that keep their place in the queue are the ones with sovereign backing, which is to say the oil and gas assets first, the export-facing assets second, and the merchant renewable projects last. Within each national program, the practical allocation follows signature order. Projects that reached agreements earlier hold earlier interconnection positions, and new entrants join the back of a queue that already runs years deep (Vision2030.ai, March 2026). An AI campus announced this quarter is, in grid terms, a customer for the early 2030s unless it brings its own generation. The loads that cannot wait buy gas turbines; the loads that can wait become the market for whatever the solar parks deliver after 2030. What would falsify this reading The judgment above is built to be checked, and four signals would break it. First, if published trackers show transformer lead times falling below one year, the delivery constraint dissolves and the gap closes on the target’s schedule. Second, if the next EIA country analysis shows the UAE solar generation share moving decisively past the 2024 reading of 12 percent, approaching a fifth of generation, then delivery is keeping pace with installation and the bottleneck argument weakens (EIA Country Brief, May 2026). Third, if Saudi operational renewable capacity passes roughly 25 GW before the end of 2027, doubling inside two years, the delivery pace has accelerated beyond the analyst range of 45 to 74 GW by 2030 (Vision2030.ai, March 2026). Fourth, if Dubai’s solar park passes its 8,000 MW mark ahead of the 2030 date (DEWA, June 2026), the flagship program will have outrun its own queue. There is also a demand-side falsifier. If Gulf data center operators begin publishing power purchase agreements dominated by new solar and storage rather than gas, then the delivery system is matching clean supply to new load, and the argument that gas fills the gap first fails on the evidence. Today no such disclosure exists in the material reviewed for this piece; the demand side is documented in investment sums, not in generation mixes (Arab News, October 2026). A final honesty check concerns the indicators themselves. The two leading variables are watched through different owners: the demand variable through commercial announcements, the delivery variable through utility and manufacturing data. If both owners start reporting the same good news at the same time, from the same type of document, the independence that gives this call its strength is gone, and the judgment should be rebuilt from scratch. The arithmetic behind the call Data as of November 2026. The core computation uses four inputs, each with a defined denominator. Operational capacity figures (12.3 GW for Saudi Arabia at end-2025; 3,860 MW for the Dubai solar park; 5.6 GW for Barakah in 2024) are counts of grid-connected hardware, taken from Vision2030.ai (March 2026), DEWA (June 2026) and the EIA country brief (May 2026). The target figure (130 GW by 2030) is a state-announced goal, not a funded construction schedule. The gap computation divides the difference, 117.7 GW, by the five remaining years to get the required pace of 23.5 GW per year, then converts the analyst estimate range of 45 to 74 GW the same way to get an expected pace of 6.5 to 12.3 GW per year. The 12 percent UAE figure is a generation share, with total annual generation as its denominator, and it is deliberately never compared against a capacity number. The transformer lead time of 3 to 4 years is used as a proxy for the whole interconnection queue because it is the only component with a published duration; the true queue includes permitting and network studies that the sources do not time. The Indonesia comparison (100 GW announced against about 1.5 GW installed, China Energy Storage Network, August 2026) is used as a pattern check, not pooled into any Gulf computation. No figure in this piece has been rebased, deflated or seasonally adjusted. Limitations in the data The 3 to 4 year transformer lead time rests on one tracker, Vision2030.ai, without a public queue disclosure behind it. Saudi data center demand has no published megawatt figure; the demand side rests on investment announcements. The UAE solar share is a 2024 generation figure and may be stale relative to 2026 installation. Data sources Dubai Electricity and Water Authority , MBR Solar Park strategic initiative page, accessed November 2026 EIA , United Arab Emirates country analysis brief, May 2026 Vision2030.ai , Saudi Arabia renewable capacity encyclopedia entry, March 2026 ACWA Power , Q2 2026 report, June 2026 PRNewswire , ADIPEC 2026 opening coverage, November 2026 Arab News , Saudi data center coverage, October 2026 Philstar , Philippines UAE oil storage report, November 2026 DW , US diplomats departure report, October 2026 The Diplomat, Southeast Asia energy security reporting, June 2026 (no public link) China Energy Storage Network, Indonesia 100 GW solar program reporting, August 2026 (no public link) This article was prepared by the expert team at Global Infinity Labs, drawing on insights and data provided through its MCP data services. About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. Email: support@globalinfinitylabs.com
More
Canada’s Care Beds Are Thinning Out. The Oldest Wave Has Not Peaked. SeaPRwire

Canada’s Care Beds Are Thinning Out. The Oldest Wave Has Not Peaked.

Long-term care beds per 1,000 residents over 75 fell from 66.6 to 63.5 between 2021 and 2025, and the 85+ population is projected to more than double by 2051 SeaPRwire – Canada’s long-term care system is shrinking by one measure at the same time as its client base is growing by every measure. Between 2021 and 2024-2025, the number of long-term care beds per 1,000 Canadians aged 75 and over fell from 66.6 to 63.5 (CIHI, 2025). Over the same window, the population aged 65 and over grew 3.4 percent in a single year, to 8,108,467 people, or 19.5 percent of the national population as of 1 July 2025 (Statistics Canada, September 2025). Neither number is a forecast. Both are measurements of a system under load, and they point in opposite directions. The claim this piece defends, stated early enough to be refuted: Canada’s care capacity gap is not primarily a spending problem or a staffing problem, it is a timing problem. Two independent structural variables are moving toward each other on fixed schedules. The first is demographic and essentially certain: the population aged 85 and over, which was about 1.2 million in 2031 terms in the medium-growth projection, is projected to reach 2.8 million by 2051 (Statistics Canada, January 2025). The second is institutional and equally fixed: the bed stock, the buildings and the licensed facilities that already exist, whose capacity per senior is drifting down rather than up. When a certain wave meets a thinning reservoir, the first casualties are not the residents inside the system. They are the people queued outside it. The four numbers that define the squeeze On paper, Canada’s long-term care footprint looks stable: provinces keep licensing beds, spending keeps rising. In practice, every denominator that matters is moving. The table below assembles the load-bearing indicators, each with its period and its denominator stated, because in this file the denominators are the story. Table 1: Load-bearing indicators of Canada’s long-term care squeeze, latest available periods Indicator Value Period Denominator LTC beds per 1,000 population 75+ 63.5 2024-2025 (2021: 66.6) Licensed LTC beds per 1,000 residents aged 75+ LTC residents aged 85+ 50.0% 2024-2025 All current LTC residents LTC residents with dementia 60% 2024-2025 All current LTC residents Clinically complex residents 24.6% 2024-2025 (2019-20: 22.7%) All current LTC residents LTC spending per capita, 75+ 6,409 CAD 2023 (2016: 5,234, nominal) Nominal spend per person aged 75+ Population 65+ 8,108,467 (19.5%) 1 July 2025 National population estimates Source: CIHI, Health System Context Series, 2025 (no public link); Statistics Canada , population estimates, 24 September 2025 Read the first row against the second and the squeeze acquires its shape. The bed rate is measured against everyone over 75, a group that is itself growing at better than 3 percent a year. Holding the bed count flat while the denominator compounds is arithmetically identical to closing beds, and the recorded fall from 66.6 to 63.5 per 1,000 implies that supply did not even hold flat. Divide the same system a different way and the pressure concentrates: half of the people already inside long-term care are over 85, six in ten have a diagnosed dementia, and the share classified as clinically complex has risen from 22.7 percent to 24.6 percent in five years (CIHI, 2025). The system is not merely full. It is full of people who cost more per bed-day than the residents it was designed around. The spending line shows what that costs and why it does not solve the timing problem. Per-capita long-term care spending on the 75-plus population rose from 5,234 CAD in 2016 to 6,409 CAD in 2023, nominal terms (CIHI, 2025). That is a 22.5 percent increase over seven years, tracked against a consumer price index that rose roughly 18 percent over the same period. Real spending per senior grew, but barely, and it grew against a resident population that is getting older, sicker and more expensive per head faster than the average senior is. Run the standing-still arithmetic forward and the scale of the institutional task appears without any new policy assumption. The 65-plus population grew 3.4 percent in the single year to July 2025 (Statistics Canada, September 2025), and the 75-plus group grows at least as fast in an aging profile. Holding the bed rate flat at 63.5 per 1,000 therefore requires the licensed bed count itself to grow roughly 3 percent a year, which compounds to about a third more beds within a decade, before a single point of the 63.5 rate is recovered. Against the recorded history, in which the rate fell rather than held, the standing-still scenario is already the optimistic branch. The gap between what compounding requires and what licensing has delivered is the numerical core of this analysis. One more feature of the indicator set deserves its own note, because it is the row most often skipped. Some 6.4 percent of long-term care residents are under 65 (CIHI, 2025). Long-term care in Canada is not only an old-age institution; it is also where the system parks high-acuity disability that community care cannot absorb. That cohort does not shrink when the senior wave arrives, which means the beds are shared between a growing 85-plus population and a steady younger caseload. Every percentage point of bed rate lost to demographics is contested between two groups, and only one of them is counted in the aging projections. Variable one: the wave is dated, not hypothetical The demographic side of this analysis is unusually tractable, because the people who will be 85 in 2051 are alive and counted today. Statistics Canada’s medium-growth projection, released in January 2025, puts the population aged 85 and over at about 1.2 million in 2031 and 2.8 million in 2051, a more-than-doubling in twenty years driven by the baby-boom cohorts crossing that threshold (Statistics Canada, January 2025). The same projection family shows the 85-plus share of the senior population itself rising from about 12 percent in the mid-2020s to 21.7 percent by 2046. Canada is not waiting to find out whether the wave arrives. The wave has a schedule. The leading edge is already measurable. As of 1 July 2025, the country counted 12,281 centenarians, against roughly 9,500 at the 2021 census (Statistics Canada, 2025 and 2022). The 85-plus group stood at over 861,000 in the 2021 census, more than double its 2001 count, and has been one of the fastest-growing age groups in every census since (Statistics Canada, 2022). Population aging is often discussed as a slow variable. For institutions with decade-long planning cycles, it is not slow at all: the 2031 doubling window is the same horizon as a hospital rebuild, and the 2051 endpoint is two renewal cycles away. Two properties of this variable matter for the analysis. First, it is independent of policy: no realistic immigration or fertility scenario in the projection family changes the 85-plus count materially before 2040, because those cohorts are already born. The projection document states the point directly in its own vocabulary, that the projections “are not predictions” but planning tools, and in this case the planning tool’s least uncertain row is the oldest one. Second, it is geographically uneven, and uneven in a way that misaligns with capacity. The same projection notes that the demographic weight of Newfoundland and Labrador, Quebec and Yukon declines from 2024 to 2049 in all scenarios (Statistics Canada, January 2025). Declining weight in a projection means aging in place, a population growing older faster than it grows larger, concentrated in provinces with the smallest tax bases to fund care infrastructure. The variable is not just dated. It has an address. Variable two: the reservoir is thinning while it waits The institutional variable is behavioural, which makes it harder to project and easier to misread. The bed rate fell 4.7 percent in four years, from 66.6 to 63.5 per 1,000 seniors over 75 (CIHI, 2025). A fall this size does not require a decision to close beds; it requires only that bed licensing grows more slowly than the 75-plus population, which is what happens when construction cycles, zoning and operating budgets all move at the pace of normal government. In practice, the reservoir is thinning passively, by accretion of the denominator rather than by subtraction from the numerator. What the system is doing instead of building beds is visible in the acuity shift. The clinically complex share of residents rose from 22.7 percent in 2019-2020 to 24.6 percent in 2024-2025, and half of all residents are now over 85 (CIHI, 2025). A common reading is that long-term care is taking harder cases. The structural reading is sharper: as the bed rate falls, admission is increasingly reserved for people who cannot be kept out by any other means, which raises average acuity inside the system and pushes everyone less acute back into the community. The bed rate and the acuity rate are the same phenomenon observed from both sides of the door. The pressure relief valve for that door is home care, and it is already large. The Canadian home healthcare market is estimated at 17.72 billion US dollars in 2025, with aging demand cited as the primary driver (Mordor Intelligence, 2025). Home care is where the system’s arithmetic actually gets decided, because it is the only component that scales without a construction permit. Its constraint is different and harder: it runs on a labour market, not a licence, and its capacity per worker cannot be wired into new buildings the way a charging station can. A gap that closes by hiring must compete for workers with every other part of a health system that is itself aging. The 22.5 percent nominal rise in institutional spending per senior over 2016 to 2023 suggests what happens when a care system tries to buy its way past demography: the money moves, the denominator moves faster. A caution belongs next to the bed-rate series, because the national number is a mix. The 63.5 per 1,000 is an aggregate over provincial systems with different licensing regimes, building stocks and admission rules; a provincial mix shift, in which faster-aging provinces with fewer beds per senior grow their share of the 75-plus population, can move the national rate without a single province closing a bed. The direction of the drift is unlikely to be a pure composition effect, since the 2021 reference point of 66.6 came from the same kind of mix, but the magnitude carries that uncertainty. This is one reason the analysis leans on the acuity and dementia shares, which are measured inside facilities and are harder to move by mixing. Why the two variables cannot rescue each other The analysis needs its two leading indicators to be independent, and they are, for an unglamorous reason. The demographic variable is fixed by births that happened between 1946 and 1965 and by survival rates that are published actuarial inputs; no provincial decision of the next five years alters the 2031 count by more than a rounding error. The institutional variable is fixed by buildings, budgets and labour contracts; no mortality table changes it. A gap whose two sides are driven by disjoint causes does not close by improvement on either side alone, and it cannot be argued away by assuming the two sides will somehow coordinate. That is the structural meaning of a timing problem: the schedule of one side is set by biology and the schedule of the other by procurement. The independence also sets the honest bound on what policy can do. Speeding up bed construction attacks the institutional variable with a lag of five to ten years per project, which means decisions taken now land inside the 2031 window at best. Expanding home care attacks the door-side mechanism immediately but converts a bed-count problem into a wage-bill problem that compounds with the same demographic arithmetic. Neither lever touches the wave. The claim of this piece, that the squeeze is a timing problem, is exactly the claim that makes the policy menu narrow: what is choosable is the order and the buffer, not the schedule. Who gets hit first, and in what order The intersection of the two variables identifies the first casualties without much ambiguity. The first group hit is the over-85 cohort in provinces whose population weight is declining: Newfoundland and Labrador first among them, since aging-in-place there is steepest and the fiscal base smallest. The second group is the under-85 seniors with high acuity who used to qualify for beds and increasingly do not; the clinically complex share tells you how quickly the admission bar is moving. The third group is unpaid, and uncounted in the spending tables: the families absorbing the residents who would have been admitted at a 66.6 bed rate and are instead waiting at a 63.5 one. Home care’s 17.7 billion dollar market estimate measures the paid portion of that absorption. The unpaid portion has no invoice and no ceiling. The order matters because it tells provinces what to watch. If the analysis is right, the first observable stress is not a bed shortage in the aggregate; it is a wait-list and acuity problem at the door of the existing facilities, followed by home-care spending growth outrunning its labour supply. Beds are the wrong early-warning indicator for this system. Queues are the right one. The two variables differ in their leading indicators, and the difference is usable. The demographic variable publishes its own future: the 2031 cohort of over-85s is already counted in today’s 75-to-84 group, so the wave’s size at every point in the next decade is known within a narrow band. The institutional variable has no such schedule, but it leaves a trail in observable series. Provinces that want to see the squeeze before it arrives can watch three things, none of which requires a new statistics programme. The bed rate per 1,000 over-75 in the next CIHI round: a further fall below 63.5 confirms the passive-thinning mechanism; recovery above 66.6 would falsify it. The clinically complex share inside facilities: a continued climb past 24.6 percent means the admission bar is still rising, and community absorption is still deepening. Home-care spending and its workforce: growth in the paid market alongside flat or falling worker supply is the signature of a valve that is opening into a wall. What would prove this analysis wrong The claim is falsifiable on a schedule, and the falsifiers are specific. If the bed rate per 1,000 over-75 turns up in the next CIHI reporting round, above roughly 65, the thinning-reservoir premise weakens and the timing argument loses its second variable. If the clinically complex share plateaus below 25 percent while the bed rate keeps falling, then admissions are not being rationed by acuity and the door-side mechanism described here is misread. If home-care spending growth flattens while the 85-plus population accelerates through 2031, the pressure-relief-valve assumption fails, and the squeeze lands somewhere the two variables used here do not reach. Each falsifier is observable within one or two reporting cycles, which is the standard this kind of projection should be held to. One softer falsifier is worth naming because it would arrive first. The analysis treats the bed rate’s fall as passive, an accretion of the denominator. If a province openly reclassifies or decommissions long-term care beds as part of a home-care-first strategy, the same numerical drift would carry a different meaning: a chosen substitution rather than a squeeze, with different distributional consequences for the families absorbing the difference. The distinction is observable in policy announcements, and it should change how the same 63.5 figure is read, even if it does not change what the figure does to a person waiting at the door. Data basis Data as of November 2026. Population figures (8,108,467 people 65 and over, 19.5 percent of the population, 3.4 percent year-over-year growth; median age 40.6; 12,281 centenarians) are Statistics Canada population estimates as of 1 July 2025, released 24 September 2025. Long-term care indicators (beds per 1,000 population 75+, 63.5 in 2024-2025 against 66.6 in 2021; 50.0 percent of residents aged 85+; 6.4 percent under 65; 60 percent dementia diagnoses; 24.6 percent clinically complex against 22.7 percent in 2019-2020; 6,409 CAD per-capita spending on the 75-plus population in 2023 against 5,234 CAD in 2016, nominal) are from the Canadian Institute for Health Information’s Health System Context Series, 2025. Projections (85-plus population of about 1.2 million in 2031 rising to 2.8 million in 2051, medium-growth scenario; 85-plus share of seniors at 21.7 percent by 2046; declining demographic weight of Newfoundland and Labrador, Quebec and Yukon from 2024 to 2049) are from Statistics Canada’s population projections released 21 January 2025, which are scenario-based and not predictions. The home healthcare market size of 17.72 billion US dollars for 2025 is a market-research estimate (Mordor Intelligence), not official statistics, and is treated here as an estimate throughout. No adjustments are applied to any series; nominal spending is not inflation-corrected beyond the one explicit comparison noted. Limitations CIHI indicators are provincial-system aggregates; provincial mix can shift the national bed rate without any province closing beds. The 85-plus projection is a medium-growth scenario, one of several; the direction is robust to scenario choice, the magnitude is not. The home-care market figure is a commercial estimate with a proprietary methodology, used only as an order of magnitude. Sources Statistics Canada , population estimates for 1 July 2025, 24 September 2025 Statistics Canada , population aging subject page, median age and centenarian data, accessed November 2026 (site home) Statistics Canada , population projections 2024 to 2074, 21 January 2025 CIHI, Health System Context Series, long-term care indicators, 2025 (no public link) Mordor Intelligence , Canada home healthcare market report, 2025 This article was prepared by the expert team at Global Infinity Labs, drawing on insights and data provided through its MCP data services. About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. Email: support@globalinfinitylabs.com
More
What Abu Dhabi Heard When Sam Altman Said One Word About Energy SeaPRwire

What Abu Dhabi Heard When Sam Altman Said One Word About Energy

SeaPRwire – Abu Dhabi, 2 November 2026. The opening ceremony of ADIPEC, the largest energy exhibition in the world, ran a keynote, a signing, and then a speech-and-interview with the chief executive of OpenAI. The exhibit halls outside held 2,260 exhibiting companies from more than 170 countries, and the organizers expected 239,000 visitors across the four days (ADIPEC 2026 opening coverage, November 2026). Inside the plenary, the entire industrial logic of the Gulf was compressed into two speeches. Sultan Al Jaber, the UAE’s industry minister and ADNOC’s group chief executive, told the room that the energy industry must “fundamentally rethink” how it builds, protects and delivers secure energy. Sam Altman told the room that AI is increasingly a platform for discovery, and that its expansion requires significantly more energy. Then someone asked Altman to name the one challenge he faces today. He answered with a single word: “Energy.” That one-word answer is worth more attention than the partnership announcement that preceded it, because it inverts the usual direction of flattery. Technology executives on Gulf stages normally praise the host’s ambition and leave. Altman, standing in the capital of an oil producer, named the commodity on the stage’s home ground as his binding constraint, and then extended the compliment further than protocol required: “I think the UAE has consistently been the most forward-looking country in the world for AI adoption. Going back to the launch of ChatGPT, this is a country that has decided to go all in on AI” (ADIPEC opening, November 2026). The producer and the customer spent a morning telling each other they need each other. This piece sorts what each of them actually said, marks where each is standing when he says it, and asks what the exchange exposes about the next phase of the AI buildout in the Gulf. The pivot both speeches were built on The core argument of the opening was Al Jaber’s, and he performed it as a reversal of a two-year-old question. “Sam, from the moment ChatGPT was born, the world has asked what energy can do for AI. And now, together, we will find out what AI can do for energy” (ADIPEC opening, November 2026). The line repositions an oil company from supplier to user. It landed moments after the announcement that ADNOC, with the Abu Dhabi technology group G42, will become the first energy company to deploy OpenAI Frontier, applying advanced AI systems to oilfield development, well management and commercial operations (Energy Connects, November 2026). The question “what can AI do for energy” is not rhetorical in Abu Dhabi this year; it has a contract attached. Al Jaber’s supporting argument ran on operational language rather than vision language. “AI must be built in, not bolted on,” he said. “In a crisis, the speed of insight and the speed of decision-making is the difference between continuity and disruption.” He anchored the urgency in the year’s supply shocks, telling the room that since the disruption in the Strait of Hormuz, nearly one billion barrels of crude have been drained from inventories. His five-step programme for the industry, from expanded strategic storage to what he called operational intelligence, ended on people rather than machines: “Systems don’t carry responsibility, people do.” Notice what the speaker is selling at each of those moments. Al Jaber is a minister of an OPEC producer and the chief executive of the national oil company, opening an event his company hosts, announcing a deal his company signed. His argument, that resilience is a product and Abu Dhabi is its supplier, is addressed to buyers of energy security. The AI clause is the newest item in an old catalogue. Where Altman stood when the answer got short Altman’s section of the morning was framed as a speech and interview, and his position is easier to state than his host’s: he is the buyer. Every efficiency he described redounds to his own cost structure. “We’re going to make more efficient models. We’re going to have robots that can make chip fabs more efficient and assemble racks for us,” he said, before delivering the sentence that framed the day: “We can bring down the cost of delivering great AI in almost every way, except, you know, atoms are still atoms, and the physical world that has to power this. That’s going to be, I think, the very dominant factor of the cost and the abundance and how much we can create” (Energy Connects, November 2026). The single-word answer sits inside that logic. Asked for his one challenge, “Energy,” is not a compliment to the host country; it is a cost line. The numbers behind the cost line came from outside the room, and the opening coverage quoted them directly: the International Energy Agency reported in April 2026 that data centres used about 485 terawatt-hours of electricity in 2025, up 17 percent on the year, and that consumption would roughly double to about 950 terawatt-hours by 2030, around 3 percent of global demand. Capital spending by the five largest technology companies passed 400 billion US dollars in 2025 and is expected to rise by a further 75 percent in 2026 (IEA via Energy Connects, November 2026). When the buyer of 485 terawatt-hours stands on an oil stage and names his constraint in one word, the compliment that matters is not the one he speaks; it is the constraint he names. Altman also supplied the reciprocity clause the host wanted, and marked its own position as speculation rather than fact: AI is “increasingly being used not just as a productivity tool, but as a platform for scientific discovery,” with potential to transform energy operations, materials development and system design. The same IEA report, run as the sceptical control, says existing AI applications could save more than 13 exajoules of energy by 2035, about 3 percent of global final energy consumption, by monitoring grids and equipment. The buyer’s hope and the agency’s estimate agree in direction. Neither is a delivered saving. The minister two seats away from the deal The UAE’s energy and infrastructure minister, Suhail Al Mazrouei, carried the state’s position onto the opening ministerial panel, and his formulation is the one to watch because it binds AI to spare capacity rather than to software. “We need to build additional layers of protection to ensure we have enough resilience and spare capacity. All of this will require technology, and we will need AI to design better and become more resilient” (Energy Connects, November 2026). Where Al Jaber sells resilience as a product, Al Mazrouei budgets for it as inventory. The distinction matters because a country that treats AI as an input to spare capacity will buy different systems, and accept different latencies, than a company that treats AI as a trading tool. The state’s AI deployment record gives the rhetoric a measurable base. Microsoft’s global diffusion tracking put UAE AI adoption at 73.3 percent of respondents in the second quarter of 2026, the highest reading it records, on a sequence that ran 59.4, 64.0, 70.1 and then 73.3 percent across four quarters (Microsoft, September 2026). The federal government reported around 35,000 public-sector Copilot users in 2026, and the federal AI architecture sets a target of 50 percent of government services running through AI agents. In September 2026 the emirate of Ajman put into service a proactive public-service model in which AI agents renew licences across departments before they expire (The Arabian Post, September 2026). The Gulf state that Altman called the most forward-looking adopter is, by its own published counters, already running its bureaucracy on the technology his company sells. Table 1: Speakers at the ADIPEC 2026 opening, what each is standing on, and the quote that carries it Speaker Position of interest What the quote is doing Sultan Al Jaber UAE industry minister; ADNOC group CEO; host of ADIPEC Sells resilience as a product: “Energy leadership is not measured by what you produce in good times. It is measured by what you deliver in hard times.” Sam Altman CEO of OpenAI; buyer of energy and compute Names his own cost line: “Energy.” Then: “atoms are still atoms.” Suhail Al Mazrouei UAE energy and infrastructure minister Converts AI into inventory: resilience and spare capacity “will require technology” IEA (April 2026 report, quoted in coverage) International agency; supplies the demand curve Supplies the denominators: 485 TWh in 2025, about 950 TWh by 2030 Source: Energy Connects , Gulf Fire , compiled November 2026 The year that made resilience the product The opening’s urgency has a dated source, and the speakers repeated it often enough to count as the event’s second theme. Al Jaber told the room that since the disruption in the Strait of Hormuz, “nearly one billion barrels of crude have been drained from inventories”, and built his five-step programme on top of that number: accessible supply through expanded strategic storage, routes to market with infrastructure “built before it is needed”, operational intelligence, capital policy, and people. The line that carried the argument was aimed past the hall at every buyer of Gulf barrels: “Energy leadership is not measured by what you produce in good times. It is measured by what you deliver in hard times. We cannot control every situation. We cannot remove every risk, but we can decide what is there to meet it.” A year earlier, at the opening of ADIPEC 2025, the same speaker had urged the industry to focus on “data, not drama” and framed the debate as “energy addition” rather than replacement (Energy Connects, November 2026). The shift between the two openings is measurable in vocabulary. In 2025 the industry debated how much supply to add. In 2026 it debated how to keep supply moving through disruption, and the technology programme followed the debate: the organisers report use cases across reservoir modelling, autonomous operations, infrastructure inspection and robotic systems, with an AI Zone among the four specialised areas and Asia participation at its strongest level, including pavilions from China, India, Malaysia, Singapore and South Korea (official opening-day release, 2 November 2026). The operators on the following CEO panel confirmed the pivot from their side of the table. Richard Jackson, president and chief executive of Oxy, put it in accounting language rather than engineering language: “For us, having gone through these shocks, our strategy has been durability. We talk a lot about resilience, but within our team, we think about durability over time. We have focused on sustainable cash flow and production, and we have taken advantage of the opportunity to invest in more durable production.” A chief executive who defines resilience as sustainable cash flow will buy AI the way he buys any other cost reducer, and that is the buyer psychology the ADNOC-OpenAI announcement was designed for. Al Jaber’s “built in, not bolted on” is, read against Jackson’s sentence, a sales specification: resilience that arrives as a subscription rather than as capital expenditure. What 73.3 percent measures, and what it does not The number that made Abu Dhabi the natural venue for this conversation deserves its own position annotation, because it too is standing somewhere. Microsoft’s diffusion tracking put UAE AI adoption at 73.3 percent in the second quarter of 2026, the highest national reading in its series, after a sequence of 59.4, 64.0, 70.1 and 73.3 percent across four quarters (Microsoft, September 2026). The measure counts people, not machines: it is the share of surveyed respondents reporting AI use, which makes it a diffusion reading, not a deployment inventory. A country can be first on that measure with a consumer base that prompts chatbots on phones, and the number alone does not say which. The deployment inventory is thinner and more concrete. Around 35,000 public-sector users were reported on Copilot in 2026, the federal AI architecture targets a 50 percent share of government services running through AI agents, and Ajman’s September 2026 deployment put cross-department licence renewals into the hands of agents that act before expiry, the first case in the region where the agent’s action precedes the citizen’s form (The Arabian Post, September 2026). Set the three counters against the diffusion reading and the gap between them is the honest map: adoption of 73.3 percent, agent penetration targets of 50 percent, and one flagship deployment that actually closes a loop without human initiation. The first number is why the world calls the UAE an AI leader. The third number is why the claim is currently a claim about direction rather than depth. The same gap runs through the event’s economics. The IEA numbers quoted in the opening coverage give the demand curve, 485 terawatt-hours for data centres in 2025 rising to about 950 by 2030, and the savings curve, a potential 13 exajoules by 2035. The UAE’s purchases sit on the first curve today. Its five-step plan and its agent targets are bets on the second. Both curves were quoted in the same session; only one of them has a procurement office behind it. What nobody on the stage was asked The opening ceremony’s question list had visible gaps, and each gap sits exactly where an interviewer would have had to choose between hosts and guests. No one asked what the OpenAI Frontier deployment costs, who pays for the power it consumes, or whether the model runs on grid electricity that the Gulf’s own demand forecasts show tightening as data-centre load doubles globally by 2030. No one asked Al Jaber to reconcile “AI must be built in” with the five-step resilience plan’s first two items, strategic storage and routes to market, which are capital projects with decade-long lead times that no model accelerates. No one asked Altman whether the UAE’s adoption figures, impressive on the diffusion survey, convert into productivity at the federal scale the 35,000-user deployment implies, or how a 50 percent AI-agent target in government services will be audited. The emissions question was also absent, in a year when the IEA report quoted at the same event counts AI both as a demand source and as a potential saver of 13 exajoules by 2035. An opening session that quotes the demand half of that sentence and leaves the savings half to a paragraph is not hiding anything; it is scheduling. The savings estimate has no contract attached. The demand number does. What the exchange actually exposed Strip the ceremony and one structural fact remains, and it is the fact both speeches were arranged to serve. The Gulf’s AI story has moved from ambition to procurement. A national oil company signed to be the first energy company on OpenAI Frontier; a federal architecture targets a 50 percent AI-agent share of services; an emirate runs cross-department licence renewals through agents that act before a human files a form. The 73.3 percent diffusion reading is the demand-side proof the sellers needed, and it is why the producer’s stage welcomed the buyer of compute with a headline deal rather than a panel discussion. What the buyer gave the producer is subtler. Altman’s “atoms are still atoms” concedes, in the buyer’s own vocabulary, that the binding constraint on his industry now sits in the physical world his hosts own. The partnership reads, on that reading, less like a technology transfer and more like a toll agreement: the company that needs power and the country that sells it have agreed to find out whether the models can pay for the barrels. The excitement Altman expressed, that he is “tremendously excited for AI to help enable the energy industry,” reads differently once his cost answer is on the table; the enabling runs in both directions, and only one of the two directions has a meter. “And now, together, we will find out what AI can do for energy” is, in the end, a research question with a revenue model attached, posed in a hall where 40 ministers were listed among the attendees. Whether the answer arrives as productivity in the oilfield or as another line on the demand curve is the question the next ADIPEC will be asked. Sourcing note Data as of November 2026. This piece is an organised reading of one event: the opening ceremony of ADIPEC 2026 in Abu Dhabi on 2 November 2026. Primary quotes are taken from three near-contemporaneous accounts of the same session, the Energy Connects feature of 3 November 2026, the Gulf Fire reproduction of the official opening-day release dated 2 November 2026, and the TahawulTech reproduction of the same release; where the accounts differ in wording, the fuller version is quoted and no wording is altered. Speaker positions are annotated from public roles: Sultan Al Jaber is the UAE Minister of Industry and Advanced Technology and ADNOC managing director and group CEO; Sam Altman is CEO of OpenAI; Suhail Al Mazrouei is the UAE Minister of Energy and Infrastructure. Event statistics (239,000 expected visitors, 2,260 exhibitors, more than 40 ministers, more than 1,800 speakers across more than 380 sessions, 30 country pavilions) come from the official opening-day release. UAE adoption figures (73.3 percent in Q2 2026 with the four-quarter sequence; about 35,000 federal Copilot users; the 50 percent AI-agent target) come from Microsoft’s diffusion report of 21 September 2026 and UAE federal materials held in the track knowledge base; the Ajman case is dated 25 September 2026. Session duration is not published in the sources, so the exchange is characterised as a speech and interview per the official release, not as a timed conversation. Sources Energy Connects , AI is a necessity for energy industry, not just an option, 3 November 2026 Gulf Fire , HE Dr Sultan Al Jaber and Sam Altman highlight energy, AI and investment priorities at ADIPEC 2026 opening, 2 November 2026 TahawulTech , Dr Sultan Al Jaber, Sam Altman highlight energy, AI and investment priorities at ADIPEC 2026 opening, 2 November 2026 Microsoft , The continued state of global AI diffusion in 2026, 21 September 2026 The Arabian Post , UAE broadens AI deployment across essential public services, 25 September 2026 This article was prepared by the expert team at Global Infinity Labs, drawing on insights and data provided through its MCP data services. About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. Email: support@globalinfinitylabs.com
More
Hong Kong’s EV Ledger: Three Ratios That Do Not Mean the Same Thing SeaPRwire

Hong Kong’s EV Ledger: Three Ratios That Do Not Mean the Same Thing

AsiaPresswire – Hong Kong published a statistic in 2025 that sounds like the end of the combustion era: roughly seven out of every ten newly registered private cars in the city are electric, a figure the government repeated in a Legislative Council paper that September. In the same year, the same government recorded that electric vehicles make up about 16.3 percent of all vehicles on the road. Both statements are accurate. Both come from the Transport Department’s own registration data. And neither one means what a casual reader assumes it means, because the two sentences are computed over different denominators, different vehicle classes, and different months. The distance between 71 percent and 16 percent is not a contradiction. It is the gap between a flow and a stock, and in Hong Kong’s transport policy that gap is doing a great deal of quiet work. What is usually called EV adoption in Hong Kong is really three different ratios wearing one label. The first ratio counts decisions: of the private cars newly registered in a period, what share is electric. The second counts inventory: of the private cars, or of all vehicles, on the road at a date, what share is electric. The third counts infrastructure: of the parking spaces, or of the chargers, how many can serve an EV. Hong Kong’s 2025 and 2026 transport documents quote all three. The distinction between them matters because the first ratio is already past 70 percent, the second is between 16 and 20 percent depending on the denominator, and the third, on the public-charger definition that matters most for taxis and ride-hailing, is a few orders of magnitude away from either. Policy sells itself on the first number. Drivers live inside the other two. The flow ratio, checked against the raw tables The claim that opens nearly every Hong Kong EV story is quoted verbatim here, from the government’s own paper to the Environmental Affairs Panel dated 29 September 2025: “The percentage of electric private cars among newly registered private cars has risen significantly, from 6.3% in 2019 to 70.6% in August 2025. In other words, approximately seven out of every 10 newly registered private cars are now electric.” The denominator in that sentence is private car first registrations in the reference period. It excludes motorcycles, taxis, goods vehicles and buses, which are counted separately and electrify far more slowly. The full-year tables behind that claim are published in the Transport Department’s replies to the 2026-27 Estimates questions, and they let anyone recompute the ratio rather than inherit it (Transport Department, 2026). The table below assembles the three most recent years for private cars. Table 1: First-registered private cars in Hong Kong by fuel type, 2023 to 2025 (units, calendar years) Year Electric private cars All private cars EV share of flow 2023 28,541 44,169 64.6% 2024 33,206 46,709 71.1% 2025 37,467 51,035 73.4% Source: Transport Department , replies to Legislative Council Estimates questions 2026-27 Recomputed from the raw counts, the flow ratio was 64.6 percent in 2023, 71.1 percent in 2024, and 73.4 percent in 2025. The headline “seven out of ten” was true when written in September 2025 and had become conservative by December. What the same table shows in the rows outside the private-car band is a second fleet electrifying at a different speed entirely. The 18,163 taxis that the Transport Department counts as the city’s point-to-point backbone, 15,250 urban, 2,838 New Territories and 75 Lantau, renew slowly enough that their fuel mix moves by percentage points per year, not by tens of percent (Transport Department taxi page, accessed November 2026). The flow ratio’s smooth climb is a property of one vehicle class. The ledger’s other columns, and the other fleets, are a different table. The flow ratio also carries a policy lever inside it that the raw numbers make visible. Since 2021 the government’s stated goal has been to cease new registrations of fuel-propelled and hybrid private cars in 2035 or earlier (Hong Kong EV Roadmap, March 2021). A flow ratio above 70 percent makes that goal look close to self-executing: if three quarters of new private cars are already electric, the last quarter follows in a few renewal cycles. That inference is where the first ratio starts flattering the second. The stock ratios, and what each denominator hides The inventory numbers are the ones a driver actually experiences, and they are quoted in two different versions. In August 2025, the government’s panel paper stated that the total number of EVs in Hong Kong exceeded 131,000, of which approximately 129,000 were private cars, “nine times the figure from six years ago, accounting for 20% of the total private car population” (Legislative Council Panel on Environmental Affairs, 2025). In December 2025, a market report compiled from official registration statistics put the city’s EV count at about 149,000 vehicles, “16.3% of all vehicles” (Jwview via China News Service, February 2026). Both statements are defensible. They are not the same claim. The 20 percent is computed over the private car population only. The 16.3 percent is computed over all registered vehicles, a pool that includes motorcycles, taxis, light buses, goods vehicles and buses, roughly 270,000 vehicles by the arithmetic of the two published stock claims themselves, and most of the non-private fleet runs on diesel, petrol or liquefied petroleum gas. The two numerators differ by roughly 18,000, because they are taken four months apart. Run the arithmetic backwards and each stock claim quietly reveals the size of its own denominator: 129,000 private EVs at 20 percent implies a private car fleet near 645,000 at the end of August 2025, while 149,000 EVs at 16.3 percent implies a total fleet near 914,000 at the end of December 2025. The private car fleet is therefore about seven in ten of all registered vehicles, which is consistent, and which is precisely why the two percentages look so different while describing one fleet. Neither stock figure supports the sentence most often built on top of them, that Hong Kong is “already electric.” At 20 percent of private cars and 16.3 percent of the full fleet, more than four in five registered vehicles still run on liquid fuel, and the conversion of the stock happens at the pace of the renewal cycle, not at the pace of the flow ratio. The honest projection is mechanical: even if the flow holds at 73 percent, and even if every newly electric private car replaces an old petrol car one for one, lifting the private stock from 20 percent to a majority takes on the order of a decade of normal replacement. The 2035 registration stop applies to the flow. The road fills up on the stock’s clock. What the chargers are counted in Infrastructure numbers arrive with their own denominator problem, and the government’s own paper supplies both sides of it. Hong Kong has “around 120,000 parking spaces equipped with charging infrastructure”, of which “approximately 14,500 are public charging facilities, about three times the figure in 2021”, and the target is to raise total spaces with charging from about 120,000 to about 200,000 by mid-2027, an increase of over 66 percent (Legislative Council Panel on Environmental Affairs, 2025). Three different units sit inside that paragraph. A “parking space with charging infrastructure” mostly means a residential or commercial bay wired for slow overnight charging, counted because the 2020 gross floor area concession pushed developers to pre-wire new buildings. A “public charging facility” means a charger a stranger can use, and 14,500 of them serve roughly 149,000 EVs citywide, about one public charger per ten electric vehicles as of late 2025. The mid-2027 target of 200,000 extends the first unit, the wired bays, whose growth is nearly automatic in new building stock, rather than the second, whose growth requires kerbside space, power upgrades and commercial operators. Read the target as a charger count and it looks like a plan for drivers without private parking. Read it correctly, as a plan for wired bays, and it mostly ratifies construction that was already mandated. The distinction matters most for the vehicles that cannot charge overnight at home. The same panel paper concedes the point in its own logic: for electric taxis, “their operational models necessitate a more extensive network of quick and even fast public chargers” (Legislative Council Panel, 2025). The taxi and ride-hailing fleets are therefore asked to run on the 14,500, not the 120,000, against an 18,163-vehicle taxi fleet that renews on the trade’s schedule rather than the buyer’s. Which of the two charging counts a policy sentence chooses tells you which fleet it was written for. The cap that has no published denominator The fourth number in Hong Kong’s mobility ledger is not about vehicles at all; it is about permission. The Road Traffic (Amendment) (Ride-hailing Service) Ordinance was passed by the Legislative Council in October 2025, and on 26 May 2026 the government gazetted four pieces of subsidiary legislation to operate it, including a notice that “specifies the limit on the number of vehicle permits that may be issued – at the current stage, the Government proposes capping the number of permits at 10,000” (news.gov.hk, May 2026). The regime requires platforms, vehicles and drivers each to hold a licence or permit, binds driver to vehicle, restricts permits to cars under 12 years old, and introduces a combined driving test for taxis and ride-hailing vehicles. Platform licences cost HK$16,250 to apply for and HK$1,200,000 per year to hold, and the application window closed at noon on 30 October 2026 (Transport Department ride-hailing page, 2026). The government’s stated rationale is arithmetic of its own kind: “With the busy traffic in Hong Kong and the fact that nearly 90% of the public rely on public transportation for their daily journeys, the Government needs to impose an overall control on the number of ride-hailing vehicles” (Transport and Logistics Bureau, May 2026). The cap, the bureau said, was set “based on the data collected from a survey administered by the Transport Department” on demand for personalised point-to-point transport services. Here is the number group that cannot be cross-checked, and the distinction matters because it is the only load-bearing figure in the ledger with no visible denominator. The 10,000 permit cap is presented as the output of a survey, but neither the gazetted notice nor the accompanying press releases publish the survey’s estimate of current ride-hailing activity, its sample, or its definition of demand. Every other ratio in this ledger, the flow share, the stock share, the charger counts, can be recomputed from published tables. The one number that reallocates earning rights between taxi licence holders and platform drivers rests on a survey whose baseline is internal. Set against the taxi fleet, which the Transport Department fixes at 18,163 licensed vehicles, a 10,000 permit cap is a deliberate decision to keep the regulated ride-hailing fleet at roughly half the size of the taxi fleet, whatever the demand survey said. That may be the right call for road space. It is not a finding of the survey; it is a policy choice wearing the survey as a citation. The subsidy ledger and the 3,000 taxis it paid for The gap between the private-car ledger and the fleet ledger is not unmanaged. It is subsidised. In December 2024 the government published the Green Transformation Roadmap of Public Buses and Taxis, and committed to “subsidising franchised bus operators and the taxi trade to procure approximately 600 electric buses and 3,000 electric taxis” (Legislative Council Panel on Environmental Affairs, 2025). Set the two numbers side by side with the registration data and a ratio emerges that no launch speech quotes. The private-car flow crossed 70 percent without a purchase subsidy aimed at the vehicle itself, pushed mainly by the “one-for-one” first registration tax concession that rebates buyers who scrap an old petrol car while buying electric (Jwview, February 2026). The taxi trade, whose economics run through daily hire and whose charging needs the panel paper itself flags as exceptional, was offered a procurement subsidy sized at 3,000 vehicles, about one in six of the licensed taxi fleet, spread over a multi-year window. The distinction between these two instruments is where the audit instinct pays. A tax concession works on the flow: every buyer who was already shopping in a given year meets a lower price at the moment of choice, and the flow ratio responds within months, which is what 64.6 to 73.4 percent across 2023-2025 shows. A procurement subsidy works on the stock: it retires and replaces specific vehicles on the operators’ schedule, and its effect is bounded by how many vehicles the trade agrees to turn over. Hong Kong has chosen the flow instrument for the fleet it does not need to persuade and the stock instrument for the fleet it does. The registration table confirms which choice moved faster. Nothing in the table is inconsistent; the design just is what it is. The same asymmetry runs through the charging build-out. The wired-bay target of 200,000 spaces by mid-2027 is, in effect, the flow instrument applied to infrastructure: new buildings pre-wire by rule, and the number rises with construction. Quick and fast public chargers, the stock instrument that taxis and ride-hailing vehicles actually need, require kerbside space and grid upgrades that no construction schedule delivers automatically. One per ten EVs is the ratio the fleet runs on until that second ledger moves, and it is the ratio to watch when the 2027 target comes due, because 200,000 wired bays will arrive on time while the fleet’s charger count will have had to be earned. Where the ledger actually balances Assembled on one page, Hong Kong’s EV and ride-hailing numbers do not contain an arithmetic error. They contain a systematic order of presentation. The flow ratio, 73.4 percent of new private cars in 2025, is the number that opens speeches. The stock ratio, 16.3 percent of all vehicles at end-2025, is the number that closes appendices. The charger count splits into a flattering aggregate, 120,000 wired spaces, and a functional one, 14,500 public chargers, one per ten EVs. The ride-hailing cap of 10,000 cites a survey whose denominator stays in a drawer. Each individual document is accurate. The incompatibility lives in the gap between what is counted, what is quoted, and what is published, and the pattern repeats: every figure that grows fast is a flow or an aggregate, and every figure that describes the lived city is a stock or a permission. The distinction also marks where the next three years get decided. If the private-car flow stays above 70 percent, the 2035 flow stop arrives on schedule without further policy. The binding constraints are the other two ledgers: public charging for the fleets that cannot charge at home, and the 10,000 permits, whose number the bureau has promised to review dynamically against licensed platforms’ operating data. Those are the ratios to watch in the 2027 estimates round, because they are the ones the city’s own tables can check. There is one more reason to watch the permits rather than the percentages. The flow ratio, however impressive, was substantially produced by a price signal, the “one-for-one” first registration tax concession that rebates buyers who scrap an old petrol car while buying electric, and a price signal moves a flow without touching a stock. The permit cap works in the opposite direction: it is a hard number with a renewal cycle, an age limit of 12 years on permitted vehicles, and a combined driving test that funnels new entrants through the same gate as taxi drivers. When the bureau says it will monitor “licensed platforms’ operational data” and adjust, the ledger’s most consequential line item is a promise to revisit a denominator that has never been shown. Hong Kong’s electric decade will be booked in flows, but it will be lived in stocks and permits, and only one of those three is published in full. Methodology Data as of November 2026. Data source: four primary documents, the Transport Department’s replies to the 2026-27 Estimates questions (first registration tables by fuel type, 2023-2025), the Legislative Council Panel on Environmental Affairs paper of 29 September 2025, the gazette notice and press releases of 26 May 2026 on ride-hailing legislation, and the Transport Department’s taxi and ride-hailing pages. Metric definition: the “flow ratio” is electric first-registered private cars divided by all first-registered private cars in a calendar year; the “stock ratio” is EVs registered at a date divided by the private car population or the total vehicle population, as labelled. Denominators are stated in the text at each use. Time points: flows cover calendar years 2023 to 2025; stocks are as at end-August 2025 and end-December 2025. Computation: shares in Table 1 are recomputed from published counts, and the fleet sizes of about 645,000 private cars and 914,000 total vehicles are back-solved from the two published stock claims. No adjustments: no seasonality, de-trending or annualisation is applied. Excluded: hybrids are counted under their fuel types per the department’s note, and derived fleet sizes carry the rounding of the published percentages, so they are approximations. Cross-check: the two stock claims were tested for mutual consistency through the implied fleet sizes. Limitations The December 2025 stock figure comes from a compiled market report citing official statistics, one step of secondary sourcing. The ride-hailing demand survey’s baseline is unpublished, so the 10,000 cap can be described but not independently recomputed. Derived fleet sizes inherit rounding error from the published percentages. Sources Transport Department , Replies to Legislative Council Estimates Questions 2026-27, first registration tables Legislative Council Panel on Environmental Affairs , Electric Vehicle Charging Network discussion paper, 29 September 2025 news.gov.hk , Ride-hailing laws gazetted, 26 May 2026 Transport Department , Ride-hailing service licensing information, application window closed 30 October 2026 Transport Department , taxi fleet composition, 18,163 licensed taxis, accessed November 2026 Jwview , mainland EV brands in Hong Kong with official registration statistics, February 2026 This article was prepared by the expert team at Global Infinity Labs, drawing on insights and data provided through its MCP data services. About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. Email: support@globalinfinitylabs.com
More