CZ Blames “Policy Blindness”: The Shanghai Freeze Exposes Solana’s Risk Miscalculation

(SeaPRwire) -By: Ethan Gallagher The postponement of Solana’s Shanghai summit on October 16 was not a simple scheduling glitch. It was a tactical stumble. The presence of law enforcement at the venue turned the morning sessions into a standstill. Attendees waited outside for over an hour. No replacement time has been confirmed. This hesitation signals a deeper disconnect between the project’s expansion playbook and the regulatory reality on the ground. The network’s push into China is hitting a wall of bureaucratic friction that marketing cannot outpace. The official narrative remains opaque. Organizers cited logistics without confirming police orders to close the event. Attendees reported eight or nine officers on site. The Solana Foundation has not provided a public statement addressing these reports directly. The agenda included talks on internet capital markets by Lily Liu, President of the Foundation. An Alibaba Qwen team representative was slated to discuss AI tools. Sessions on robotics and enterprise systems were also scheduled. These topics bridge cryptocurrency with traditional tech. They suggest a strategy to dilute the crypto label. Yet, the physical disruption at the venue overshadowed all digital programming. The subtext is a repeat failure of local intelligence. Changpeng Zhao, co-founder of Binance, noted on October 16 that Solana likely did not understand local policies. He referenced a previous incident in Shenzhen in October 2025. During that event, police conducted on-site inquiries. Organizers then blamed canceled hackathons on crowding and safety. Zhao’s critique is sharp. He had praised Solana’s Shanghai office the day before. The shift from praise to questioning highlights the volatility of the China market. Solana’s online attention share reached 16.74% this week. High visibility attracts regulatory scrutiny. The team is operating in a grey zone that requires constant legal calibration, which they apparently lacked for this stop. The hardware landscape does not care about brand optics. China’s February 2026 rules prohibit virtual currency trading and related financial activities. Officials have not cited these rules for the Shanghai shutdown. The remaining stops in Hangzhou, Shenzhen, and Beijing remain on the calendar for October 18, 20, and 22. The Alpenglow network upgrade is scheduled for October 21. Developers expect it to reduce transaction confirmation times. The 200-millisecond block move is a technical win. But it cannot solve the geopolitical deadlock. If the next three cities face similar friction, the tour will collapse. The supply chain for trust is broken. Until the legal team aligns with local enforcement, the hardware speed is irrelevant. Author bio: Ethan Gallagher, a Silicon Valley Hardware Architect and Infrastructure Strategist who specializes in analyzing the intersection of decentralized networks and regional regulatory frameworks.
More
BlackRock’s $68 Billion Toll Road: The Crypto ETF Fee War Everyone Else Is Losing Business

BlackRock’s $68 Billion Toll Road: The Crypto ETF Fee War Everyone Else Is Losing

(SeaPRwire) - By: Logan Pierce BlackRock's iShares Bitcoin Trust holds $68.67 billion. That's four times the next-largest fund in the category. IBIT alone commands over 61 percent of all Bitcoin ETF assets. The entire crypto ETF market sits at $124.77 billion across 32 active funds managed by 11 issuers. Bitcoin ETFs capture 77.9 percent of that total. Ethereum takes 18.9 percent. The rest goes to Solana and XRP products. The gap between IBIT and Fidelity's FBTC is $53 billion. That's not a competitive market. That's a toll road. Grayscale's Bitcoin Trust ETF holds $10.56 billion. Its 1.50 percent expense ratio is the highest among spot Bitcoin products. Investors fled. Grayscale launched the Bitcoin Mini Trust at 0.15 percent. It now holds $5.42 billion. Bitwise's BITB charges 0.20 percent and holds $3.24 billion. ARK 21Shares' ARKB charges 0.21 percent and holds $2.87 billion. VanEck's HODL currently sits at 0.00 percent thanks to a fee waiver, with a standard rate of 0.20 percent. ProShares' BITO, the only futures-based product in the top tier, holds $1.71 billion at 0.95 percent. The top seven Bitcoin ETFs together hold more than $110 billion. Over the past 30 days, IBIT attracted $1.47 billion in net inflows. Fidelity's FBTC added $357.92 million. ARKB shed $224.28 million. BITB lost $60.43 million. GBTC lost $193.53 million. The 35 tracked funds generated roughly $143 million in 24-hour trading volume. ETFs now hold approximately 8.80 percent of the combined market cap of all crypto assets they track. That includes 1.28 million Bitcoin, roughly 6.1 percent of the total 21 million BTC supply. ETFs also hold 5.9 million Ethereum. The market grew from near zero in early 2024 to over $100 billion within two years. BlackRock dominates Ethereum just as hard. ETHA holds $8.61 billion, equal to 36.5 percent of the entire ETH ETF market. That fund alone controls 3.53 million ETH. Grayscale operates two Ethereum products. The Ethereum Staking Mini at 0.15 percent holds $2.20 billion. The older ETHE charges a staggering 2.50 percent, the highest fee in the entire crypto ETF space, and holds $1.83 billion. Fidelity's FETH holds $1.37 billion at 0.25 percent. Bitwise's ETHW sits at approximately $279 million. The Ethereum market totals $23.59 billion, a fraction of Bitcoin's $97.18 billion. Solana ETFs hold $2.27 billion. XRP ETFs hold $1.72 billion. Three additional Hong Kong-listed funds have data still being compiled. Spot ETFs hold the bulk of AUM, while futures-based funds account for a smaller share. The market spans products listed in both the United States and Hong Kong. Expense ratios range from 0.15 percent to 2.50 percent. That spread tells you everything about the consolidation pattern. Winners collect volume. Losers get squeezed into niche roles or exit entirely. Grayscale's mini products prove the playbook. Match the fee or lose the book. Every crypto ETF manager who doesn't drop below 0.20 percent within the next twelve months is building a bridge with no deck. Author bio: Logan Pierce, an independent business researcher and corporate governance writer specializing in market consolidation, fee structures, and competitive moat dynamics for Medium and independent financial newsletters across global markets.
More

TSMC Just Posted Its Best Quarter Ever and Wall Street Shrugged — That Should Terrify You More Than Any Miss

(SeaPRwire) - By: Lucas Caldwell A company prints a 69% profit jump, guides for 58% growth, and the stock drops 2%. That is not a contradiction. That is the market telling you the TSMC story is already fully priced, fully owned, and one macro headline away from a crowded exit. Thursday's close at $422.25, down $7.75, came on a day when Nvidia slid 2% and Broadcom slipped 1%. Nobody was selling TSMC's numbers. They were selling the entire chip complex because a hot inflation print revived rate-hike fear. When your stock trades as a macro proxy instead of a company, fundamentals become background noise. The numbers themselves were absurd. Sixth consecutive record quarter. Profit of NT$763.1 billion, up nearly 69%. Revenue of NT$1.49 trillion, up roughly 50%. In dollar terms, $4.60 per share on $46.72 billion in revenue, beating FactSet estimates of $4.46 and $45.67 billion. Gross margin came in at 66.4%, down from 67.7% in the second quarter, with fourth-quarter guidance of 65% to 67%. Q4 revenue is guided to $52.3 billion to $54.3 billion, about 58% year-over-year growth. CEO C.C. Wei called leading-edge demand "extremely robust" and pointed to agentic AI as the driver. Now the forward picture. Management expects 44% revenue growth in 2026, slightly above consensus. They also signaled AI accelerator revenue could outrun the current mid- to high-50s CAGR guide. CFO Wendell Huang held the 2026 capital budget at $60 billion to $64 billion, but the real tell was his comment that 2026-to-2028 spending should be far above the past three years. Needham's Charles Shi raised his target to $560 from $530 and kept a Buy, calling it a beat-and-raise quarter. The stock is still up more than 41% this year and touched record highs this month. Here is the game underneath the game. TSMC is the only foundry on earth that can actually fulfill the AI order book, and every major customer knows it. That monopoly on execution is why the AI accelerator CAGR keeps getting revised upward. But it also concentrates systemic risk in one company, one island, one supply chain. The margin dip from 67.7% to 66.4% looks trivial until you realize overseas fabs structurally dilute profitability. Arizona, and whatever comes next, will cost more per wafer than Tainan ever will. Wei can talk about robust demand all day. The gross margin line tells the quieter truth about geographic expansion. Then there is the Texas wildcard. The recent run to record highs followed Elon Musk's comments about early talks on his Terafab chip project in Texas. TSMC confirmed it is exploring the state, and Wei said teams are there doing evaluations, naming Terafab directly as a customer trying to build a fab. Read that carefully. TSMC is entertaining a role in a project that could eventually compete with its own customers' ambitions, while already stretched across Arizona and evaluating more US sites. Every dollar of that $60-plus billion budget is a bet on where geopolitics lets them build, not just where demand is. The next twelve months will decide whether TSMC is a company being valued or a hostage being traded. Author bio: Lucas Caldwell is a tech opinion leader with millions of followers on X/Twitter, known for sharp semiconductor market analysis, earnings-season breakdowns, and blunt commentary on the AI hardware supply chain.
More

The $5 Million Lesson: Why Gemini’s Legal Surrender Cannot Be Unwritten

(SeaPRwire) -By: Julian Holbrooke The courtroom drama played out in plain sight, yet the legal reality remains stubbornly opaque. A federal judge in New York has effectively slammed the door on a joint plea by the Commodity Futures Trading Commission and the crypto exchange Gemini. They wanted to undo a $5 million settlement entered in January 2025. The move was bizarre. The regulator was asking the court to reverse its own enforcement stance while admitting internal flaws. The outcome is clear. The money stays paid. The injunction holds. This is not a victory for market freedom. It is a reminder that procedural finality outweighs political shifts in federal judicial eyes. The official narrative offered by the CFTC was one of self-correction. In May, the agency joined Gemini’s request to cancel the court order. It cited an internal review that questioned the reliability of a whistleblower. It alleged that investigators had withheld evidence from a commissioner before the lawsuit began. The agency argued the case no longer met its current standards. Former acting chair Caroline Pham noted the regulator’s authority over crypto trading under federal law. This framing suggested a desire to clean house and realign enforcement priorities. The public statement on X served as a signal to the industry that the agency was shedding its old, aggressive posture. The subtext, however, reveals a collision of timing and leverage. Judge Alvin Hellerstein ruled that neither the alleged problems in the investigation nor the shifts in Washington justified reopening the case. The critical fact is simple. Gemini paid the penalty before seeking relief. The judge found that documents obtained later did not change the facts as they existed at the time of the settlement. The court rejected the claim that President Donald Trump’s crypto policies created a legal reason to cancel the order. Gemini had accepted the agreement voluntarily after nearly three years of litigation. The permanent ban on misleading statements to the CFTC remains in effect. The regulator has proposed new rules for event contracts. But it will not enforce the clause barring public denials of settlement findings. This creates a strange legal limbo. The order is binding, yet partially dormant in practice. The geopolitical pendulum in US crypto regulation is swinging toward deregulation, but the judiciary is not keeping pace. The CFTC’s failure to recover the $5 million is not just a financial loss. It is a strategic one. It signals that agencies can retreat from their own precedents, but they cannot erase the procedural history once a settlement is signed. For Gemini, the expansion into prediction markets through its Titan platform now operates under a cloud of unresolved legal overhang. The injunction limits how the company interacts with regulators. Industry peers are watching. The warning is clear. In the current transitional political landscape, judicial finality is the only stable constant. Companies that rely on regulatory goodwill to unwind past liabilities are walking into a trap that no amount of political reshuffling can break. Author bio: Julian Holbrooke, an overseas international relations analyst who frequently contributes to major European daily newspapers, specializing in the intersection of judicial proceedings and state regulatory power.
More

The Carbon Composite Trap: Why Rocket Lab’s Neutron Delay Exposes a Critical Manufacturing Blind Spot

(SeaPRwire) - By: Reginald Vance Rocket Lab’s decision to push the Neutron launch to 2027 wasn’t a surprise to anyone tracking the supply chain. It was a necessary correction. The market reaction, an 11% drop, reflects a panic driven by investor fatigue, not fundamental reality. CEO Peter Beck admits the company found errors in the production process. Specifically, defects in the stage one propellant domes. This is a hardware failure, not a software bug. You cannot code your way out of a manufacturing defect in a carbon composite structure. The stock fell because the narrative of "speed" collided with the physics of "reliability." Beck’s quote about balancing speed with reliability is standard PR language. The subtext is that they rushed the production line and paid the price in time. The delay to 2027 is not just a timeline slip; it is a reset of the entire value proposition. The official release states that KeyBanc analyst Michael Leshock noted the defects are fixed. However, the subtext lies in the financial implications. Leshock cut his 2027 revenue estimate by $53 million. This number represents one fewer revenue-generating launch. Why only one? Because the new timeline compresses the deployment window. The company plans to finish two key production steps this year. The third is expected in Q1 2027. This is a tight squeeze. The "world’s largest carbon composite rocket" claim hangs on the viability of the material process. If the domes fail, the rocket fails. The market sees a delay. The industry sees a potential pivot in material science validation. The 11% drop is a repricing of risk, not a vote of no confidence in the tech. Rocket Lab sits nearly 70% below its May record. The stock is down close to 25% this year. Wall Street holds a Strong Buy consensus with an average price target of $100.25. This implies about 82% upside. Why the disconnect? The Street is pricing in a successful 2027 launch. Leshock expects a Q2 2027 start, though Q1 is possible. The "High-growth space stocks" valuation drop mentioned by KeyBanc is a red herring. The real issue is hardware scaling. Neutron is the bridge between the small Electron and the heavy lift class. If Neutron fails to scale cadence, the entire vertical integration model stalls. The 53 million dollar cut is small, but it signals a slowdown in cash generation during the critical burn phase. The hardware vendor consolidation endgame favors those who can fix manufacturing defects without stopping the line. Rocket Lab just stopped the line. The supply chain landscape shifts toward those who prioritize yield over speed. Any investor chasing the 82% upside must understand that they are buying into a bet on carbon fiber curing cycles, not just launch windows. The market is wrong to panic. The market is right to be cautious. Hardware delays are the only permanent delays in tech. Author bio: Reginald Vance, a venture partner specializing in semiconductor valuation and advanced materials.
More

Quantinuum Just Got Called the Top Quantum Pick. The $62 Target Tells a Darker Story.

(SeaPRwire) - By: Fiona MacIntyre Quantinuum shares jumped 11% to $36.68 on Thursday. The Nasdaq was under pressure. The S&P 500 was slightly lower. So the move was company-specific. Investing.com reported a 4.5% gain in pre-open trading. Morgan Stanley upgraded the stock to Overweight from Equal-Weight. It installed Quantinuum as the bank's top quantum play. Then it cut the price target. From $78 down to $62. Let that sink in. An 11% rally, fueled by a note that lowered the target by more than 20%. The market is not celebrating the stock. It is ranking the sector's relative horror. Quantinuum just smells the least burnt. Analyst Joseph Moore calls it a compelling entry point. He argues the company leads its peers on technology and execution. It carries the lowest valuation multiple against 2030 revenue projections. In a sector with no real earnings, the lowest multiple is not a value signal. It is a confidence verdict. The analysts note the market is least confident in Quantinuum. The gap between their view and the market's view is far larger for this stock than for its rivals. Shares had been loitering near a 52-week low of $33.02. The June IPO was an industry first. It could not hold its momentum. That is a sector with a burn-rate problem. Not a healthy market shrugging off a good stock. The technical record partially justifies the call. Helios shipped 48 error-corrected logical qubits at its late 2025 launch. That number is published, testable, and genuinely first. Moore credits the published results for offering clarity when rivals make inflated claims. Now look at IonQ. It closed Thursday at $34.35. Morgan Stanley trimmed its target from $49 to $43. That still implies roughly 25% upside. The bank says IonQ has the strongest outside validation of its scaling plan. But it trails Quantinuum on technology. IonQ has not shown it can repeat earlier error-correction results on Superion, its newest machine. It bought SkyWater Technology for a manufacturing edge. A chip fab is not a qubit result. The roadmap gap is where the sector's anxiety lives. Quantinuum's Sol system is due in 2027. Apollo follows in 2029. Logical qubits must climb from 48 into the hundreds. CEO Rajeeb Hazra told Barron's the company builds on an architecture. It does not restart with each generation. That is the right philosophy. Every added qubit multiplies calibration complexity and control hardware demands. Forty-eight is a proof point. Hundreds is a promise. Now follow the capital. Insiders bought roughly $24.7 million of QNT over the past year. Zero reported selling. That is the only unambiguously bullish data point in this coverage group. Morgan Stanley now rates Quantinuum as its sole Buy-rated quantum stock. IonQ, Infleqtion, and Xanadu all sit at Equal-Weight. Infleqtion rose 4% to $9.48, but the bank doubts its roadmap. A next-generation system in 2027 could help, if it lands on time. Xanadu gained 5% to $3.34. Morgan Stanley sketches a range from $1 to $9. It flags fresh funding needs. That is a polite way of saying capital depletion risk. The bank projects a $10 billion quantum market by 2030. It sees $100 billion by 2040. Quantinuum is expected to grab the largest revenue share. Those projections hinge on Sol shipping on schedule. Apollo delay is the named risk. Consider the consolidation endgame. The first player to reach hundreds of logical qubits locks in the patent moat. It also locks in pricing power and institutional contracts. IonQ owns manufacturing edge, not technical proof. Xanadu is watching its runway. Infleqtion needs a schedule miracle. Quantinuum has insider conviction, published results, and a bank's endorsement. The market still prices it near a 52-week low. Thursday's 11% pop did not settle that argument. It just postponed the margin call. The $62 target sits far above today's $36.68. The data says one thing. The tape says another. Only Sol, and the timing of Apollo, will write the final verdict. Author bio: Fiona MacIntyre, an independent physics researcher and consultant for emerging compute hardware clusters.
More

Nvidia’s Supply Chain Is So Fragile Taiwan Is Building the Fix in Texas

(SeaPRwire) - By: Reginald Vance Nvidia locked in $279 billion in supply commitments for the quarter ending July 26. That figure more than doubles the $119 billion it committed in Q1. When a company nearly triples its supply lock-in in a single quarter, that's not procurement growth. That's panic math. The numbers tell you exactly what Jensen Huang's team saw. High-bandwidth memory remains the single constraint on AI hardware throughput. TrendForce reported in June that Nvidia's planned low-power DRAM supply for its Vera Rubin platform covers only about 60% of projected demand. Forty percent of a flagship platform's memory roadmap sits unallocated at the component level. That's not a gap. That's a structural failure waiting for a revenue cycle to expose it. Every hyperscaler from Microsoft to Meta is competing for the same scarce wafers. Nvidia's supply commitment surge tells you they've stopped trying to negotiate allocations and started pre-buying entire production runs regardless of pricing. Supply commitment growth at that rate usually precedes a pricing reset downstream. Customers who signed two-year contracts last year are now watching component costs climb while their contract lock-ins expire. The stock dropped about 2% on Friday when the Texas industrial park news broke. TSMC fell roughly the same amount. The market read the headline as dilution. The market missed the subtext. This isn't about building factories. This is about a supply chain so fragile that a $4 billion government backstop became the only way to keep the long tail of vendors from fragmenting. The mechanics of Taiwan's plan are deceptively simple. Economy Minister Kung Ming-hsin laid out the structure on October 12. Taiwan will build several U.S. industrial parks targeting AI hardware suppliers. Each complex can absorb up to $4 billion in investment. The first site lands in Texas, with a projected cost range between $2 billion and $4 billion. The Taiwan Electrical and Electronic Manufacturers' Association will coordinate capital raising. The government will provide loan guarantees. A dedicated team will handle local and federal regulatory navigation and permitting. That regulatory layer matters more than it looks. Every small component maker that needs to break ground in the U.S. faces a permit process that can stretch eighteen months in some jurisdictions. A government-backed fast-track team compresses that timeline materially. The loan guarantees also shift credit risk. A supplier that can't secure commercial financing for a $50 million assembly line can now anchor a credit rating against sovereign backing. That changes the balance sheet equation entirely for firms operating at thin margins. TSMC has already pledged $265 billion for American expansion. Foxconn and Wistron are independently adding U.S. production capacity to meet surging AI demand. These firms fund their own migration. They don't need a government backstop. The parks exist for everyone else. Jensen Huang named dozens of specialized parts makers during a Taipei speech earlier this year. Connectors. Thermal interfaces. Precision molds. PCB manufacturers. These are the vendors whose geographic concentration in Northern Taiwan creates single-point-of-failure risk. If those firms can't or won't relocate to the U.S., the parks become the minimum viable infrastructure for keeping AI hardware production on schedule. If they don't participate, the parks become expensive empty lots waiting for mandates. The $4 billion per-site number is a red herring. It covers construction, permits, and basic facility setup. It doesn't address the actual bottleneck. HBM production still depends on advanced packaging nodes controlled by a handful of foundries. DRAM supply still runs through memory makers whose capacity is fully allocated through 2026. The parks solve a geography problem. They don't solve a yield problem. What they do solve is the political question that Taiwan faces in every quarterly trade review with Washington. Investment commitments under the trade deal are a stated requirement. Lowering geopolitical exposure tied to mainland tensions is a parallel objective. The parks operationalize both goals simultaneously. But the endgame is vendor consolidation. Right now, the AI hardware supply chain is a hybrid network. Taiwan-based component makers feed into U.S.-assembled products. That model is efficient but fragile. The parks create a pathway to bifurcate that network. Eventually, some suppliers will operate parallel production lines in both Taiwan and the U.S. Others will fully relocate. Still others will be priced out of the global AI supply chain entirely and lost to non-competitive local markets. TSMC and Foxconn can afford the bifurcation. Their cash flow supports dual-site operations without margin destruction. The smaller vendors cannot. Their only path to remaining in the chain is government financing. Which means Taiwan's industrial parks aren't just supply chain infrastructure. They're the difference between staying in the game and being written off as a legacy vendor. The decision to build these parks signals that the government of Taiwan has already determined that waiting for market-driven relocation is no longer viable. The margin compression cycle started years ago. Every additional quarter of inaction widens the competitive gap between dual-site vendors and single-site ones. $4 billion per park sounds substantial until you divide it across dozens of qualifying suppliers and subtract permitting costs, labor training, and technology transfer expenses. The net capital available per vendor is modest. And modest is a dangerous word in a market where supply commitments are measured in the hundreds of billions. A supplier that can't deploy meaningful capex within eighteen months of landing a site will find themselves locked out of the next Nvidia procurement cycle. Those cycles don't wait. The real trigger behind this move isn't opportunity. It's the arithmetic of exclusion. Texas is where the first slice of that exclusion gets built. The remaining slices will follow wherever the regulatory pressure lands next. Author bio: Reginald Vance, a venture partner specializing in semiconductor valuation and advanced materials, with over fifteen years advising on capital allocation across the global chip manufacturing supply chain.
More

MSCI Just Redrew the Line Between a Company and a Vault — and Michael Saylor Is on the Wrong Side of It

(SeaPRwire) -By: Adrian Kingsley Index providers were supposed to be referees, not rule-writers with an agenda. Yet MSCI's decision on Thursday to adopt its "non-operating companies" methodology crosses that line in a way that deserves cold scrutiny. The mechanics sound technical. Companies get screened on operating assets and five financial ratios. Fail at least four of the five tests, and you are out of the Global Investable Market Indexes. But the intent is plain. This is a filter built to catch crypto treasury firms, and Strategy (MSTR) is the biggest fish in the net. Metaplanet and Upexi were previously named for deletion under the same method. A May 2026 simulation also flagged Yellow Cake. When an index provider starts deciding what counts as a "real" business, it stops measuring the market and starts shaping it. Look at the official facts first. The rules take effect with the November index review. They replace interim limits that targeted companies holding digital assets worth at least 50% of total assets. MSCI will publish its final removal list on Nov. 11, with removals set for Nov. 30, 2026. The design includes deliberate buffers. Companies not yet in the index cannot be added if they fail the screen in either of their two most recent annual filing periods. Current members must fail in both periods before removal. MSCI may also use the most recent interim filing if one is available. SharpLink (SBET), Ton Strategy (TONX), Solana Company (HSDT) and DeFi Development (DFDV) land on a watchlist, which is not a removal but a loaded warning. Now the real social and market impact. Removal forces funds tracking MSCI indexes to sell. That pressures prices and drains passive demand. JPMorgan analysts earlier estimated roughly $2.8 billion in selling if Strategy is cut, though that figure concerned MSCI's earlier digital asset proposal, not the rules adopted Thursday. Strategy's own numbers frame the scale differently. In August, the company said funds tracking MSCI indexes hold about 13 million of its shares, or 3.1% of basic shares outstanding, less than one day of trading volume. Michael Saylor and CEO Phong Le called the plan "discriminatory." Conner Brown of the Bitcoin Policy Institute put the objection sharply in September, arguing broad index exclusion "removes a company from the default portfolios of tens of millions of people who never chose to remove it." Strategy, meanwhile, recently added 250 Bitcoin, bringing holdings to 848,250 BTC. The company insists the move "would have no meaningful impact" on its business, while warning it harms MSCI's reputation as a neutral provider. Governance by methodology is still governance. MSCI has built itself a lever that reclassifies an entire corporate category out of mainstream capital access, and other index providers will now face pressure to follow or to differentiate. Treasury-style bitcoin firms will adapt by restructuring toward operating revenue, or they will accept exile from passive flows and price their shares accordingly. Either way, the precedent stands: the gatekeepers of benchmarks have claimed the power to define what a company is, and that power will not stay limited to crypto. Author bio: Adrian Kingsley is an internationally renowned scholar who has long studied public administration and social policy, with a focus on how regulatory classification reshapes markets and institutional behavior.
More
The $292 Million ETH Long Wipeout: One Level Separates a Bounce From a Bloodbath Business

The $292 Million ETH Long Wipeout: One Level Separates a Bounce From a Bloodbath

(SeaPRwire) - By: Lucas Caldwell The loudest noise in crypto right now isn't a new narrative. It's the sound of leveraged longs being forced out. Ethereum fell to $2,375, down 1.93 percent in a single day. Roughly $292 million in ETH positions were liquidated within 24 hours. Ninety-two percent of that was long side. This isn't a routine pullback. It's a margin squeeze that caught the aggressive side of the market flat-footed. Hotter CPI ignited it. September CPI printed 3.7 percent against a 3.6 percent forecast. Risk assets wobbled, and ETH carried the heaviest forced selling. Spot Ethereum ETFs recorded a $129.5 million net outflow on October 14. BlackRock clients accounted for $109.8 million of that. Blockto data shows spot exchange volume hasn't recovered since the 2025 all-time high. It's now the lowest it's been. Thin sell waves move price further. The bid-side depth is shrinking precisely when it's needed most. The derivatives side isn't helping. CoinGlass open interest data shows positions grew sharply in August and stayed high through September. October's pullback has been draining them. Leverage built up on the way to $2,800 is now unwinding into diminishing liquidity. Ted Pillows tracked a whale position worth $92.17 million. It was long with 14x leverage. At one point, the position sat just $64 from full liquidation. Another update showed ETH sweeping $2,315, the top of the weekly bull market support band. It then ran to $2,450, up 3.6 percent. RSI bounced from 34 to 41. About $11.4 million in shorts were liquidated on OKX, against just $1.2 million in longs. MVRV stands at 1.06. ETF demand remains the weak link. The short squeeze doesn't change the bigger picture. Buyers defended the low, but they haven't taken back control yet. Open interest grew sharply in August and stayed elevated through September. October's pullback has been draining it. Derivative positioning is unwinding, and spot volume is thin. Here's the uncomfortable part. The price action now lives or dies based on how many leveraged traders bleed out before dip buyers step in. ETF flows are negative. Institutional demand isn't catching the knife yet. South Korea's stock market circuit breaker added to the pressure. Traders moved out of risk assets. Ethereum absorbed the heaviest forced selling. The setup looks fragile from a flows perspective. Price is bouncing, but the foundation is still shaky. Vitalik's labeled wallet holds roughly $530 million, almost all in ETH. That's a statement of conviction, but it doesn't change short-term flow math. The next resistance sits at $2,394. Reclaim it, and $2,500 opens up. Daily close below $2,315? $2,140 becomes the magnet. The support at $2,141.59 has marked turning points since 2024. Bulls need a convincing reclaim of $2,394 to end the flush. RSI sits at 39.44, below its average of 47.85. OBV of 34.73 million shows buying pressure hasn't recovered. Even after the bounce, momentum is weak. The market needs volume, not just leveraged short covering. When the spot bid is this thin and the leverage wipeout has already taken $292 million out of ETH longs in a single day, with ETF money still walking out the door and a whale long sitting dangerously close to liquidation before inflation data forced the market to reprice, the path of least resistance points back toward $2,141 unless $2,394 is reclaimed with actual volume rather than short covering, and that is the only signal worth trading right now, so ignore the noise and watch that level. Author bio: Lucas Caldwell, a tech opinion leader with millions of followers on X/Twitter, specializing in crypto market microstructure, liquidation flows, and institutional capital movement.
More

Mastercard Just Swallowed Stablecoins Whole — and Visa Should Be Nervous

(SeaPRwire) -By: Logan Pierce Forget the press release language about "interoperability." What Mastercard actually did on October 15 is buy its way into the stablecoin settlement layer and flip it into a distribution product. The Global Money Platform is not an experiment. It is the first real yield from the BVNK acquisition closed in August, a deal valued at up to $1.8 billion including contingent payments. When a card network spends that kind of money and ships a flagship product within roughly two months, the message is simple. Stablecoins are no longer a crypto sideshow. They are now plumbing, and Mastercard intends to own the pipes. Here is what the platform actually delivers, stripped of the marketing gloss. Banks, fintechs, and enterprises get accounts holding both fiat and stablecoins through a single API. They can convert between the two in real time. They can issue payment cards linked to stablecoin balances in more than 130 countries. Holders can spend those balances at hundreds of millions of merchant locations without manually converting anything first. The backend hooks into Mastercard Move, the company's money transfer network, which reaches more than 17 billion endpoints including bank accounts and cards. Stablecoins go in, local currency lands in a recipient's bank account. The partner list tells you where the demand actually sits. Nuvei, Marqeta, Ontop, Beem, and Almond FinTech are among the first integrators. These are payment processors, card issuers, and payroll platforms, not crypto casinos. That matters. Ontop's presence signals cross-border payroll use cases, where stablecoins solve a genuine pain point around settlement speed and correspondent banking fees. Mastercard is positioning itself as white-label infrastructure. Financial firms can offer stablecoin services under their own brands while Mastercard collects the network tolls underneath. BVNK co-founder Chris Harmse framed it as connecting his firm's technology to Mastercard's "scale and trust," which is exactly the deal logic. Now the competitive geometry. Visa launched its own platform in July, letting financial institutions hold, mint, and transfer stablecoins. Visa moved first on issuance. Mastercard's counterpunch is distribution, spending cards in 130-plus countries and payouts through Move. These are two different attack angles on the same market. Visa wants to be where stablecoins are born. Mastercard wants to be where they are spent and cashed out. Raj Dhamodharan, Mastercard's EVP of blockchain and digital assets, says commerce will be built on interoperability across multiple forms of money. Translation: whichever network abstracts away the fiat-versus-crypto distinction wins the flow. The demand signal is real but uneven, and honesty requires saying so. Standard Chartered research shows stablecoin transaction activity is growing, yet circulating supplies of USDt and USDC have stayed relatively flat this year. Velocity is rising faster than supply, meaning existing tokens are being used more intensively rather than new money flooding in. Mastercard's roadmap is ambitious regardless. Move coverage is expected to expand beyond 40 currencies to more than 200 countries and territories by 2027. Tokenized deposits are on the horizon. So is commerce executed by autonomous AI agents, which is where stablecoin rails become genuinely strategic rather than merely convenient. The first network to make a stablecoin balance indistinguishable from a checking account in the eyes of a merchant will quietly reprice the entire cross-border payments industry, and Mastercard just bought itself the best seat at that table. Author bio: Logan Pierce, an independent business researcher and corporate governance writer on Medium, covering payments infrastructure, fintech consolidation, and the mechanics of platform monopolies.
More
XRP’s $1.32 Floor Is Barely Holding: What The PPI Shock And Dying ETF Flows Actually Mean Business

XRP’s $1.32 Floor Is Barely Holding: What The PPI Shock And Dying ETF Flows Actually Mean

(SeaPRwire) - By: Lucas Caldwell XRP got chewed up by a hotter-than-expected PPI report and then somehow clawed back from six percent losses to re-test $1.34. That bounce off $1.32 happened fast enough to look like panic buying. It probably was. The broader crypto market dumped over three days and liquidated $1.7 billion in positions while Bitcoin slid below $81,000 and Ethereum broke under $2,400. XRP just refused to join the collapse entirely. That refusal is either conviction or confusion. The PPI came in at 1.3 percent monthly against a 0.5 percent forecast. Core PPI hit 0.7 percent versus a 0.3 percent read. Both followed a CPI print that also missed to the upside. Higher energy costs pushed wholesale prices further than anyone priced in. Traders who had bet on easing inflation got squeezed. More than $100 million in short positions evaporated in twelve hours once the reversal kicked in. XRP held above $1.32 and traded at $1.34 on October 16, up roughly 2.18 percent from the lows. XRP ETF inflows tell a quieter story that matters more long-term. Net inflows hit just $13 million in October. At a simple run rate that projects about $26 million for the full month, which is a 79 percent drop from September. Bitwise added $10.55 million. Franklin Templeton's XRPZ pulled in $4.1 million. Canary Capital's XRPC saw $3.34 million in outflows. Cumulative inflows sit at $1.80 billion with net assets of $1.51 billion. The weekly inflow streak is now at 13 weeks. The momentum is flatlining. On-chain data from Santiment shows exchange inflows spiked between September 10 and September 27 and have since declined. Holders stopped routing tokens to exchanges to sell. That reduction in sell pressure is one reason the $1.32 level held. Ali Charts flagged $1.25 as the likely buying zone if price retests the lower boundary of the hourly parallel channel. A bounce from there could target $1.42 at the midpoint or $1.60 at the upper boundary. The daily chart shows strong buying volume appeared exactly at $1.32. That level has been key support for weeks. A four-hour close below $1.30 would open the door to $1.25. Price needs to clear $1.45 on the four-hour to confirm a reversal. The RSI sat at 32.82, deep in oversold territory. The MACD line remained below its signal line. The structure is fragile but not broken. If the Fed keeps rates higher for longer because inflation is proving stickier than expected, XRP will keep grinding against macro headwinds until ETF demand catches up with the price. Right now it is not. $1.25 is the real test. Hold that and $1.45 breaks and the channel play works. Lose that support and the whole setup resets.
More

Wall Street Just Walked Into a $9 Billion Door That Never Closed — And Ripple Is Selling the Key

(SeaPRwire) -By: Christian Pierce Institutional traders have been stuck. They need exposure to stocks, commodities, and currencies around the clock. Traditional markets shut down at 5 p.m. and again on weekends. Crypto never sleeps. The gap between the two worlds has been a structural frustration for hedge funds for years. Ripple just bridged it. Ripple Prime announced real-world asset perpetual swaps tied to Trade.xyz perpetual futures on Hyperliquid. The product covers more than 100 reference markets across equities, equity indices, ETFs, metals, energy, and foreign exchange. Trading and settlement run 24/7, including weekends. Clients can post Ripple’s RLUSD stablecoin as collateral. The product is offered through Ripple Prime’s CIV BVI license. Market maker Virtu is already trading the swaps. Michael Higgins, Ripple Prime’s international CEO, described it as the convergence point of traditional finance and decentralized finance. Scotte Moegling, head of business development for digital assets at Virtu, cited cross-margining as the practical pull. Open interest in RWA perpetual contracts reached $9 billion over the past year, according to Bloomberg. Trade.xyz is the largest HIP-3 deployer on Hyperliquid. Ripple Prime itself was built after Ripple completed its $1.25 billion acquisition of prime broker Hidden Road last year. The platform consolidates digital assets, foreign exchange, fixed income, derivatives, and swaps under one account. Ripple Prime added Hyperliquid support in February, which first gave institutional clients access to the decentralized derivatives venue with cross-asset margin. Earlier this year, Ripple also launched a Delta One business for total return swaps on U.S. stocks, indices, and crypto. The commercial loop is straightforward. Institutions already held margin inside Ripple Prime from other positions. Adding RWA perp swaps means less new collateral, faster execution, and continuous exposure without market closures. The real question is not whether this works. It is who controls the flow next. Ripple Prime is laying claim to the institutional gateway between on-chain perpetuals and off-chain asset risk. Hidden Road gave the plumbing. Hyperliquid gave the execution layer. The $9 billion open interest is the proof of demand. Author bio: Christian Pierce is a chief financial columnist and markets commentator with two decades of coverage spanning institutional prime brokerage, digital asset infrastructure, and cross-border derivatives regulation.
More
$80,000 Was Never a Floor. Bitcoin’s $82K Bounce Just Exposed the Market’s Fragile Foundation Business

$80,000 Was Never a Floor. Bitcoin’s $82K Bounce Just Exposed the Market’s Fragile Foundation

(SeaPRwire) - By: Lucas Caldwell The market just got slapped awake by a number nobody wanted to see. September PPI came in at 6.3% year-over-year when analysts had penciled in 5.3%. Monthly gain of 1.3%, the biggest since March 2022. Bitcoin sliced below $80,000 before half of crypto Twitter could refresh their feeds. But here's the part everyone missed. The bounce back to $82,000 looked like strength on the chart. It wasn't. Spot buyers ghosted the entire session. This was a short squeeze dressed in recovery clothing. Leverage doesn't build infrastructure, and pretending otherwise is how positions get liquidated at the worst possible time. The market thinks it's recovering, but it's just leveraged noise pretending to be conviction. Let's strip the narrative and look at what actually hit the tape. The Bureau of Labor Statistics reported September PPI up 1.3% from August, with the annual rate hitting 6.3%, blowing past the 5.3% consensus. Core PPI landed at 5% versus 4.4% expected. This followed Wednesday's CPI print of 3.7%, stacking inflation pressure back-to-back. Energy was the culprit, responsible for over 80% of goods price gains. Energy prices surged 10.8%, gasoline spiked 20.3%. Services climbed 0.8%, but excluding food, energy, and trade services, the underlying number was only 0.5%. The gap between headline and core is where markets get hurt, and Bitcoin is paying that tax right now. The Fed doesn't get a free pass here. The liquidation carnage tells the real story of this market. Bitcoin first dropped roughly $4,000 after PPI and CPI data hit, wiping out over $800 million in long positions in a single move. Then, just as bears celebrated, BTC snapped back to $82,000, triggering $50 million in short liquidations within 60 minutes. The CME FedWatch tool pegged October rate hike probability at 34%. Reuters put it around 30%. Treasury yields actually fell despite the hot data, which Robin Brooks from Goldman Sachs noted has become decoupled from macro metrics as markets obsess over the federal deficit. The yield curve is lying, and Bitcoin traders are trading off the wrong signal. Rate hikes are being priced in, but not deeply enough. The analyst consensus is telling but deeply divided. Ted Pillows called out that the $79,700 to $82,300 bounce was almost entirely short squeeze fuel with spot buyers completely absent from the order book. He flagged $81,200 as the daily close level that must hold. A break of $83,700 with real spot demand would give the rally legs. Rekt Capital sees Bitcoin potentially retesting the 21-week EMA at $76,144 and the 50-week EMA at $78,459 while maintaining its bullish trend, noting such dips are normal in early bull markets. But calling a dump into EMAs "normal" is exactly how traders stop paying attention to what spot flow is actually telling you. The technicals look fine on a daily chart. The reality on the book is uglier. Here's where it gets uncomfortable for the bulls. Aksel Kibar argued last week's close near $83,700 lacked the conviction to qualify as a genuine breakout. His rectangle pattern invalidation sits at $75,000. Meanwhile, Bitcoin remains trapped below the $82,500 to $82,800 support zone. The weekly chart shows price above both EMAs but without a bullish crossover yet. The one-hour chart caught the lowest level since September 18 before the rebound. Every structural level is being watched on charts. But the real question is whether this market has genuine underlying demand or just leveraged noise creating false signals. The market keeps testing these lines, but nobody is stepping in with real money to defend them. That's the problem. When energy inflation keeps running ahead of Fed tolerance and spot buyers refuse to commit capital, $75,000 is not a support level, it's an invitation. Author bio: Lucas Caldwell, a tech opinion leader with millions of followers on X/Twitter, covering crypto markets, macro-driven asset dynamics, and on-chain data analysis for a decade.
More
The AI Trading Scam Is Dead. Long Live The AI Trading Scam. Business

The AI Trading Scam Is Dead. Long Live The AI Trading Scam.

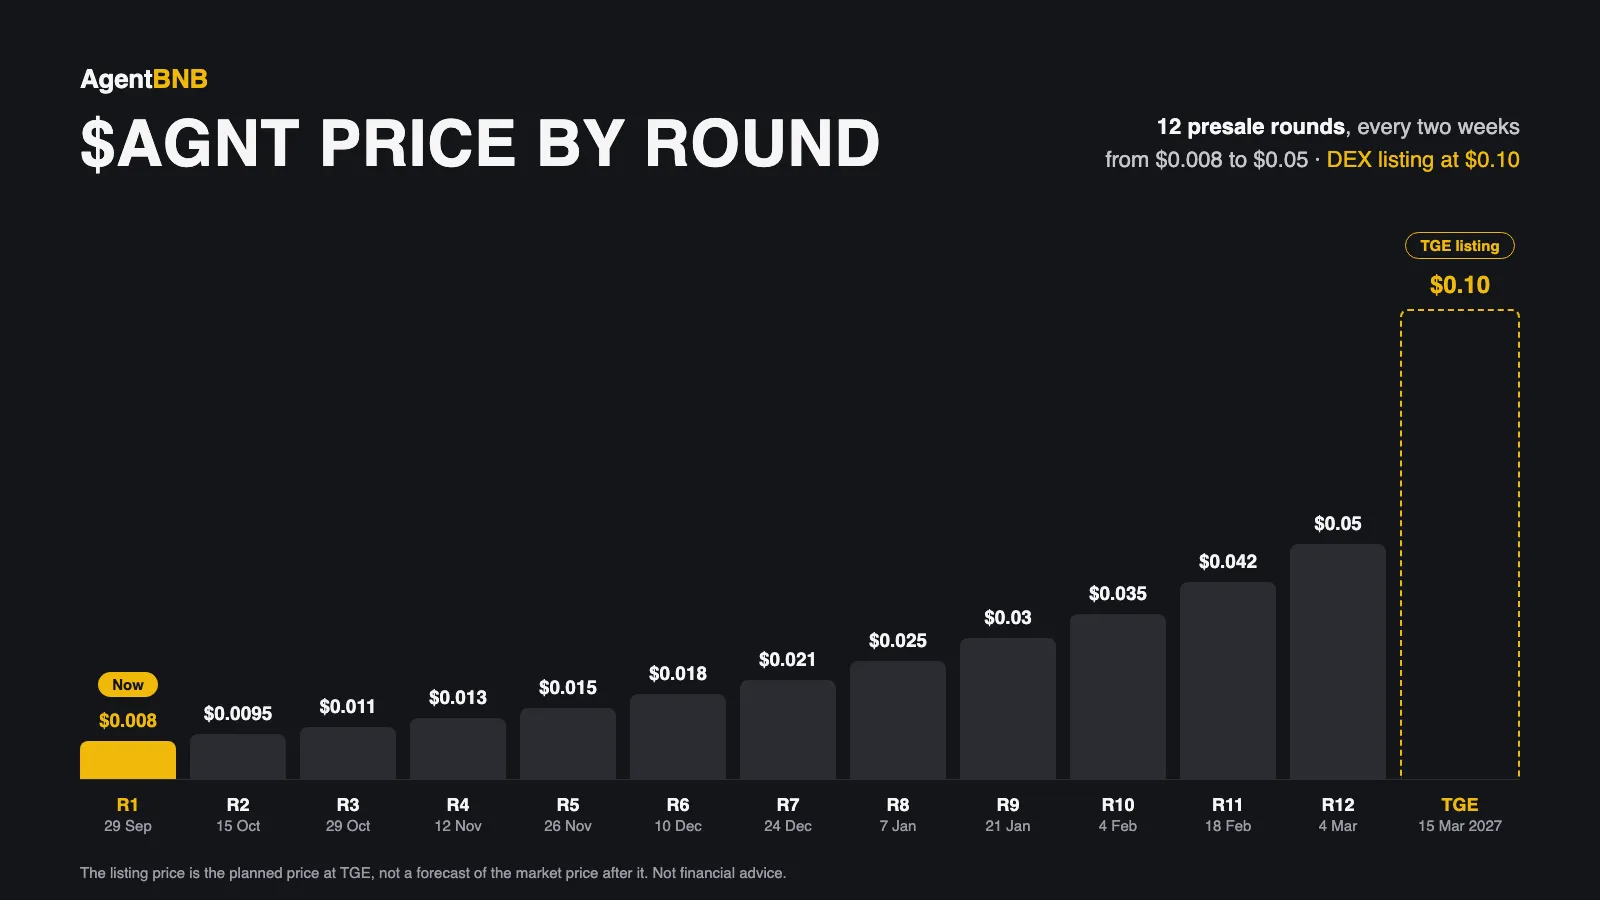
(SeaPRwire) - By: Nathaniel Cross Crypto has swallowed an absurd volume of so-called AI projects this year. Most of them are repackaged bots wearing a fresh coat of LLM marketing. The real innovation in AgentBNB is not that it adds intelligence to trading. It is that the intelligence is deliberately shackled. The constraint itself is the product. Nobody likes handing custody to an algorithm they cannot audit. A contract that refuses trades that violate your written mandate is the closest thing to genuine oversight we have seen in this space. The architecture splits cleanly along custody lines. Every user deploys an ERC-4337 smart account on BNB Chain. The owner key remains in the user wallet. The agent only receives a session key with narrowly scoped permissions. The Mandate Compiler converts plain-language instructions like stop losses and position caps into a formal policy that lives on-chain. The Policy Guard checks every proposed execution against that signed policy. Trades that fit the mandate proceed. Trades that do not are reverted and logged. The Execution and Refusal Log publishes both outcomes publicly, so a losing trade and a dishonest one look different in the records. Nothing executes before the user signs. The platform cannot withdraw user funds. The token layer follows the contract layer. $AGNT fees power the paymaster. Staking $AGNT earns a share of 50 percent of platform fees in USDC. The 10 percent performance fee is payable in $AGNT, and paying it that way halves the cost. Stakers also vote on new roles and risk defaults. The presale allocates 30 percent of the fixed 1,000,000,000 AGNT supply across ten rounds, priced from $0.0080 to $0.0170, with a planned TGE listing at $0.02. Half of purchased tokens unlock at TGE, the rest vest over two months, and unsold supply is burned. Roles ship sequentially. Accumulator and Rotator reach beta in Q4 2026. Treasurer and Sentinel arrive in Q2 2027. A SolidProof audit and team disclosure land in Q1 2027. The project is not affiliated with Binance. The name references the BNB Chain network only. Here is the blunt read. The contract architecture is sound. Custody separation and on-chain mandate enforcement are real improvements over the custodial AI-trading products flooding the market. But sound code does not equal a profitable strategy. The Policy Guard stops the agent from crossing your stated limits. It does not protect you from bad interpretation, biased training data, or a mandate you wrote carelessly. Markets decide the results. The roadmap contains no guaranteed APY, no performance promises, and no audit today. Anonymous team, pre-audit contracts, and a token pricing ladder that rises without a live product are all standard presale signals. Buy the simulation first. Test the accumulator logic against volatile conditions. Verify that refusals actually revert. Then decide whether the fee model favors you or the platform. Self-custody is progress. It is not a substitute for due diligence. Author bio: Nathaniel Cross is a former Lead AI Research Scientist and decentralized protocol pioneer who has spent over a decade studying how smart contracts reshape autonomous agent architectures.
More
Bitcoin ETFs Built $111 Billion in Two Years. In 2026, They Added $717 Million. The Stall Is Structural. Business

Bitcoin ETFs Built $111 Billion in Two Years. In 2026, They Added $717 Million. The Stall Is Structural.

(SeaPRwire) - By: Christian Pierce The $57.79 billion cumulative net inflow figure that anchors every Bitcoin ETF discussion has become a story about a market that is no longer growing. US spot Bitcoin ETFs launched on January 11, 2024, and have accumulated 721,710 BTC. Total net assets across these funds reached $111.09 billion as of October 8, 2026. That puts them among the largest institutional Bitcoin pools anywhere in the world. But the year-to-date net flow for all of 2026 is only $717 million. Eighteen months of operation produced a contribution that is a rounding error against the cumulative total. The bulk of all-time inflows arrived in 2024, when demand from institutional allocators met a genuinely new product category. Since then, the market has been flat to negative. Cumulative net flows turned negative in mid-2026, reaching a low of negative $5.76 billion in July. The recovery in August and September pulled the figure back into positive territory, but the velocity of the reversal reveals how much of this capital is position-dependent rather than conviction-based. September delivered $2.65 billion in net inflows. The arc was clear in the daily data. September 21 saw the largest single-day inflow of the period at $999 million, with IBIT taking in $381.4 million and FBTC taking in $238.8 million. By September 22 the inflow had moderated to $714.7 million, and it bled steadily from there. September 23 recorded $346.9 million. September 24 brought $190.7 million. September 25 brought $134.5 million. September 28 registered just $31 million. October 7 then recorded a single-day outflow of $484.9 million, the largest since June 25. Through October 7, the month sits at negative $165.6 million. The 90-day average daily inflow is roughly $92 million. Daily trading volume on October 8 hit $3.58 billion. That ratio means nearly forty dollars of trading activity pass through these funds for every single dollar of net accumulation. The market is churning, not building. The competitive landscape is determined by a variable that has nothing to do with Bitcoin. BlackRock's IBIT holds $68.67 billion in assets and 785,640 BTC, more than four times Fidelity's FBTC at $15.66 billion and 176,510 BTC. Both charge 0.25% annually. BlackRock won because it had access to brokerage platforms, wirehouses, and registered investment advisors that its nine same-day competitors lacked. The fund structure was identical. The distribution plumbing was not. Grayscale's original Bitcoin Trust once held institutional monopoly status. It now charges 1.50% annually and has shrunk to $10.56 billion and 126,580 BTC after steady outflows since its January 2024 ETF conversion. The 1.50% fee is six times higher than the leading competitors, and that premium has accelerated capital migration away from GBTC. Grayscale launched the Bitcoin Mini Trust at 0.15% per year as a response. It has gathered $5.42 billion and holds 142,230 BTC. The mid-tier fee compression has been sharp. Bitwise charges 0.20% on $3.13 billion in assets holding 69,130 BTC. ARKB charges 0.21% on $2.87 billion holding 100,920 BTC. Franklin charges 0.19% on $467.1 million holding 9,700 BTC. Invesco Galaxy's BTCO charges 0.39% on $439.8 million holding 5,190 BTC. ProShares' BITO, the only futures-based product on the list, holds $1.71 billion and 158,890 BTC. VanEck's HODL sits at $1.22 billion with 51,930 BTC. Coinshares' BRRR trails at $475.6 million and 20,250 BTC. Morgan Stanley's MSBT has $903.8 million in assets without published volume data. WisdomTree trails at $181.7 million with 1,990 BTC and a 0.30% fee. These are shelf positions in a market where fee compression has made it nearly impossible for providers outside the top two to build scale efficiently. The commercial loop is distribution, pricing power, and the total absence of product differentiation. Every spot Bitcoin ETF holds the same fungible asset. The wrapper is identical. The only reason an investor holds IBIT instead of BTC or BITB is access, and access flows through existing platform relationships rather than active investor choice. That makes the switching cost structural, not behavioral. Fee compression at the mid-tier erodes revenue per dollar of assets under management while simultaneously expanding the addressable market through lower entry barriers. The result is a squeeze. Mid-cap providers cannot charge premium fees against a competitive floor of 0.15% to 0.25%. They also cannot achieve the scale needed to absorb fixed operating costs. BlackRock and Fidelity will absorb the remaining market at premium efficiency. The distribution moat that built $111 billion in two years can reverse in weeks, as it did during the July outflow crisis. When the 90-day average daily inflow breaks below zero for a sustained stretch, the fee compression cycle forces the mid-tier to consolidate or exit. The parallel European exchange-traded product market faces the same structural pressures, and the fee compression dynamic will play out across both jurisdictions. The endgame is two providers absorbing the US market at marginally lower effective costs, while the remainder of the field compresses into irrelevance. Author bio: Christian Pierce, a chief financial columnist and markets commentator specializing in exchange-traded product flows, institutional capital allocation, and the structural dynamics of competitive financial markets across global jurisdictions.
More
One Bitcoin Transaction Equals 1 Million Visa Swipes—And Everyone Pretends It’s Fine Business

One Bitcoin Transaction Equals 1 Million Visa Swipes—And Everyone Pretends It’s Fine

(SeaPRwire) - By: Oliver Hawthorne I've sat through enough investor roadshows to recognize when a technology is selling a dream while eating the planet. Bitcoin's energy appetite is not some distant abstract. It is a physical reality consuming more electricity than Thailand, a nation of 72 million people. The network draws an estimated 18.35 gigawatts continuously. That is not crypto. That is infrastructure the size of a small country, justified as digital gold. The numbers are stark. Bitcoin's annualized consumption sits between 82.45 and 309.35 terawatt-hours depending on which hardware efficiency model you trust. The best-guess range lands around 160 to 204 TWh. To compare: Finland, a cold northern country with heavy industry, uses roughly 85 TWh. Hungary runs on about 43 TWh. Bitcoin alone outstrips both. And this is not a static figure. It expands and contracts with Bitcoin's price. When the coin rallies, mining becomes profitable, more machines turn on, and consumption climbs. The peak hit in early 2022, briefly exceeding Finland's total national demand. The carbon intensity tells an equally ugly story. Annual CO2 emissions amount to 114.03 million tonnes, comparable to the entire Czech Republic. But here is what is worse. The energy mix has gotten dirtier since 2021. Before China cracked down on miners in spring 2021, roughly 41.6 percent of Bitcoin's electricity came from renewable sources. Much of that was Chinese hydropower during the wet season. After miners fled to the United States and Kazakhstan, renewables collapsed to 25.1 percent. They switched to coal and natural gas. Carbon intensity rose from 478.27 grams of CO2 per kilowatt-hour in 2020 to 557.76 gCO2/kWh by August 2021. The network is literally running on dirtier fuel now than it was four years ago. Visa processes 138.3 billion transactions a year across the globe using about 740,000 gigajoules for everything combined. That breaks down to roughly 0.00149 kWh per transaction. One Bitcoin transaction consumes an estimated 834.82 kWh. Do the math. A single Bitcoin transaction equals the energy footprint of 561,675 Visa transactions. In carbon terms, one Bitcoin swap generates 465.63 kilograms of CO2. Visa produces 0.45 grams per transaction. One Bitcoin transaction carries more carbon than over one million Visa payments combined. The BECI model calculates hardware efficiency at 17.01 joules per terahash on average. The newest machines push down to 9.50 J/TH. Older equipment drags up to 30 J/TH or worse. So even if the network adds more efficient miners, the total power demand does not shrink. It grows with price. That is the structural flaw. Proof of Work rewards whoever can burn the most electricity, not whoever can do it cleanly. The commercial loop is clear. Bitcoin sells itself as decentralized money. In practice it is a power-hungry settlement layer that outsources its security to whoever has the cheapest megawatts. When regulators and ESG committees start asking hard questions, the industry responds with hardware efficiency claims. But efficiency gains have never reduced total network consumption. They have always been swallowed by expanded mining operations. Until Bitcoin switches to Proof of Stake or faces genuine carbon pricing on its electricity, every transaction will continue to carry the environmental cost of a small town. The industry knows this. Investors know this. They just do not want to talk about it at fundraising events. Author bio: Oliver Hawthorne is a principal correspondent permanently stationed at an international technology review, covering the intersection of energy policy, digital infrastructure, and institutional capital flows.
More

Ripple’s XRP Lending Gambit: Why Validator Apathy Is the Real Risk Factor

(SeaPRwire) -By: Ethan Gallagher The market narrative has shifted uncomfortably fast. Brad Garlinghouse is pushing XRP from a speculative token into a collateral asset for institutional lending. This is a bold pivot. It ignores the current reality of the ledger. The technology simply isn't there yet. Investors are buying the dream of yield. The protocol is stuck in a waiting room of validator votes. Ripple claimed plans to expand the XRP Ledger into institutional credit markets. The goal is simple. Institutions use XRP holdings for loans instead of idle reserves. Evernorth started trading on Nasdaq under XRPN in October. They plan to deploy 473 million XRP from their treasury. Kraken, Coinbase, and BitGo support the initial strategies. Ripple contributed over 126 million XRP to this setup. The ledger added new account permission controls on October 8. Businesses can now delegate tasks without sharing private keys. This is good. It’s also the only part that works today. The reality hits hard when you look at the upgrades. XLS-65 and XLS-66 are pending. They are essential for fixed-term loans and asset pools. As of October 15, validator support sat at 60% and 54%. Activation needs 80% for fourteen consecutive days. That gap is the chasm. Ripple’s LendingProtocolV1_1 must activate first. It adds vault controls and interest recognition. Doppler Finance holds over $150 million in deposits from 14,000 users. These yields come from trading spreads, not native lending. The proposed framework keeps borrower checks off-chain. It uses optional first-loss reserves. Standard Chartered and LMAX handle stablecoin custody. But none of this changes the fact that native credit is unavailable on mainnet. The supply chain for institutional trust is broken at the validator layer. Until those specific network upgrades clear the threshold, this remains a circular economy of marketing. Author bio: Ethan Gallagher, a Silicon Valley Hardware Architect and Infrastructure Strategist focusing on decentralized ledger scalability and institutional adoption barriers.
More

One GPU, 10 Seconds, 7,200 Blocks: Buterin Just Told Everyone They Were Chasing the Wrong Benchmark

(SeaPRwire) -By: Ethan Gallagher Nobody in the zero-knowledge proving space needed another benchmark day. Someone was going to post a number, someone was going to congratulate them, and everyone would pretend the bottleneck was throughput. That was the script. Vitalik Buterin broke the script on October 15 when he walked into ZKsync's Airbender Prime announcement and said the speed race was over. Not "almost over." Over. The top priority, he said, should shift fully to security. That's not a soft redirect or a diplomatic acknowledgment. That's a protocol founder looking at the entire competitive landscape and telling everyone the scoreboard they've been watching was the wrong one. It also means that the entire arms race over proving latency — the one that consumed engineering cycles and raised expectations across the sector — has been reframed as table stakes. The question is no longer who can prove blocks fastest. It's who can prove them correctly, cheaply, and provably against a full adversarial model. Here's what happened technically. ZKsync released Airbender Prime on October 13. The numbers: one NVIDIA RTX PRO 6000 Blackwell graphics card proved 99% of 7,200 consecutive Ethereum blocks in under 10 seconds. Every single block finished within 12 seconds, and that timing included required proof preparation. The system uses open-source software and hash-based proofs designed to resist future quantum threats. These are real numbers from real tests, and the engineering achievement is not trivial. A single consumer-grade GPU handling this workload signals something fundamental about where proving costs are trending. Buterin's three security requirements landed alongside this news, and they cut deeper than any latency benchmark. He wants formal verification of proof equivalence against Ethereum's exact rules. He wants a strict upper limit on proving costs relative to block gas. He wants the proof system itself to be provably secure against adversarial manipulation. No timetable was announced for any of it. That silence is the most important data point in the entire announcement. Without a verification roadmap, a speed number is just a number. But let's look underneath those benchmark headlines. The speed figures came from ZKsync's own tests. They are lab conditions, not production deployment. No Ethereum developer has independently confirmed that proof accuracy holds under adversarial workloads. The cost ceiling Buterin demands — controlling proving costs relative to block gas — has no implementation roadmap anywhere in the codebase. If a prover can process blocks in seconds, that doesn't mean every operator can afford the NVIDIA RTX PRO 6000. The hardware is still enterprise-grade. The $2,300 to $2,350 ETH price range on October 15 told a different story. The daily relative strength index sat near 34. ETH hit a low near $2,317. U.S. spot Ethereum ETFs pulled in $19.7 million in net outflows the previous day, October 14. Traders are watching $2,300 support. The resistance sits at $2,400 to $2,450, then $2,500 to $2,550. None of this is about GPU benchmark velocity. This is about confidence in a security model that has never been formally verified at scale. Airbender Prime remains a ZKsync development, not an Ethereum network upgrade. That distinction is doing more quiet work in the market than any tweet about speed. The infrastructure is there. The verification isn't. The real supply chain play here has nothing to do with proving speed. If one RTX PRO 6000 can clear 7,200 blocks in seconds, the proving hardware layer becomes a commodity overnight. That devalues the compute infrastructure moat every zkEVM team has been selling as proprietary. The moat was never throughput. It was verification — the ability to prove, mathematically, that your proofs match Ethereum's rules exactly. Whoever ships that verification first captures the network's trust layer. Whoever optimizes for GPU throughput first captures a marketing headline that expires by next quarter. Buterin also flagged AI-driven wallet security concerns in a separate thread, which makes the security pivot more than rhetorical. The implications extend to wallet design, smart contract auditing, and the entire chain of custody for key management. The rest of the room is still deciding whether to believe him. The market has already voted, and it's sitting at $2,317. Author bio: Ethan Gallagher, a Silicon Valley Hardware Architect and Infrastructure Strategist who covers protocol-level infrastructure shifts and distributed computing supply chains.
More

The $1.30 Trap: Why XRP’s Technical Bleed Is a Liquidity Trap, Not a Break

(SeaPRwire) -By: Logan Pierce XRP is not falling. It is bleeding. There is a distinction that matters when you are trying to figure out if your capital is about to evaporate or if you are just watching dust settle. The market chatter around the $1.30 mark feels heavy with false urgency. Traders are screaming about a "breakdown" because a line on a chart got touched. But looking closely at the tape, this is a liquidity trap. The price hovers near $1.29 to $1.30, testing the 20-week exponential moving average. That line has been drifting. It was around $1.34 earlier in the year. Now it sits lower. This is not a sudden collapse. It is a slow erosion of the medium-term support structure. The weekly candle is still forming. Until it closes, nobody knows for sure if this is a washout or a true bearish signal. Panic selling into a forming weekly candle is a classic way to sell your position at the absolute bottom of a range. The official facts from the release paint a picture of persistent pressure. XRP traded near $1.32 on Thursday, October 15, before sliding down to the $1.29 zone. Analyst Ali Charts pointed to a potential rebound zone near $1.25 on his hourly charts. He identified that level as the lower edge of a parallel channel. It is a "possible" floor, not a confirmed one. Meanwhile, the broader market was messy. Crypto liquidations hit $959 million in a 24-hour window. Most of that came from long positions getting wiped out. This kind of volume suggests that the selling pressure is real, not just algorithmic noise. The daily trendline broke. The relative strength index dipped toward 35. That is weak momentum territory. It tells you buyers are exhausted. They are not necessarily gone, but they are not fighting hard. The subtext here is about institutional inertia versus retail panic. The press release notes that spot XRP ETF inflows totaled about $11.3 million over five trading days through October 9. That is a trickle. It is not a firehose. Those funds are not enough to push the price through the 50-week EMA, which sits around $1.52. So what happens when the slow drip of ETF buying meets the fast bleed of liquidations? The price gets pinned. It gets stuck in the $1.25 to $1.30 box. The $1.52 level acts as a ceiling. The $1.00 level acts as a floor. We are currently trapped in the middle. The "deeper drop" bears are eyeing toward $1 is a real risk if that weekly close fails. A drop from $1.30 to $1 is a 23% loss. That is a significant haircut. But the market is waiting for the close. It is a holding pattern. Competitors in the crypto space are not sitting still. While XRP struggles to find its footing, other assets are absorbing the liquidity. The focus on XRP’s technical breakdown is a distraction from the broader capital rotation. Smart money is likely hedging or moving to stablecoins while the weekly candle resolves. The "supply chain" of liquidity is thin. With $959 million in liquidations, the order book is thin on the sell side, but thin on the buy side too. There is no wall of buyers at $1.29. The next support is $1.25, then $1.00. The path of least resistance is down. But it is not a freefall. It is a grind. The weekly close will decide if the grind stops at $1.30 or continues to $1.00. Until then, the market is in a limbo state. The real story is not the price level. It is the lack of volume to support it. If the weekly candle closes below $1.30, the $1.00 target becomes the primary focus for the next two weeks. The $1.52 resistance is too far away to matter right now. Do not get caught in the crossfire of traders who are gambling on a V-shaped recovery. The data suggests a lower-low scenario is more probable. Watch the $1.25 level. If that breaks with volume, the $1.00 floor is in play. If it holds, the price may drift sideways for months. The endgame is a consolidation between $1 and $1.52, with the center of gravity shifting downward over time. The bulls need to push above $1.52 to change the trend. Until then, this is a bearish market structure. The "rebound" at $1.25 is likely just another stop-out zone for overleveraged longs. The wise move is to wait for the weekly close. Do not guess. Let the candle decide. Author bio: Logan Pierce, an independent business researcher and corporate governance writer for Medium, specializing in capital allocation and market structure analysis for high-volatility sectors.
More

The 15% Yield Trap: Why AI’s Debt Bubble Is Popping Before the Chips Do

(SeaPRwire) - By: Reginald Vance The panic in Wednesday’s session wasn’t about silicon quality. It was about the cost of moving electrons. AMD dropping 5.7% to $570.82 was a symptom, not the cause. The real story is that the hardware roadmap is no longer the bottleneck. Capital structure is. When you see Marvell Technology plummeting 8.7% and Dell Technologies losing roughly 11% in a single session, you are watching a sector-wide revaluation of risk, not a product failure. The market has realized that building a data center is no longer just a tech problem. It is a leveraged financial engineering game. And the players are running out of collateral. Let’s strip the PR. CoreWeave’s bond yields are touching 15%. That is a distress signal for high-growth infrastructure. Quarterly net interest costs have hit $640 million. In a normal capex cycle, a company spends cash to build assets that generate recurring revenue. Here, they are borrowing at triple-A junk rates to buy chips that Nvidia dominates. The math breaks down. If you can’t cover the interest on the debt that buys the accelerator, the accelerator is a liability, not an asset. Musk’s reaction on X was short. He just said "Yikes." That was the correct assessment. Look at the supply chain reaction. TSMC reported a 69% rise in quarterly profit, citing AI demand. That sounds bullish. But it is a lagging indicator. AMD’s second-quarter data center revenue was $6.7 billion, more than double the year-earlier figure. Nvidia is at $89 billion. The gap is too wide for AMD to close quickly. If AMD’s November 3 earnings show a slowdown in order growth, it won’t be because of TSMC’s yield issues. It will be because buyers like CoreWeave are pulling the plug on expansion to save cash. The selling spread to Broadcom, losing 3.1%, and Nvidia, down 3.2%, because investors are de-risking the entire AI infrastructure stack. The endgame for hardware vendors is consolidation through creditworthiness. We are entering a phase where chip design matters less than who can afford the inventory. The "free rider" problem in AI computing is becoming a debt trap. If your customer’s debt service exceeds their EBITDA, your Q4 orders are at risk. The industry will see a brutal clearing of weak data center operators. Survivors will be those with balance sheets, not just GPU clusters. Watch AMD’s Nov 3 report not for revenue growth, but for customer concentration metrics. If top clients are leveraged, the stock will correct further. The hardware race is pausing. The debt clock is ticking. Author bio: Reginald Vance, a venture partner specializing in semiconductor valuation and advanced materials, focusing on the intersection of hardware scalability and corporate credit risk.
More