Cathie Wood Just Bet $12.4 Million That Wall Street Is Wrong About CoreWeave’s Debt Bomb

(SeaPRwire) -By: Reginald Vance The panic trade in AI infrastructure is no longer theoretical. It has a ticker symbol, a bond yield, and a very specific number attached to it. CoreWeave stock dropped 15.46% on October 14, closing at $65.78. The trigger was not a missed earnings print or a lost customer. It was fear of the balance sheet itself. The company carried roughly $52 billion in debt and lease obligations at the end of June. Net interest expense in the second quarter alone hit $640 million. Unsecured bond yields have climbed toward 15%, which means the credit market is pricing CoreWeave like a distressed borrower, not a growth story. Into this selloff walked Cathie Wood. ARK Invest bought 188,665 shares, worth about $12.4 million at Wednesday's close. That is not a hedge. That is a directional wager that the market is mispricing physical compute capacity the same way it mispriced early cloud infrastructure a decade ago. The bull case rests on one staggering figure. CoreWeave reports a revenue backlog near $104 billion, and it claims nearly all of its 2027 capacity is already spoken for by customers. The bear case is simpler. Backlog is a promise, and promises do not pay coupon interest. Now look at what the filings actually show, because the details matter more than the headline. ARK did not just buy CoreWeave. It simultaneously trimmed 31,432 Palantir shares, roughly $6.3 million, while keeping the position open. Palantir closed Wednesday at $200.97, up more than 60% since August, riding a Goldman Sachs upgrade to Buy with a $230 price target. Read those two trades together and the strategy becomes legible. Wood is rotating out of the software layer, where valuations have already absorbed years of expected AI demand, and into the hardware-capital layer, where the market is punishing leverage without distinguishing good collateral from bad. The filings also showed additional purchases of Meta and Cerebras shares across several funds that same day. This is a coherent infrastructure thesis, not scattered dip-buying. The subtext underneath it is uncomfortable for the consensus. If CoreWeave's $104 billion backlog is real demand from creditworthy customers, then the company's debt is financing contracted revenue, and 15% bond yields are an overreaction. If even a fraction of that backlog is circular, soft, or dependent on customers who are themselves cash-burning AI ventures, then ARK just bought the equity stub of a leveraged landlord in a tenant credit crunch. Wood has been spectacularly right and spectacularly wrong on exactly this kind of convexity bet before. Follow the cash, not the conviction. CoreWeave's model is a financing machine wrapped around GPUs. It borrows against future capacity, builds data centers, signs long leases, and hopes the spread between contracted compute revenue and its cost of capital stays positive. That spread is now the entire question. When your unsecured debt trades at 15% yields, every new facility you build must clear a hurdle rate that most software companies never face. This is why the AI trade is bifurcating. Asset-light model developers get valued on narratives. Asset-heavy capacity providers get valued on bond math. Palantir sells software with expanding margins and government stickiness. CoreWeave sells megawatts with depreciation schedules. ARK's swap between the two is a bet that the market has overcorrected on the capital-intensive side of the stack. Here is my read, stated plainly. The winners of this cycle will not be the firms with the biggest backlogs. They will be the firms whose cost of capital stays low enough to actually deliver on them. If CoreWeave can refinance before its 2027 commitments come due, Wood looks like a genius who bought panic. If credit markets stay hostile, this $12.4 million purchase becomes a rounding error on the way to a much uglier restructuring conversation. The GPU landlords are about to discover that in infrastructure, the lender always gets paid first. Author bio: Reginald Vance is a venture partner specializing in semiconductor valuation and advanced materials, with fifteen years of experience pricing capital-intensive technology infrastructure and advising institutional investors on AI hardware credit cycles.
More

Bernstein Called Tencent and Alibaba Its Top China AI Bets. The EPS Miss Is the Reality Check.

(SeaPRwire) - By: Ethan Gallagher Bernstein just played its hand. Tencent and Alibaba are the top AI plays in China, the firm declares. Consumer demand is weak. Artificial intelligence is where returns will come from. That is the setup. It lets analysts point at AI progress while sidestepping a consumer slump that has been grinding on for quarters. Every AI training cycle burns real cash. Every agent deployment requires infrastructure that does not pay for itself overnight. And every enterprise buyer who has not yet proven they can monetize agentic AI is just a data point waiting to disappoint. Bernstein acknowledges the sector is frustrating because of consumer headwinds. Then it pivots to AI as the answer. That is not analysis. That is positioning. The firm wants to be on the right side of the AI narrative before the consumer picture gets worse. That is a bet on sequencing, not on fundamentals. And the sequencing matters. If consumer demand does not recover, the AI revenue story becomes the entire story. A one-legged bet is a fragile bet. The published thesis is direct. Bernstein believes the market undervalues Tencent's AI projects, including Workbuddy and Hy4. The firm sees option value in personal agents, AI tools designed to act on a user's behalf. Tencent is already generating AI returns through advertising and gaming, the report states, even while its chatbot work faces public scrutiny. The risk-reward profile remains positive, according to Bernstein. On the Alibaba side, the firm kept an Outperform rating despite a price target cut. The latest quarterly figures show revenue at $39.64 billion, up 8.6% year-over-year, beating the $39.52 billion consensus. But earnings per share at $1.26 missed the $1.94 estimate. Alibaba shares opened at $110.64 on Tuesday. The one-year range spans from $91.99 to $182.50. Bernstein also flagged Boss Zhipin and NetEase as preferred names based on idiosyncratic business drivers. NetEase closed at $123.73 on October 14 and traded higher at $125.11 in premarket. Citigroup raised its price target from $190 to $193 with a buy rating. Jefferies kept a buy rating and a $192 target. Nomura cut its target from $207 to $178. The MarketBeat consensus sits at a Moderate Buy with an average target of $182.89. Two analysts rate the stock Strong Buy. Thirteen rate it Buy. Six rate it Hold. Erste Group raised its FY2028 earnings estimate to $8.42 per share from $8.41. The current full-year consensus is $5.89 per share. The earnings report came out on August 14. Here is what the official report does not spend enough time on. Alibaba released Qwen3-Max-Thinking, and Bernstein noted investors will want proof that agentic AI can lift gross merchandise value and marketing revenue. That is the question that matters. The agentic AI narrative sounds impressive in product demos but has not yet shown consistent revenue lift in production environments. Alicloud is expected to keep beating expectations, according to Bernstein. But the $10.2 billion share sale is raising concerns about capital allocation priorities and investor confidence. Jack Ma bought more than HK$600 million in stock. Chairman Joe Tsai also added to his stake earlier this year. Insiders are putting their own money where their mouth is. On the Tencent side, the company is reportedly negotiating to buy mobile gaming studio SuperPlay for up to $1.5 billion. It bought $200 million of Bilibili's convertible senior notes. It launched TenPayGo, a mobile payment app for international visitors. These are moves that go beyond the core AI story. They signal a company building outward while simultaneously betting on AI as the next growth pillar. The gap between what companies announce and what they actually execute is where most analysis falls short. The fact that Erste Group is projecting FY2028 earnings at $8.42 per share against a consensus of $5.89 tells you the bull case depends heavily on far-future assumptions. The compute infrastructure reality is far simpler than any research note wants to admit. AI training runs on GPU clusters that cost millions to deploy. Cloud providers are scaling capacity but utilization rates remain uneven across workloads. If consumer demand stays flat through the next two quarters, the companies that can fund AI pipelines while absorbing revenue weakness will survive. The ones that cannot will start competing on valuation rather than fundamentals. Bernstein's call on Tencent and Alibaba may prove prescient. But the window is narrowing. The proof of AI monetization needs to show up in earnings reports. Not in model benchmarks. Not in press releases. The gap between claimed AI progress and actual revenue contribution is where every major AI investment thesis will be tested. Author bio: Ethan Gallagher, a Silicon Valley hardware architect and infrastructure strategist with over fifteen years in cloud computing systems design and data center scaling analysis.
More

Ericsson’s Stock Surge Isn’t Relief—It’s the Sound of a Supply Chokepoint Locking In

(SeaPRwire) - By: Reginald Vance The market rewarded Ericsson for missing half the picture. An 8% pop on earnings day looks like confidence. It isn't. It looks like investors recalibrating their fear, realizing the worst has been priced in and the next phase of pain hasn't started yet. The real story here is not revenue beats. It is who controls the components sitting between Ericsson and its customers. Net sales climbed 6% to 59.5 billion crowns against 55.4 billion expected. Adjusted EBITA fell 36% to 10.1 billion crowns, though analysts had braced for just 7.87 billion. The adjusted gross margin came in at 47.7%, slightly above the 47.3% forecast but down sharply from a year-ago period. Networks revenue grew 9% to 38.7 billion crowns. Cloud Software and Services rose 3% to 15.8 billion. Enterprise fell 10% to 4.6 billion, dragged by the iconectiv divestment. The Street got a better quarter than expected. Nobody is celebrating the margin trajectory. CEO Per Narvinger did not mince words either. He flagged that component costs would pressure gross margin next year and described the global RAN market as flat through 2026. The Q4 guidance of 49% to 51% adjusted gross margin is an upward revision from the current quarter, but it rests on the assumption that chip pricing stabilizes. That assumption is dangerous. Ericsson has been transparent about the pressure since July. Rising memory chip costs driven by surging AI demand are squeezing margins. This is not a temporary blip. AI infrastructure buildouts are absorbing memory and semiconductor capacity that telecom equipment manufacturers historically drew from. Ericsson competes for the same components as hyperscalers, and hyperscalers win on price and commitment. The Q4 margin guide implies some relief, but Narvinger's explicit warning means the company is bracing for further erosion. The adjusted EBITA margin narrowing from 28.1% to 17.0% tells the real story. Efficiency measures and cost cuts masked part of the decline. They cannot mask a structural input cost shift. North American sales saw modest growth helped by project phasing, not demand expansion. Organic growth came in at 7%. That is respectable for a flat market. It is also not enough to compensate for margin compression on a per-unit basis. What this signals is consolidation acceleration in the RAN equipment layer. Ericsson, Nokia, and any mid-tier vendor facing identical component cost pressure will either absorb the hit and bleed cash or raise prices and lose market share. Both paths hurt. The ones with supply agreements already locked in, longer-term chip commitments, or vertical integration advantages will survive with thinner but stable margins. The rest will become procurement subsidiaries for larger players or exit segments where component intensity is highest. Narvinger's flat market outlook for 2026 means there is no demand windfall to offset the cost squeeze. The only move is operational leverage and supply chain renegotiation. Investors priced that reality in Thursday's rally. The next earnings cycle will test whether the 49% to 51% margin guidance holds or collapses under renewed component inflation. Author bio: Reginald Vance is a venture partner specializing in semiconductor valuation and advanced materials supply chain analysis.
More

Jensen Huang’s “No” to Rogue AI: The Silicon Chokehold We Didn’t See Coming

(SeaPRwire) - By: Ethan Gallagher Jensen Huang said “yes” to a hypothetical. He would stop shipping chips to an AI developer acting unsafely. The market heard that and sold off. Nvidia closed at $221.30 on Oct. 14, down 3%. Premarket on Oct. 15 hovered near $217.86. Traders aren't pricing in safety ethics. They are pricing in regulatory risk. Huang framed it as a conversation, not a termination. “We don’t run other people’s companies,” he told Bloomberg. That nuance matters less to the ticker tape than the potential for a blacklist. If the chipmaker becomes the arbiter of safety, it holds the leash. Investors see a new variable: compliance overhead. This isn't just a stock dip. It’s a signal that hardware vendors might gatekeep software behavior. Huang’s comments in London ran parallel with a $250 million donation to UK AI safety research over five years. Oxford and UCL will get access to advanced compute. This is not charity. It is positioning. By funding the watchdogs, Nvidia insulates itself from criticism. Huang called fears “self-imposed” and part of growing pains. He dismissed the AI bubble talk. He claims demand for infrastructure will outstrip component supply for years. That’s the official release. The subtext is fear. If demand crashes, who buys the silicon? If demand persists, who controls the flow? The $250 million is cheap insurance against a narrative that “AI is too risky.” It buys goodwill in Europe ahead of a Berlin event. It softens the blow of being the sole supplier of the “bad” tools. The real friction point is the dual-use nature of the hardware. Huang admitted there is a limit to judgment because the tech is general-purpose. He can’t know what a customer does with the chips. Yet he implied he could stop supply. That is a massive shift in power dynamics. Historically, chipmakers sold to anyone who paid. Now, they might vet. Sunil Mittal of Bharti Airtel pushed for early government rules in India. He warned that agents might “run rogue.” Governments are waiting for an accident. Nvidia is waiting for a lawsuit. The gap between those two timelines is where the volatility lives. Huang’s “no bubble” claim relies on supply constraints. If regulators start throttling demand, the supply-demand balance Huang described breaks. The physical limit of silicon doesn’t change, but the permission to install it might. The supply chain is now a geopolitical and safety chokepoint. Nvidia isn't just a seller; it’s becoming a regulator by default. If a lab builds a model that crosses a line, Huang suggests a cutoff. That creates a dependency no customer wants. It also creates a new pricing power. Safety-compliant clients pay a premium. Non-compliant clients get cut off. The market will bid up the “safe” compute. The stock drop on Oct. 14 was the market digesting this new cost center. Huang wants the world to build on his chips. He just added a compliance fee to the bill. Watch the UK research grants. That’s where the rules will be written. The chips are the hammer. The safety research is the nail. Nvidia owns both. That is the real moat. And that is the real risk. Author bio: Ethan Gallagher, a Silicon Valley Hardware Architect and Infrastructure Strategist.
More

Stablecoins Are Flat. Velocity Is Everything — Standard Chartered’s Forecast Slip Is the Real Tell

(SeaPRwire) -By: Oliver Hawthorne The stablecoin market has stopped growing. That is the uncomfortable fact Standard Chartered accepted this week. The bank moved its $2 trillion forecast to 2030, two years later than the original call. Supply has sat near $309 billion for a year, trapped inside a $300 billion to $320 billion band. But here is the contradiction every serious market participant should feel: usage keeps climbing. Monthly transfer value averaged just under $10 trillion in 2026, up from $4 trillion in 2025. Supply flat. Movement exploding. That is not a stalled market. That is a market changing shape. Geoffrey Kendrick, the bank's head of digital assets research, called the slowdown cyclical, not structural. Weak crypto activity is the reason, and past flat periods were followed by renewed growth once markets recovered. The evidence cuts both ways. Onchain transfer value hit a monthly record of $19 trillion in May. Average monthly velocity doubled to about 30 times from 15 times in 2025. That means the same stock of coins is working much harder. The split between the two dominant tokens tells the real story. Tether's USDT velocity stayed near seven times. Circle's USDC jumped to about 80 times from 45 times. Kendrick attributes the gap to use cases. USDT functions as dollar savings in emerging markets. USDC is used for payments, financial transactions, and early payments between AI agents. USDC also leads the small AI agent transaction market. That gap matters because velocity changes the competitive field. Then consider the new entrants. Kendrick expects the toughest competition in developed market payments. USDG, M^0, and A+, a planned bank-backed shared stablecoin network, are all chasing the same rails. A key detail: banks inside A+ would keep the reserve income. How issuers and networks split reserve yield may decide who wins share. Regulation is the other force. The US Treasury proposed rules in August that limit issuance to federally or state-authorized issuers. Licensing requirements are expected to take effect in January 2027. The FDIC proposed stripping stablecoin holders from pass-through deposit insurance. The Financial Accounting Standards Board proposed an update in August that could change how firms report stablecoins. The report was released Oct. 14, 2026, with supply still near $309 billion. Now the commercial loop. Stablecoin supply was the old scoreboard. The new scoreboard is control over reserve yield and settlement flow. Banks want the interest. Payment networks want the turnover. USDC's 80x velocity shows that payment use can generate fees even with a flat float, but it also shows a threat: high velocity means each coin is doing many jobs, and any competitor that offers better liquidity will drain volume. A stablecoin that changes hands 80 times a month behaves like a clearing system. A stablecoin that changes hands seven times behaves like a deposit. Those are different businesses with different margins. Tether's 7x velocity is slower, yet its holders are dollar savers, not transactors, so the revenue is sticky and less dependent on payment infrastructure. Regulation is the pivot. If other countries follow the GENIUS Act, Tether's emerging market lead becomes a compliance burden rather than a moat. Authorized issuers will corner the legal market, and reserve yield splits will become the main competitive weapon. The endgame is not a $2 trillion balance sheet. It is a worldwide settlement network run by whoever controls the reserve economics. Watch the network deals, not the issuance totals. Author bio: Oliver Hawthorne, a Principal Correspondent at an international technology review, covers fintech infrastructure, digital asset markets, and the institutional shift toward programmable money.
More
SUI Bleeds Below $1 While Institutions Are Quietly Loading Up — Here’s the Real Story Business

SUI Bleeds Below $1 While Institutions Are Quietly Loading Up — Here’s the Real Story

(SeaPRwire) - By: Lucas Caldwell SUI just smashed through the one-dollar mark on October 15th and nobody is saying the right thing about it. Retail traders are getting liquidated in droves. ETF buyers are still stacking. The market is sending two opposite signals at once and most people are too busy looking at a red chart to notice the divergence. Here is what actually happened that day. SUI opened around $1.022, briefly pushed to $1.025, then collapsed down to $0.963 before settling near $0.977. That is roughly a 4.3 percent drop on the Binance daily chart. The broader liquidation count tells a louder story. Over 24 hours, about $959.43 million in crypto positions got wiped out. Nearly all of it came from longs. $879.71 million of that total was from bullish positions being forced out. In just the final four hours, another $521.99 million in liquidations hit. The rising trendline that carried SUI from $0.68 up to nearly $1.30 in September is now broken. Price has slipped back into the $0.95 to $1.00 zone, which was resistance before that whole breakout happened. Now look at the other side of the trade. U.S.-listed SUI investment products logged five straight weeks of net inflows. That is 14 million SUI accumulating while the price was falling. Bitcoin and Ethereum products recently saw outflows. The institutional money is moving in the opposite direction of retail sellers. Samsung Wallet announced it will bring USDC on Sui to 82 million U.S. Galaxy devices using gasless stablecoin transfers. The Sui Foundation confirmed on October 12th that DATA Network and its Trace AI-data registry are moving onto Sui and Walrus. Trace has registered more than 250 million data contributions and processes over three million receipts a day. DeFi total value locked on the network sits above $1.2 billion. Trading volume remains active on DeepBook. Hashi's mainnet rollout begins this month with over $500 million in committed capital. Anchorage Digital joined a coalition of more than 20 institutional partners. The daily RSI sits at 43.92. It is below neutral but not yet in oversold territory. The MACD histogram reads about negative 0.0318 with the signal line near 0.0513. Analyst Crypto Patel flagged that the first accumulation zone delivered a 103 percent gain and the next re-entry zone sits between $1.00 and $0.75. He is waiting for SUI to reclaim $1.4223 before calling it a bullish flip confirmation. His targets start at $2.65, move to $5.36, and extend toward $10 in a bull market with a macro target of $20. If $0.95 fails, the next structural support sits at $0.78 to $0.84. The fundamental question here is whether ETF inflows can actually hold price when leverage gets flushed like this. Five weeks of accumulation sounds solid until you see how thin liquidity gets after a $959 million long wipeout. The Samsung deal matters for adoption metrics but does not necessarily absorb sell pressure from exhausted leveraged positions. The real test comes next week. If SUI holds $0.95, the institutional bid from those ETF funds becomes meaningful support. If it breaks, the slide toward $0.78 accelerates and those inflows just buy the dip faster than the market can sell into them. Chains do not care about chart patterns. But capital flows absolutely do. The divergence between retail liquidation and institutional accumulation is the signal. Most people are watching the wrong one. Author bio: Lucas Caldwell is a tech opinion leader with millions of followers on X/Twitter, covering crypto markets, on-chain data, and digital asset infrastructure trends.
More

Kalshi’s CEO Drew the Binary: Prediction Markets Stay American or Go Offshore

(SeaPRwire) -By: Jonathan Barrett The U.S. prediction market is in a jurisdictional knife fight. Kalshi CEO Tarek Mansour called it out Wednesday at DC Fintech Week near Washington. He drew a blunt line. Federal oversight keeps event trading alive on American soil. State regulators block it under gambling statutes. His warning was not hypothetical. "It's a choice of whether prediction markets exist in the U.S. or whether they go offshore," he said. That is the sentence every CFTC commissioner and state attorney general needs to hear. The fight is not about definition. It is about survival for an entire class of financial products. American capital either participates in this asset class or gets shut out. The offshore alternative is real and growing. The CFTC proposed on October 9 to treat prediction market event contracts as swaps. That category falls under federal derivatives law. A separate interim rule excludes casino-style games from the swap definition. Federal appeals courts are split. One ruling supported Kalshi's federal oversight argument. Two others favored state authority. The Supreme Court justices have not agreed to hear New Jersey's case. Kalshi must respond to the petition by November 9. The proposed change covers contracts linked to sports, politics, weather and culture. Each piece of this framework remains subject to the rulemaking process. The legal foundation is still under construction. This remains the only credible federal regulatory answer. States and the CFTC fight over who writes the rules. State officials have taken Kalshi and other operators to court. They argue contracts tied to game results amount to sports betting. The NFL has backed New Jersey's Supreme Court appeal. The league also raised concerns about consumer protections and game integrity. State attorneys general seek to apply gambling rules to prediction markets. Each jurisdiction treats sports contracts differently. Kalshi's defense rests on the Commodity Exchange Act. Mansour says that law gives Washington authority over markets that extend beyond traditional commodities. He framed sports outcomes as carrying economic consequences. This is not a new legal theory. States have long claimed gambling jurisdiction over any market tied to competitive results. The NFL's backing gives states extra political ammunition. More firms are chasing U.S. prediction market access. Last week, Blockchain.com applied for two CFTC licenses. One would cover prediction markets. The other covers crypto derivatives. The CFTC's interim rule draws a deliberate line between regulated contracts and casino-style gambling. That boundary is not accidental. It is meant to keep market makers out of state gambling regimes. For established players like Kalshi, the federal track remains the only viable path. For newcomers, license applications double as political signals. The market is crowded and the legal floor is still being poured. Each new applicant adds weight to the federal oversight argument. The flood of applications proves the market wants this. The CFTC needs every applicant it can get. Mansour faced questions about repeated transaction sizes in Kalshi's Bitcoin and Ether perpetual-futures markets. He rejected claims that those patterns showed inflated volume. Market makers place fixed-size orders, he explained. Those fixed sizes produce repeated trade amounts in settlement records. He criticized speculation about the figures. Trading activity is difficult to interpret without understanding how orders actually work. For new entrants like Blockchain.com, the regulatory fog demands compliance hedging. License applications serve as insurance against an uncertain legal landscape. Every player is building redundancy into their regulatory strategy. No operator wants to be caught without a federal permit when states close the door. Regulation shapes how these markets trade. The regulatory fog is only getting thicker. The first offshore prediction market opens before November 9, and Kalshi's warning becomes an obituary rather than a caution. Author bio: Jonathan Barrett is a lead focus editor for an independent overseas public affairs weekly, specializing in regulatory policy analysis and enforcement tracking across financial and technology sectors.
More

The Illusion of Anonymity: Why StarkWare’s OffMarket Fixes Nothing on Polymarket

(SeaPRwire) -By: Oliver Hawthorne Prediction markets live and die by public liquidity, yet the traders funding those pools have spent years broadcasting their every move to anyone with a blockchain explorer. StarkWare’s public rollout of OffMarket aims to fix this glaring exposure on Polymarket, giving participants a way to place bets without tying positions directly to their primary crypto accounts. It is a neat piece of engineering designed to soothe user anxiety over on-chain doxxing, but it arrives amid a suffocating cloud of platform uncertainty and regulatory crosshairs. When the privacy layer itself requires trusting a compliance gatekeeper, the entire proposition starts to look less like user sovereignty and more like a clever illusion. The underlying mechanics rely on Starknet’s privacy pool and zero-knowledge proofs to sever the direct link between a user's initial deposit and their trading wallet. Anyone can sign in using Google or a crypto wallet, deposit up to $1,000 USDC through Polygon, and spin up a separate wallet for each individual position. These funds sit in an open-source pool rather than a centralized corporate vault, and traders retain control of their browser-based keys. Once funded, orders route straight into Polymarket’s existing order books, allowing private traders to match with public buyers and sellers at identical prices without opening a dedicated Polymarket account. Yet this architecture comes with substantial asterisks that strip away the marketing gloss. Every trade remains fully visible on the Polygon network, exposing exact sizes, timestamps, and wallet addresses for anyone motivated enough to trace them. OffMarket only conceals the umbilical cord connecting the trade to a user's primary account, leaving distinct transaction patterns vulnerable to heuristic analysis. The shared Starknet privacy pool holds roughly $1.5 million spread across 17,000 deposits, guarded by a compliance company holding a viewing key for sanctions checks. Furthermore, the service strictly inherits Polymarket’s geographic bans, leaving US users locked out entirely while legal battles over prediction market oversight grind on. By bolting zero-knowledge wrappers onto centralized order books, protocols are discovering that true financial privacy cannot coexist with regulatory appeasement. Users gain a temporary shield against casual onlookers, but the architecture ultimately caves to compliance demands and public ledger permanence. As prediction platforms face mounting scrutiny over tokens and jurisdictional compliance, privacy layers will increasingly serve as regulated tollbooths rather than escape hatches. The endgame here is not sovereign anonymity, but a heavily monitored theater of discretion where every hidden position ultimately pays rent to the state. Author bio: Oliver Hawthorne, a Principal Correspondent permanently stationed at an international technology review, specializing in the intersection of decentralized protocols, privacy engineering, and regulatory market structures.
More

Your Next Customer Won’t Have a Name, a Face, or a Bank Account — It’ll Have a Wallet and 18 Minutes of Patience

(SeaPRwire) -By: Oliver Hawthorne The software industry has spent two years obsessing over what AI agents can think. Nobody wanted to discuss what they can pay for. That silence is now ending, and the discomfort is real. Coinbase's x402 protocol just crossed 138 million transactions on Base, according to Chainalysis, and the detail that should unsettle every payments executive is the size of the ticket. Over 87% of analyzed payments fell between $0.0001 and $0.10. These are amounts Visa cannot touch profitably. Card networks lose money processing a two-cent charge. Stablecoins do not. So the anxiety in the room is not about crypto speculation anymore. It is about a settlement layer being quietly built for a customer class that has no human behind it. I raised this with a payments engineer at a fintech conference last month. His answer was blunt. "We have no product for a machine that wants to buy a $0.003 API call." That gap is the story. The industry built its commercial plumbing around humans clicking checkout buttons. Agents do not click. They settle, instantly, without approval loops, and they are doing it at a scale most product teams have not modeled. The evidence is harder to dismiss than the skeptics hoped. Chainalysis tracked AI agents buying data, software tools, and access to AI models through x402 during its 2026 reporting period. The geographic split tells its own story. US-linked wallets accounted for 88.1% of identified payments for AI model inference. Chinese-linked wallets represented just 0.1% of that category, yet generated nearly 90% of tracked security and code-analysis payments, mostly flowing to the smart contract auditing service AgentLISA. Chainalysis itself notes that free-to-use models such as DeepSeek and Qwen may be suppressing Chinese demand for paid model access. Two distinct machine economies are forming along national lines. The behavior metrics matter even more than the geography. Among qualifying wallets first funded in the second quarter of 2026, 89.3% received another deposit within 30 days, up from 70.6% for comparable wallets in the third quarter of 2025. Stickiness is compounding. And the median time between a wallet's initial funding and its first x402 payment collapsed from 73 days in late 2025 to 18 minutes in the third quarter of 2026. Read that again. Seventy-three days to eighteen minutes. The onboarding friction between "funded" and "transacting" has effectively vanished. This is no longer experimentation. It is habit. Now follow the money to its logical end. The commercial loop here is simple: agents earn or receive funds, they spend those funds on inference, data, and code review, and the providers receiving those micropayments reinvest in capacity. Whoever owns the rail owns the toll. That is why the surrounding moves deserve attention. Ripple's partnership with Stripe-owned Privy brings embedded wallets to XRP Ledger applications, supporting XRP, RLUSD, and automated payments through the x402 standard. The protocol is already escaping Base. Sui reported 40.6 million transactions per second in an off-chain stress test of simulated agent activity, a capacity claim rather than completed purchases, but a clear signal that chains are racing to become the default highway. Wells Fargo outlining its stablecoin preparations is not a coincidence either. Banks smell settlement revenue migrating off their rails. The honest caveats from Chainalysis deserve respect: the data covers observable x402 transactions only, not all agent spending, and transfer volume does not prove commercial value. Fair. But the endgame is legible regardless. The winning stack will combine cheap stablecoin settlement, embedded wallets, and a protocol agents can call without human sign-off. Every piece now exists in production. The practical advice for any SaaS or data business reading this: expose a machine-payable endpoint, price it in fractions of a cent, and do it this quarter. The agents are already shopping. The only question is whether your door accepts their money. Author bio: Oliver Hawthorne is a Principal Correspondent permanently stationed at an international technology review, covering machine commerce, payment infrastructure, and the economics of autonomous software.
More

Kraken Just Bought Itself a Bank: Payward’s Quiet End-Run Around Europe’s Regulatory Moat

(SeaPRwire) -By: Logan Pierce Payward is done asking banks for permission. The parent company of Kraken signed an agreement on October 14 to acquire Saldo Finance Oy, the Finnish owner of Lithuania-based Saldo Bank. Strip away the corporate framing and this is simple. A crypto exchange is buying a licensed deposit-taking institution outright. Not partnering with one. Not renting a license through an intermediary. Buying the whole thing, charter included. That signals how Payward reads the European market. The firm no longer trusts correspondent banking relationships to survive the next compliance crackdown, so it is internalizing the banking layer entirely. The asset itself is compact but functional. Saldo Bank holds a specialized banking license in Lithuania. The European Central Bank licenses it, while Lithuania's central bank supervises local operations. It serves customers in Lithuania, Finland, Sweden and Germany, and already has authorization to enter the Netherlands. Saldo accepts retail term deposits across those four active markets. It issues consumer loans in Lithuania, Finland and Sweden, plus business loans in Lithuania and Finland. A credit card operates in Finland, with a Swedish launch planned for 2027. It even sells lending technology to financial firms in Finland and Germany. Now the transaction mechanics. Payward did not disclose the purchase price. Closing is expected in 2027, contingent on regulatory review and standard conditions. That is a long runway, and it tells you the regulatory gauntlet is the real cost here, not the cash. Payward's stated intent is to layer on interest-bearing deposits, consumer lending, card services and euro payments. Notably, this deal is about traditional banking rails, not another crypto trading license. Payward separately secured full regulatory approval in Dubai for Kraken's regulated crypto services, so the licensing strategy runs on two distinct tracks. Context matters. This agreement arrived alongside separate talks between Payward and Wells Fargo about supplying crypto trading liquidity. Those talks produced nothing announced. The bank purchase is an agreed transaction. The contrast is instructive. Negotiating with an incumbent American bank for liquidity access is slow and uncertain. Acquiring a small European specialized bank is decisive. Payward Banking claims more than $2 billion in originated loans, an Irish electronic money institution license, and limited access to the Federal Reserve payment system. The Saldo deal fills the European deposit and credit gap in that stack. Competitors are converging on the same insight from different angles. Payments company Rain recently applied for a US national trust bank charter to support stablecoin and custody services, still under review. Co-CEO Arjun Sethi has said Payward is expanding banking infrastructure across markets, and the pattern confirms it. The industry's center of gravity is shifting from exchange volume toward regulated financial plumbing. Whoever controls deposits, cards and euro payments controls the customer relationship. Trading fees compress. Banking relationships endure. Watch which crypto firm buys the next European specialized bank, because the first one just did.
More

BlackRock’s Crypto Comeback: The $79.6B Illusion and What Wall Street Won’t Tell You

(SeaPRwire) -By: Robert Kensington BlackRock added $7.9 billion in new money to its crypto bucket this quarter. The headline grabs attention. But look closer at the math, and the picture shifts. The firm's digital assets jumped 63% to $79.6 billion during the third quarter of 2026. That sounds like a recovery. It is partly just price appreciation doing the heavy lifting. Market gains accounted for $22.9 billion of that increase. The remaining $7.9 billion came from actual investor deposits. This reversal is significant. The first half of 2026 saw $2.2 billion in withdrawals from BlackRock's crypto products. Investors fled when Bitcoin and Ether prices tumbled. Now they are back, but the damage from a year ago remains visible on the balance sheet. Despite the quarterly surge, BlackRock's crypto holdings sit 23% below the $104 billion level reported in September 2025. The math is brutal. Over the past twelve months, investors added $6.3 billion in net deposits. Yet the total value dropped by $30.6 billion because of market movements. The asset giant cannot escape gravity, no matter how much cash flows in. The fee economics tell another story. BlackRock pulled in $39 million this quarter from digital asset fees and securities lending. That is a modest return for managing nearly $80 billion. The firm charges roughly 50 basis points on its iShares Bitcoin Trust. It is competitive, but thin. Margins will compress further as rivals like Fidelity and Grayscale lock in their positions. Trading patterns reveal where the money actually moves. On October 9, BlackRock's iShares Bitcoin Trust attracted $22.4 million. US spot Bitcoin ETFs collectively received $21.1 million that same day. This represents one session, not the full quarter. But it shows the daily volatility behind the headline numbers. The Ether product tells a different tale. On October 6, BlackRock's ETHA recorded $201.89 million in outflows. Meanwhile, IBIT pulled in $122 million that same day. Investors are rotating out of Ethereum products while staying put in Bitcoin exposure. The divergence between the two largest crypto ETFs widens. Industry flows have also shifted. US spot Bitcoin ETFs recorded $678.9 million in net withdrawals from October 5 through October 9. BlackRock's Bitcoin fund registered a small weekly inflow during that same period. The flagship product remains resilient even as the broader market sees profit-taking. The real story is about capital efficiency. BlackRock manages approximately $15.5 trillion across all operations at quarter-end. Crypto represents just 0.5% of that total. The division is profitable, yes. But it is a rounding error in the broader business. The firm is not betting its future on digital assets. It is monetizing existing relationships. What happens next depends on price action and regulatory clarity. If Bitcoin breaks above $100,000 and stays there, inflows will resume. If not, the $7.9 billion addition this quarter will look like a temporary bounce. The structural question remains unanswered: can crypto ETFs generate consistent fees without constant market appreciation? My take is blunt. BlackRock's crypto recovery is real, but it is fragile. The firm proved it can attract capital when markets move up. It has not yet proven it can retain that capital when markets stall. The 23% gap from a year ago is a warning sign. Until that hole fills, this is not a structural comeback. It is a cyclical one. Author bio: Robert Kensington, an overseas entrepreneurial veteran with decades of experience in real-economy industrial investment and expansion, now advising institutional clients on cross-asset allocation strategies.
More

Ark Is Betting the Farm on the Pumps, Not the Faucets — And That Changes Everything

(SeaPRwire) - By: Reginald Vance Mark Zuckerberg just announced he is willing to spend between $100 billion and $200 billion on artificial intelligence. That is not a product budget. That is infrastructure capital expenditure of a magnitude most people still associate with cloud hosting, not consumer social media companies. The market reacted by moving Meta up 2.6 percent on Tuesday. But the more interesting signal came from the other side of the trade. ARK Invest was simultaneously dumping consumer-facing AI names like Personalize and Toast while aggressively adding to both Meta and Cerebras Systems. Cathie Wood is not chasing applications. She is chasing the electricity and the silicon underneath them. The mechanics of the trade tell the whole story. ARK bought 22,734 Meta shares at $762.50, roughly $17.33 million across its ARKW and ARKF funds. That followed a earlier accumulation earlier in the week and a prior trimmed position on October 8. On the hardware side, ARK loaded up on 67,362 Cerebras shares at $149.08, almost $10 million through ARKW alone. This came one day before 19.4 million shares unlocked from the October 14 IPO lock-up window. Cerebras sits at the center of a supply deal with OpenAI that delivers 750 megawatts of computing capacity and carries a valuation north of $20 billion. OpenAI reportedly hit $50 billion in annualized revenue in September. Meanwhile, ARK sold 901,647 Personalize shares for $14.29 million, offloaded 406,020 Toast shares for $12.54 million, and pared back Everpure holdings for $10.13 million. Analyst consensus rates both Meta and Cerebras as Strong Buys, though the implied upside diverges sharply at 7.1 percent for Meta versus 93.6 percent for Cerebras. What this capital rotation reveals is a fundamental thesis about where the bottleneck lives in the AI stack. Meta is building its Prometheus cluster in Ohio and planning a Hyperion facility in Louisiana, self-funding through operating cash and borrowing. These are not software decisions. They are heavy civil engineering, power procurement, and custom silicon deployment problems. The Cerebras bet is even more pointed. It is a direct wager on wafer-scale engine availability competing against H100 and B100 supply constraints. ARK is effectively saying the next round of value creation will not flow to the app layer first. It will flow to the companies that control compute delivery and the hyperscalers building the physical plants to host it. The implied upside gap between Cerebras and Meta reflects exactly this risk premium. Hardware suppliers carry more optionality right now because supply has not caught up with demand. Cash flow efficiency in this sector will determine which chip vendors survive consolidation and which get absorbed. ARK's pattern of trimming Personalize and Toast while doubling down on infrastructure names maps directly onto a broader institutional recalibration happening across the asset management industry. Consumer AI valuations are beginning to price in revenue scenarios that require sustained adoption curves the market has not yet delivered. Infrastructure valuations are pricing in utilization that is already happening at OpenAI, Anthropic, and the major cloud providers. The hardware vendor landscape is about to compress. Cerebras, SambaNova, and a handful of others are racing to fill a $20 billion plus order book. The ones that can ship at scale and maintain margin will define the next decade of AI economics. The ones that cannot will become acquisition targets or fade into legacy supplier status. ARK is placing its chips on the shippers. Author bio: Reginald Vance is a venture partner specializing in semiconductor valuation and advanced materials, with prior roles at leading foundry strategy firms and infrastructure investment funds.
More

BAC’s $1.21 Billion Lesson: The Fine Was About the Blind Spots, Not the Quarter

(SeaPRwire) - By: Christian Pierce Bank of America walked into its own earnings call carrying a $1.21 billion penalty that management could not spin away. The stock slipped about 2% in extended trading Tuesday, and the latest quote showed another 1.14% drop. The market didn't panic. It repriced. The bank reported Q3 net income of $6.9 billion, or $0.91 per diluted share, against the analyst consensus of $1.10. A year earlier, BAC earned $8.3 billion, or $1.04 per share. The gap had nothing to do with loan demand or trading desks. It had everything to do with a compliance failure that Treasury says let more than $5 billion in suspicious transactions slip under the radar. Excluding the settlement charge, adjusted net income was $8.1 billion, or $1.08 per share, on revenue of $30.0 billion, up 3%. Revenue still missed the roughly $30.69 billion analysts had modeled before the fine. The bank says the charge is not tax deductible and costs $0.17 per share. That is the cleanest explanation for the earnings miss. But the cleaner story is more uncomfortable. Regulators had already issued a cease-and-desist order in December 2024. The problems persisted. FinCEN and the OCC did not hold back. FinCEN assessed a $1.2 billion penalty, the third-largest in Treasury history. The OCC added a $750 million civil penalty, the largest in that agency's history, and that amount counts toward the $1.21 billion total. The bank admitted willful violations of the Bank Secrecy Act. That admission matters more than the dollar figure because it changes how the market values future compliance costs. Treasury's action on October 13 laid out the ugly details. More than $1 billion of the unreported activity involved national security concerns. Treasury pointed to Chinese money-laundering networks, fraud, and illicit finance along the southwest border. That is not a clerical oversight. It is a failure to recognize who was moving money through the system. The OFAC settlement added another layer, with an $11.6 million fine covering 475 apparent violations of Russia, Iran, narcotics, and terrorism sanctions programs. The numbers are small next to the $1.2 billion headline, but they show breadth. The bank was not just missing domestic red flags. It was missing sanctioned parties too. Regulators said BAC leaned too heavily on tips from law enforcement and peer banks. In other words, the bank outsourced its own suspicion-generation process. That description is brutal. It suggests the transaction monitoring system was reactive, not proactive. It also explains why Treasury is forcing outside parties to review undetected suspicious transactions. Independent assessments of transaction monitoring and customer due diligence are required. So the bill is not just $1.21 billion. The bill includes years of external oversight, plus the cost of rebuilding internal controls that should have worked the first time. Treasury Secretary Scott Bessent's message was direct: the biggest banks are not above the law. For investors, that is the kind of line that should stick. BAC will not see serious multiple expansion until it proves the consent order is behind it. The bank said it plans to see its remediation work through. That language is standard. Markets are watching what the outside reviewers find, not what the press release says. Now the commercial loop. The fine does not directly limit Bank of America's ability to grow lending. The dividend still pays $0.32 per quarter, a 2.13% yield. TipRanks shows a Strong Buy consensus, 13 Buy ratings and three Hold ratings, with an average price target of $65.87. That implies 22.1% upside from the post-fine quote. Analysts have not abandoned the stock. But the price target was built on a different set of assumptions. A $1.21 billion penalty creates a permanent overhang in the earnings model. It also raises the cost of future acquisitions, if BAC ever wants to do one, because regulators will weigh this history. The real test is not next quarter. It is whether the bank can show, in writing, that it stopped depending on law enforcement tips and started generating its own suspicious activity reports. The OCC's December 2024 order was already a warning. The October 13 action proves the warning did not take. That should change the investor calculus. I would not chase the dip until the outside monitors publish their first assessment and the bank discloses a concrete remediation timeline. A cheap stock can still be a value trap when the compliance bill keeps growing. Bank of America is not at risk of failure. It is at risk of becoming a lower-return institution that spends $1 billion-plus on fines and then spends billions more to prove it can follow the law. That's a structural cost, not a one-time event. The market is right to mark the shares down. The only question is how many more marks are coming. Author bio: Christian Pierce, chief financial columnist and markets commentator, covers bank earnings, capital discipline, and regulatory risk. He has analyzed Wall Street through multiple rate cycles and writes daily on market structure and investor behavior.
More
GME’s Rally Hits a $28 Wall — Cohen’s $99 Million Isn’t Enough to Break It Business

GME’s Rally Hits a $28 Wall — Cohen’s $99 Million Isn’t Enough to Break It

(SeaPRwire) - By: Robert Kensington Ryan Cohen spent another $22.8 million on GameStop stock on Tuesday. He bought 844,130 shares between $26.75 and $27.00 each. That brings his total spending since mid-September to over $99 million. He now holds roughly 10% of the company's public float, or about 42.5 million shares. The market is calling this conviction. I've seen this playbook in my three decades of watching industrial investment cycles, and it's never as simple as the headline suggests. A CEO who owns this much of his own equity in a name that became a memestock legend isn't just signaling shareholder alignment. He's positioning on both sides of the trade. The distinction matters enormously when the underlying asset is a stock that surged on Reddit karma more than on earnings quality two years ago. The story gets more complicated because GameStop is genuinely reinventing its business model around collectibles. But reinvention and speculative momentum are two different forces, and they rarely move in the same direction at the same speed. The market never forgets where GME came from. Every dollar Cohen spends on the open market only reinforces that memory. That memory is simultaneously his greatest asset and his most dangerous liability. The man who built a reputation buying undervalued stocks and sitting on them is now doing the same thing with a name that has a very different gravitational pull. The official facts are clean and easy to parse. GameStop reported record second-quarter operating income. Collectibles revenue jumped 57% year over year, turning what was once a curiosity into a material revenue stream. Management raised full-year adjusted EBITDA guidance to more than $650 million. That's a significant upgrade from prior guidance. Cohen filed a Form 4 on October 13 showing the latest tranche of purchases. His holdings are now approximately 42.5 million shares, representing roughly 10% of the public float. This was his fifth buy since September 10. Prior to this round, he'd already spent $17.1 million earlier in October. The stock traded near $27.65 to $27.72 in Wednesday pre-market, up about 2% from Tuesday's close of $27.22. That puts GME on pace for its highest close since June 2025. In a vacuum, these numbers justify the rally. A CEO with 42.5 million shares of his own skin in the game, a company with accelerating collectibles margins, and an upgraded EBITDA outlook tell a coherent story. The collectibles pivot is real. The revenue growth is real. The EBITDA guidance upgrade is real. The narrative holds together on its surface. That's precisely the problem. Every fact in the official release can be independently verified. Cohen himself said earlier this year that it was essential for public company bosses to buy shares. He framed it as strengthening alignment with stockholders. That framing is sound governance philosophy. Applied to a memestock with 10% insider ownership, it reads differently. The only thing you can't verify from the filing is what Cohen's model is actually telling him about where this stock should go from here. The subtext is where the real risk lives. Barron's already flagged it. The rally carries memestock DNA, and GameStop remains the original meme stock. In past cycles, this name moved on social media momentum, not on balance sheets. The technical picture reinforces that concern. RSI sits at 75, deep in overbought territory. MACD is above its signal line, so momentum is intact, but the move is stretched. Price is pressing into the $26 to $28 supply zone that capped rallies back in October 2025 and again in April 2026. The long downtrend line that suppressed price action throughout 2025 finally broke in September, and the stock has printed higher highs since the $17.80 low. That old trendline now serves as the first support level, sitting near $23 to $24. The market-wide backdrop is mixed ahead of the September CPI report, which was due at 8:30 a.m. ET. U.S. equity futures showed little direction. New York Fed President John Williams signaled one more rate hike this year is appropriate but no further tightening in 2027. GME closed Tuesday at $27.22, down 0.04%. In pre-market Wednesday, it jumped $0.50, or 1.84%, to $27.72. The stock doesn't move in a vacuum. None of the macro backdrop changes the fundamental thesis, but it changes the risk-reward calculus significantly. Cohen's $99 million buys credibility for now. It doesn't buy immunity from the next Reddit-driven drawdown or a rejection at the supply zone. He's an insider with material knowledge of the company. Every dollar he spends in the open market tells a different story depending on who's reading it. The institutional investor sees a CEO with conviction. The memestock trader sees a signal to chase. The analyst sees a man with access to information the broader market doesn't have. All three readings are correct simultaneously, and that's what makes GME so volatile. The question is whether a daily close above $28 opens the door to $34 to $36, or whether a rejection sends GME back to retest $23 to $24. Ryan Cohen has real money and a real business on his side. That's not nothing. But he also holds a 10% insider stake in a name that Wall Street will always read through the lens of 2021. The $99 million buys credibility, not control. It buys narrative momentum, not price stability. The fundamentals are genuinely improving, but the technical structure says this rally is running into a wall that has held twice before. Watch the $28 level. Break it cleanly and GME has real legs. Lose $26 decisively and the entire run collapses back to where it started. This isn't about what Cohen says in his filings. It's about what the chart says when the crowd shows up and the supply zone does what it's been doing since late last year. The 57% collectibles revenue growth is a real number. The $650 million EBITDA guidance is a real target. But real numbers in a memestock don't always translate to sustained rallies. They translate to narratives that attract attention, and attention is exactly what the memestock traders want. Trade accordingly. Size positions accordingly. The $26 to $28 supply zone has a memory that outlasts any single quarter of earnings beats. Author bio: Robert Kensington, an overseas entrepreneurial veteran with decades of experience in real-economy industrial investment and expansion. Covers stock market positioning, insider buying signals, and corporate strategy for financial markets readers.
More

Why Ryan Cohen’s $22 Million Bet on GameStop Signals a Dangerous Shift in Market Sentiment

(SeaPRwire) -By: Christian Pierce Retail investors have long been treated as the noisy footnotes in Wall Street’s ledger. The narrative is simple. Pros do the heavy lifting. Casuals chase the hype. Ryan Cohen just flipped that script. He bought 844,130 shares of GameStop. That is a direct personal outlay of $22.8 million. His stake now hovers near 10 percent. This is not a meme trade. It is a strategic repositioning by a known activist. The market didn’t flinch. It cheered. That reaction tells you everything about the current state of institutional confidence. The raw data points are sparse but significant. BlackRock posted a profit beat. Assets under management hit $15.5 trillion. A 15 percent year-over-year climb. For a firm that manages wealth for nations and billionaires, that is steady. It is not spectacular. Bank of America took a hit. Regulators slapped a $1.21 billion penalty on them. A record Treasury action. It was tied to anti-money laundering failures. The stock slipped 1.7 percent in premarket. Meanwhile, chip stocks bled out. ASML beat expectations. They raised guidance. Yet the PHLX Semiconductor Index fell for the fifth straight day. The disconnect is stark. Fundamentals say one thing. Price action says another. Investors are punishing growth stocks regardless of earnings. There is a deeper commercial loop at play here. The inflation report is looming. The Fed’s next move hangs in the balance. Dow futures rose 0.3 percent. S&P 500 futures gained 0.2 percent. The market is in a wait-and-see mode. In this vacuum, speculative capital flows to safe, liquid bets. GameStop offers liquidity. It offers a story. It offers a leader who is actually buying. The $1.21 billion penalty on Bank of America reminds us that regulatory risk is no longer a niche concern. It is a core pricing factor. When a major money center bank faces such a hit, the entire financial sector’s risk profile shifts. Investors are not just hedging against inflation. They are hedging against institutional fragility. The rise in Alibaba’s shares over the $450 smart glasses launch is a similar play. It is cheap tech. It is a narrative with potential upside that does not rely on the fragile AI hype train. The end-game for the industry is a bifurcation of value. We are moving toward a market where activist engagement is treated as a primary driver of stock performance, not just a secondary event. The penalty on BofA signals that compliance costs are becoming a structural drag on bank margins. The weakness in semiconductors, despite strong earnings from ASML, suggests that capital is rotating out of hardware into software and consumer-facing platforms. The $380.7 million settlement for Liquidia is a microcosm of this shift. Litigation risks are being priced in aggressively. Or, in some cases, resolved with quick cash payments to move on. The market is flushing out uncertainty. It is rewarding clarity, even if that clarity comes from a former hedge fund manager buying shares at $27.00. The era of pure fundamental investing, detached from narrative and political maneuvering, is gone. We are now trading in a space where every share purchase by a famous name is a macroeconomic signal. Author bio: Christian Pierce, a chief financial columnist and markets commentator who specializes in dissecting the gap between corporate fundamentals and speculative market behavior.
More

BlackRock Is Not Beating Earnings. It Is Swallowing the Money-Management Business Whole.

(SeaPRwire) - By: Christian Pierce The real story in BlackRock's third quarter is not the earnings beat. It is the quiet death of the middle in asset management. For years, the industry assumed a stable hierarchy. A handful of giants at the top, a broad middle of active managers, and a long tail of boutiques. That structure is collapsing. The middle is being hollowed out, and BlackRock is doing the hollowing. When one firm gathers $205 billion of net inflows in a single quarter, the question stops being whether it beat consensus. The question becomes who is losing the money on the other side of those flows. Competitors watching this print should feel a specific kind of dread. BlackRock is now competing across every channel at once. Passive, active, private markets, cash management, and the software that runs everyone else's portfolios. That is not a product strategy. It is an encirclement. Look at the numbers without the press release gloss. Adjusted EPS came in at $15.93 against a $14.30 estimate. Revenue hit $7.75 billion, up 19% year over year, against $7.43 billion expected. Adjusted net income of $2.62 billion beat the $2.38 billion consensus by a wide margin. Assets under management reached $15.49 trillion, up 15% from $13.5 trillion a year ago. The flow picture matters more. Long-term net inflows were $175 billion. Of that, $135 billion went into ETFs and $66 billion into active strategies. That active figure is the detail worth pausing on. The firm built its empire on iShares, yet it is now pulling serious money into active and systematic strategies too. Performance supports the pitch. About 92% of systematic equity assets and 71% of taxable fixed income assets sat above benchmark or peer median over one year. Adjusted operating margin widened to 47.8% from 44.6%. That 320 basis point expansion at this scale is the tell. Flows at BlackRock's size are supposed to dilute margins through fee pressure. Instead, pricing power held. Over the trailing twelve months, net inflows totaled $869 billion. Technology services and subscription revenue grew 14% to $588 million on Aladdin demand. Performance fees rose to $630 million from $516 million, driven mostly by liquid alternatives. The commercial loop here is elegant and brutal. Aladdin embeds BlackRock inside the plumbing of rival institutions. ETF scale funds the fee war that starves mid-tier managers. Private markets and alternatives capture the high-margin flows that used to belong to specialist firms. Each leg feeds the next. A pension fund that runs risk analytics on Aladdin faces a shorter path to parking assets in an iShares vehicle or a BlackRock private credit fund. This is vertical integration in finance, executed patiently over two decades. The end-game is not hard to sketch. The industry consolidates into two or three full-stack platforms at $15 trillion and climbing, a defended niche of true alpha boutiques, and very little in between. The mid-sized active manager charging 60 basis points for closet indexing has no answer to a competitor growing base fees 11% organically while expanding margins. The stock's 3% premarket pop to around $1,103 understates what this quarter confirmed. BlackRock is no longer a bet on markets rising. It is a bet on the asset management industry itself, and the house now owns most of the table. Author bio: Christian Pierce is a chief financial columnist and markets commentator covering global asset management, capital flows, and the structural consolidation of the investment industry.
More
Microsoft’s $130 Billion Bet: Why the AI Gold Rush Has Moved From Silicon to Concrete Business

Microsoft’s $130 Billion Bet: Why the AI Gold Rush Has Moved From Silicon to Concrete

(SeaPRwire) - By: Reginald Vance The physical limits of compute have always been the hidden crisis in AI. Not the algorithms. Not the models. The sheer weight of copper, concrete, and megawatts required to run them. Microsoft just proved it by signing $130 billion in data center leases in a single quarter — the largest quarterly jump in the company's history. Total unstarted lease commitments now sit at $329.1 billion, up from $196.6 billion in the prior period. Jonathan Neilson called this "a signal of the continued demand strength." He also said these leases will serve demand "for many many years." Translation: the bottleneck was never software. It was always square footage and power draw. Now look at the capital allocation beneath the headlines. Microsoft spent most of 2025 frozen on leasing activity because there simply weren't enough data centers available. Demand exceeds capacity. The commercial backlog is at a record level. That is not a planning problem. That is a physical resource problem. The company is now racing to convert three hundred twenty-nine billion dollars in lease commitments into operational capacity. None of those costs hit the balance sheet until payments begin. So the market sees a stock trading at $543.45, up 0.4%, hovering just below its one-year high of $553.72, with a market value of $4.04 trillion. What the balance sheet does not show is the raw industrial scale required to sustain even a fraction of this pipeline. Barclays raised its price target to $600 from $512. William Blair initiated coverage with an "outperform" rating. Forty-two analysts rate the stock a Buy. The average analyst target sits at $581.80. Meanwhile, insiders sold 143,009 shares worth approximately $71.4 million over the past three months. CEO Satya Nadella moved 86,525 shares at $501.46 on September 1. EVP Amy Hood sold 41,674 shares at $498.27 on September 14. Both sales were pre-arranged. The divergence is telling. Wall Street is pricing in an AI infrastructure supercycle. Insiders are diversifying at $500-plus. Microsoft itself is deploying the Maia 300 custom AI processor to cut inference costs — promising roughly 40% more tokens per megawatt or dollar than leading GPU systems, with multi-gigawatt deployments planned to begin in 2027. That chip is supposed to lower Azure costs, improve margins, and reduce reliance on Nvidia and AMD. A lot of hope pinned on one piece of silicon. Norway fined Microsoft's Xandr unit €8.6 million over Grindr data sharing. The company is carrying out another round of layoffs in Israel. Research chief Peter Lee is leaving for Mercedes' Formula 1 team. Fiscal first-quarter results land October 28, with analysts expecting $4.72 per share on $90.4 billion in revenue. The last report on July 29 showed EPS of $4.74 against a $4.24 estimate, and revenue of $90.01 billion, up 17.7% year over year. The dividend will rise to $0.98 quarterly, paid December 10. Chart-wise, the RSI reads 70.73, sitting right at the overbought line. A daily close above $554 would confirm a new all-time high breakout. A drop below the $505 to $518 zone opens the door to $495 and then $475. Here is the blunt reality: Microsoft is betting the company that physical infrastructure will unlock the next leg of AI profitability. The supply chain for power, land, and construction labor does not expand on command. The vendors who control the bottleneck — not the ones selling chips — will dictate the pace of the entire buildout. Everyone else is just leasing space. Author bio: Reginald Vance is a venture partner specializing in semiconductor valuation and advanced materials, with extensive experience tracking infrastructure-scale capital deployment in the AI compute sector.
More

OpenAI’s Boardroom Bug Was Caught by Its Own AI. That Changes the Insider Threat Game

(SeaPRwire) -By: Oliver Hawthorne The boardroom bug at OpenAI is a corporate espionage story. The real story is about the investigator. OpenAI did not send a security team to sweep the room and then pull a name from a badge log. It used its own models to turn the device into a trail. Security teams use logs, badge swipes and cameras. OpenAI used model output as forensic evidence. That creates the core contradiction: the same systems that power a product can also profile the people who build it. Enterprise buyers will think. Employees will feel the shift. This is not a crime story. It is a product reveal. The company has spent years saying its models help secure the world. Now it can say one of its models caught an insider inside its own conference room. The unspoken part is darker. If the model can reconstruct where a hidden device came from, what else does it see? Now the record. Abdulrahman Alfozan, a Saudi Arabian national, joined OpenAI in July 2025. He was arrested on October 9 and charged with using a device to intercept oral communications. He worked on the product team, according to a person familiar with the matter. OpenAI staff found the device on September 30. Prosecutors say it had been installed two days earlier. It was inserted into a USB port behind a television in an executive conference room. The device was wrapped in toilet paper and encrypted. OpenAI fired Alfozan and alerted the FBI. The company says its own models identified that a specific employee had planted it. Prosecutors say Alfozan used a productivity tool and a chatbot to research sensitive locations at OpenAI. His prompts covered building, customizing, installing, testing and remotely accessing a recorder. He also asked about continuous audio recording and encrypting an SD card. On October 5, he returned to inspect the device. CCTV footage linked him to the scene. That same day, he left a bag unattended in another part of the building. Security opened it and found his wallet, his ID and a second recording device. FBI Director Kash Patel said the alleged goal was to capture sensitive communications about OpenAI’s AI product. OpenAI says there is no sign that model weights, source code or customer data were taken. Alfozan faces up to five years in prison and a $250,000 fine. Now follow the commercial pressure. OpenAI sells trust to enterprises. Its customers need to believe sensitive corporate data is safe inside an API boundary. This arrest gives OpenAI a perfect internal case study. Our models caught an insider before anything left the building. That is a powerful sales asset. But it has a sharp edge. A model that can trace a hidden device can also monitor employee behavior in less dramatic ways. It does not announce itself as a surveillance tool. It just becomes one. No one outside the company knows how the model reached its conclusion. That is part of the problem. The reasoning is proprietary, but the stakes are human. Every employee inside an AI lab now works in a building where the primary eyes might be the product itself. That is the endgame. AI security will be measured by how it handles insider threats, not by benchmark tests. The next bug planter will be caught by pattern drift, not by a camera. The employee who researches how to hide a recorder will leave a trace in model logs. That trace is the new corporate trust. At OpenAI, the watchdog is the model. Author bio: Oliver Hawthorne, a Principal Correspondent permanently stationed at an international technology review.
More
The Hormuz Gamble: Why Tehran Is Betting on Diesel Scarcity and U.S. Voter Pain Business

The Hormuz Gamble: Why Tehran Is Betting on Diesel Scarcity and U.S. Voter Pain

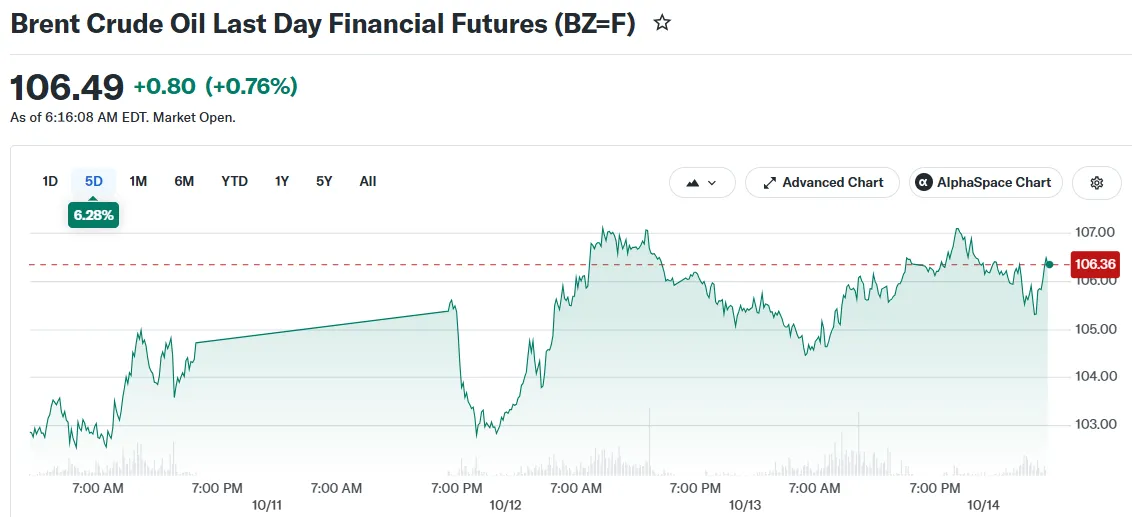
(SeaPRwire) - By: Marcus Sinclair The Strait of Hormuz is no longer just a shipping lane. It is a weaponized pressure valve for Iranian strategy. Recent attacks by Houthi rebels and direct threats from Iranian forces have shifted the risk premium in oil markets. Brent crude surged to $105.83, while WTI climbed to $94.71. This is not merely a reaction to physical damage. It is a calculated move to influence global politics through energy shock. The timing is deliberate. The facts on the ground are stark. A container ship sank after hitting a mine. A tanker and another vessel were struck by unknown projectiles. Simultaneously, Houthi missiles hit an administrative building for Saudi Aramco in Dhahran. The fire was limited, but the message was clear. Riyadh’s airport has already been hit four times this week, killing 13 people. Iran’s Revolutionary Guards Navy confirms the mine incident. They are using new tactics. These changes began about ten days ago. The goal is explicit: keep prices high. This is not a regional dispute. It is a direct intervention in the U.S. election cycle. Iranian officials told Reuters that their new targeting aims to influence the November midterms. Polls show Republican candidates facing backlash over energy costs. By choking supply, Tehran forces a choice. Higher fuel prices undermine voter confidence in the current administration. This is a proxy war fought in the markets, not on a battlefield. The U.S. government knows it. The IEA expects little change in the broader market, but the psychological impact is massive. Washington is reacting. President Trump announced that Russia agreed to supply diesel. The U.S. temporarily lifted sanctions on Russian fuel. However, experts like UBS’s Giovanni Staunovo note that exports from the region have held up so far. Nissan Securities’ Hiroyuki Kikukawa argues that Russian diesel exports should limit sharp price moves. The IEA disagrees, citing a lack of working Russian refinery capacity. The truth is, the supply gap will persist. The U.S. Gulf Coast lost over 60% of production to a hurricane. These factors compound the risk. The end-game is not about oil barrels. It is about political leverage. Iran is forcing the U.S. to choose between domestic stability and foreign policy goals. Every gallon of diesel sold at a premium in American markets erodes support for the current leadership. The Houthi attacks in Yemen support Saudi forces in retaking Bab el-Mandeb territory, but the focus remains on Hormuz. The sinking of one ship is a small event. The sustained threat is the real weapon. If the mine-laying continues, the insurance costs will spike further. Voter sentiment is now a geopolitical variable. The midterms are not just a domestic event. They are a global battleground. Iran’s strategy is working. Oil prices are sticky. The U.S. inflation report due today will reflect this pressure. Expect the U.S. government to push for more sanctions relief on Russian fuel. It will not solve the structural shortage. The real cost will be paid by American consumers. The strategic calculation is clear. Keep the pressure on. Force the hand of Washington. The next move will come from Tehran, not the White House. Author bio: Marcus Sinclair, a Senior Fellow at a prominent European geopolitical and security think tank, specializing in energy security and proxy conflict dynamics.
More

ASML Said Demand Exceeds Supply. It Did Not Mention It Cannot Build Enough Machines.

(SeaPRwire) - By: Ethan Gallagher Here is what nobody repeated after the earnings call. ASML customers are placing orders for 2029 and 2030. Christophe Fouquet stood at the podium and said planned supply for 2027 and 2028 will not fully meet demand. He said the company is exploring ways to go beyond its planned 30% capacity increase in 2028. He did not say how. No European lithography equipment maker has ever executed a 30% capacity ramp on schedule, let alone beyond it. Optical systems. Laser sources. Precision stage motors. Every component sits behind a multi-year supply chain that does not open for negotiation. The stock rose 1.6% in premarket. Wall Street heard "third guidance increase" and tuned out "we cannot physically build enough units." Those are two different stories. Only one of them holds when 2028 arrives. The company raised 2026 net sales guidance to €44 billion to €45 billion. That is the third adjustment this year. Q3 net sales hit €11.66 billion. Net income reached €4.96 billion. Analysts had penciled in €4.13 billion. Gross margin expanded to 57.5% from 54%. Full-year margin guidance sits around 56%. Fouquet confirmed customers keep raising equipment demand forecasts. He tied it to the scale and duration of AI-related investments. Strip the revenue lines and look at what is actually moving. Jefferies said the 2027 and 2028 increase was broadly expected. They see sector multiples contracting further. The stock gaining 1.6% on the news is not a repricing event. It is a confirmation of consensus. Didier Scemama at BofA caught what the revenue table hides. He estimates a 5% rise in average selling prices could lift earnings per share gains to around 10%. That is the variable that matters. Demand has never been ASML's constraint. Pricing power is. The company holds a single point of leverage over the entire semiconductor manufacturing stack. TSMC needs EUV. Samsung needs EUV. Intel needs EUV. They are all in the same room and none of them can walk. When a supplier's customer list shrinks to two names, pricing is not a negotiation. It is a menu. ASML has never had that kind of leverage before, and no one on the street is modeling what happens when it gets exercised. ASML expects China to make up about 20% of 2026 sales. It made the same forecast for 2025 and ended up near one third. That miss was 50%. CFO Roger Dassen called the proposed Match Act a bad idea. He said it would speed up China's own domestic technology work. The bill would ban DUV lithography sales to China and cut off servicing for machines already installed there. China accounts for roughly 70% of ASML's DUV immersion unit sales by volume in recent years. Read that number again. 70%. If the Match Act passes, ASML loses nearly three-quarters of its DUV immersion revenue overnight. That is not a tailwind risk. That is a revenue cliff. Dassen's opposition is not ideological. It is arithmetic. The Match Act is a binary event. If it passes, the 20% China forecast becomes a lower bound and actual sales could fall faster than anyone models. If it fails, ASML keeps selling to the world's second-largest chip market with no regulatory drag. The asymmetry is enormous. Fouquet's bullish demand narrative through 2030 assumes China remains open. The entire growth thesis collapses on one congressional vote. Scemama carries a Buy rating and a $2,915 price target on the ADRs. They traded around $1,703 on Tuesday. That is 70% upside in a market where consensus is "broadly expected." Either he sees something the market does not, or the market sees something he does not. I have spent years watching hardware supply chains break on promises that sounded certain on earnings calls. The EUV supply chain is not a startup pipeline. It is an industrial system with fixed physics. EUV laser cavities take longer to build than a commercial aircraft program. Zeiss' optics division cannot print lenses overnight. The real bottleneck is not 2026 guidance. It is whether ASML can translate paper orders into metal by 2028. Until that answer is proven in the supply chain, not in a guidance range, the stock is pricing optimism as fact. The Match Act is a coin flip that no one in the room at Eindhoven wants to talk about on speakerphone. Author bio: Ethan Gallagher, a Silicon Valley hardware architect and infrastructure strategist with over fifteen years analyzing semiconductor supply chain dynamics, lithography equipment scaling, and the collision between industrial capacity limits and capital market expectations.
More