Micron’s $35 Billion Buyback Promise Hits a December Wall: Why the Chip Giant Can’t Spend Its Way Back to All-Time Highs

(SeaPRwire) - By: Reginald Vance Micron just handed shareholders a $35.16 billion check they cannot cash for nearly a year. The market understood the message immediately. Shares fell 3.88% on Monday despite fiscal fourth quarter revenue hitting a record $54.23 billion, up 379% from a year earlier. That tells you everything you need to know about semiconductor cycle psychology. Investors do not buy announcements. They buy certainty. And Micron's board has built a ceiling of repurchase authority with no expiration date and absolutely no deployment requirement to back it up. The raw numbers are staggering. GAAP net income for fiscal 2026 came in at $84.97 billion. Adjusted free cash flow for the quarter ended September 3rd hit $33.2 billion. Non-GAAP earnings per share reached $33.42 with an 87% gross margin. Full-year revenue landed at $133.19 billion compared to just $37.38 billion a year prior. Yet Micron spent only $650 million on share repurchases throughout the entire fiscal 2026 year. That bought back 2.5 million shares. The prior program ran from zero to $2.66 billion annually. The new authorization adds $33.03 billion on top of the $2.16 billion still remaining under the 2018 plan. That is a different animal entirely. But none of it matters on day one. CHIPS Act funding agreements explicitly bar any repurchases until December 9, 2026. So the clock starts ticking before any capital actually flows back to shareholders. What divides those figures from real buying power is something nobody is talking about loud enough. Micron is spending massively to add capacity for high-bandwidth memory. That is the product that powers AI systems. The cash flow war between buybacks and capex is not theoretical. It is happening right now on the balance sheet. Rosenblatt analyst Kevin Cassidy expects the board to keep raising the authorization through fiscal 2027 as quarterly free cash flow builds. DA Davidson analyst Gil Luria pushed his target all the way to $3,000 from $2,100, arguing investors will pay a higher multiple once they fully understand the company. The broader consensus among 28 analysts shows 27 Buy ratings and one Hold, with an average target of $1,621.67 implying roughly 58% to 64% upside from current levels. The stock still trades about 18% below its June 25 high of $1,255. The endgame here is simpler than the press release suggests. Semiconductor foundry capacity and advanced packaging are the real scarcity plays. Buyback announcements are accounting theater until the CHIPS restriction lifts and management commits real dollars. Until December 9, the market will price this as a promise, not a purchase order. Micron's shareholders should watch free cash flow conversion rates and HBM ramp percentages far more closely than they watch the authorization headline. One tells you what the business is actually doing. The other tells you what the board hopes it can do. Author bio: Reginald Vance is a venture partner specializing in semiconductor valuation and advanced materials, with two decades tracking capital allocation in the memory chip cycle.
More

Wall Street’s Tokenization Dream Hits the Brutal Wall of Zero Supply

(SeaPRwire) -Here is the part of the Morgan Stanley tokenized-asset announcement that almost nobody is discussing. The bank projects a $3 trillion to $10 trillion market by 2030. It also pushed its own tokenized-equity trading platform to Q1 2027, a full six months past its original target. When Amy Oldenburg, the bank's head of digital asset strategy, was asked why, she gave one of the most honest answers in recent financial-sector history. She said the products simply do not exist yet. You cannot trade an asset that has not been issued. Client demand is limited because there is nothing to buy. That single sentence changes how you read every headline coming out of TOKEN2049. The market is watching DTCC's planned tokenization service launch at the end of October. The GENIUS Act takes effect in January. The Clarity bill died. Morgan Stanley is quietly building its Digital Asset Lab, testing tokenized deposits, money-market funds, and DeFi vaults. The OCC granted preliminary conditional approval for the Morgan Stanley Digital Trust on June 18, a proposed national trust bank requiring $50 million in tier 1 capital to handle digital custody, fiduciary staking, and collateral administration. All of that is infrastructure work. None of it is a product. The gap between forecast and factory floor is where this story actually lives. Citi's September 24 research, prepared with The ValueExchange, found that 77 percent of financial institutions expect to use some form of tokenized collateral in 2026. Large institutions manage roughly $74 billion in collateral daily across about 65 custody locations. About 25 percent of that collateral sits idle or serves as extra buffer, costing roughly $346 million in lost income each year for large firms. Nearly 60 percent of global margin is held in cash earning no yield. The economic case for tokenization is real. The sequencing problem is brutal. Nobody issues tokenized assets until they see demand. Nobody demands tokenized assets until they see supply. Oldenburg named private shares, structured notes, custom products, and private fund access as near-term opportunities where blockchain could cut paperwork and administrative overhead. Tokenized holdings could serve as collateral once enough assets exist. This is a coordination trap dressed as a growth thesis. DTCC said more than 30 firms participated in its July 15 production transactions, covering securities lending, collateral pledges, equity transfers, and U.S. Treasury repurchase agreements across its private Besu network and the public Canton Network. The service follows a December 2025 SEC no-action letter. HashKey became the first Asian digital asset provider in DTCC's working group on September 2, joining JPMorgan Chase, Goldman Sachs, Nasdaq, and the NYSE. The network effects are building. The products are not. Here is what the tokenized-asset cycle actually looks like from the inside. First comes the projection, loud and optimistic. Then comes the delay, as banks realize infrastructure takes longer than quarterly earnings calls allow. Then comes the quiet build, labs, trust charters, production testing away from the keynote stage. Then comes the first real product launch, slow and unglamorous. Then comes the nonlinear adoption curve, once settlement actually works. This cycle repeats for every asset class. Real estate tokenization will follow. Private credit will follow. Insurance-linked notes will follow. Each one will hit the same wall. DTCC is the chokepoint. It controls the settlement layer for most U.S. institutional trades. If its tokenization service ships correctly by late 2026, every major bank routes through it. If it stumbles, the market fractures into competing rails. The firms that control the rail control the revenue stream. Everything else is marketing. The GENIUS Act will matter more than most commentators admit. Stablecoin regulation creates the on-ramp for institutional dollars. Without it, tokenized assets stay a niche experiment. With it, they become a compliance decision. The difference between those two outcomes is measured in trillions. Oldenburg's remark that the bank needs a little more time is the entire story compressed into five words. Wall Street is not late because it lacks vision. It is late because building institutional-grade tokenization infrastructure is hard, slow, and deeply unglamorous. The $3 trillion to $10 trillion forecast is directionally sound. The timeline is not. Expect another delay. The first real tokenized equity product will likely land somewhere between late 2027 and mid-2028, not 2027. The market will call it a miss. The institutions will call it prudent. Both sides are right. The firms that win here are not the ones with the biggest press releases. They are the ones with the deepest custody licenses, the strongest regulatory relationships, and the patience to wait for actual product-market fit. Morgan Stanley is playing that game. So is DTCC. So is Citi. The rest is noise, and the noise is very loud right now. Author bio: Logan Pierce is an independent business researcher and corporate governance writer on Medium.
More
Ethereum’s Silent Pivot: Why Tom Lee’s “Biggest Bull Market” Thesis Hides a Fragile Floor Business

Ethereum’s Silent Pivot: Why Tom Lee’s “Biggest Bull Market” Thesis Hides a Fragile Floor

(SeaPRwire) - By: Oliver Hawthorne The disconnect between narrative and price action defines the current state of Ethereum. Tom Lee is calling for the largest crypto bull market in history, citing generational wealth transfer and AI downstream applications as primary drivers. Yet, on the Binance ETH/USDT chart, the asset is stuck. It bounced off a low near $2,410 and is now hovering around $2,529. The market is flat. It is not accelerating. Lee’s thesis assumes a structural shift in capital flows that hasn't yet materialized in the order book. He points to digital asset treasuries and tokenization. These are long-term arguments. The immediate reality is a stalemate. Traders are waiting for a breakout that simply isn't there. The optimism from BitMine’s chairman clashes with the inertia of the daily chart. Let’s look at the hard data behind the hype. BitMine Immersion Technologies bought 12,532 ETH last week. This purchase pushes their total holdings to 6.028 million ETH. They are close to their 5% supply goal. Lee states the company will stop buying once that target is met. That ends a significant source of demand. Despite this, BitMine sits on over $4 billion in unrealized losses. Meanwhile, the institutional flows tell a different story. US spot Ethereum ETFs saw $542.2 million in net outflows between Oct. 5 and Oct. 9. That is nine straight days of withdrawal, totaling $697.4 million. BlackRock’s ETHA led the charge with $201.9 million in outflows on Oct. 6 alone. The liquidation data adds pressure. Roughly $58 million in positions were liquidated over the last 24 hours. Longs accounted for 64% of that total. The market is shaking out weak hands. The technical structure reveals a battle for control, not a clear path forward. Analysts Ted Pillows and Michaël van de Poppe both identify the $2,560 to $2,575 zone as the critical ceiling. ETH failed to hold above this level. It sits below the 20-day moving average at $2,640 and the 50-day moving average at $2,558. The RSI is near 42 on the daily chart, indicating momentum is neutral-to-weak. Van de Poppe expects ETH to outperform Bitcoin soon. But he admits the asset needs to show more strength first. Ash Crypto argues the bulls are in control because ETH held above the weekly 50-period moving average for four weeks. That is a long-term view. The short-term view is constrained by resistance. CoinGlass data shows liquidation clusters just above the current price near $2,585 and $2,635. Below, support holds at $2,480 and $2,410. If ETH clears $2,575, the path to $2,700 opens. If it fails, the next support test is imminent. The commercial loop here is delicate. Lee argues that the generation inheriting wealth has higher risk appetite. He notes that digital asset treasuries were not a factor in the 2019–2021 cycle. That is a valid structural point. However, the current market is not behaving like a typical bull run. It is behaving like a consolidation phase with heavy overhead resistance. The outflows from ETFs suggest institutional patience is thin. BitMine’s buying power is capped by its 5% goal. Once they stop, the volume support drops. The market needs a catalyst beyond treasury accumulation to break the $2,575 resistance. Until then, the "biggest bull market" narrative remains a theoretical upside. The price is telling the truth: stagnation. Traders are not chasing strength. They are waiting for a clear signal. Until ETH closes decisively above $2,575, the bearish sentiment from ETF outflows and liquidations will keep the asset capped. Author bio: Oliver Hawthorne, a Principal Correspondent permanently stationed at an international technology review.
More
Bitcoin’s $83K Rebound Is a Mirage Unless CPI Bails It Out Business

Bitcoin’s $83K Rebound Is a Mirage Unless CPI Bails It Out

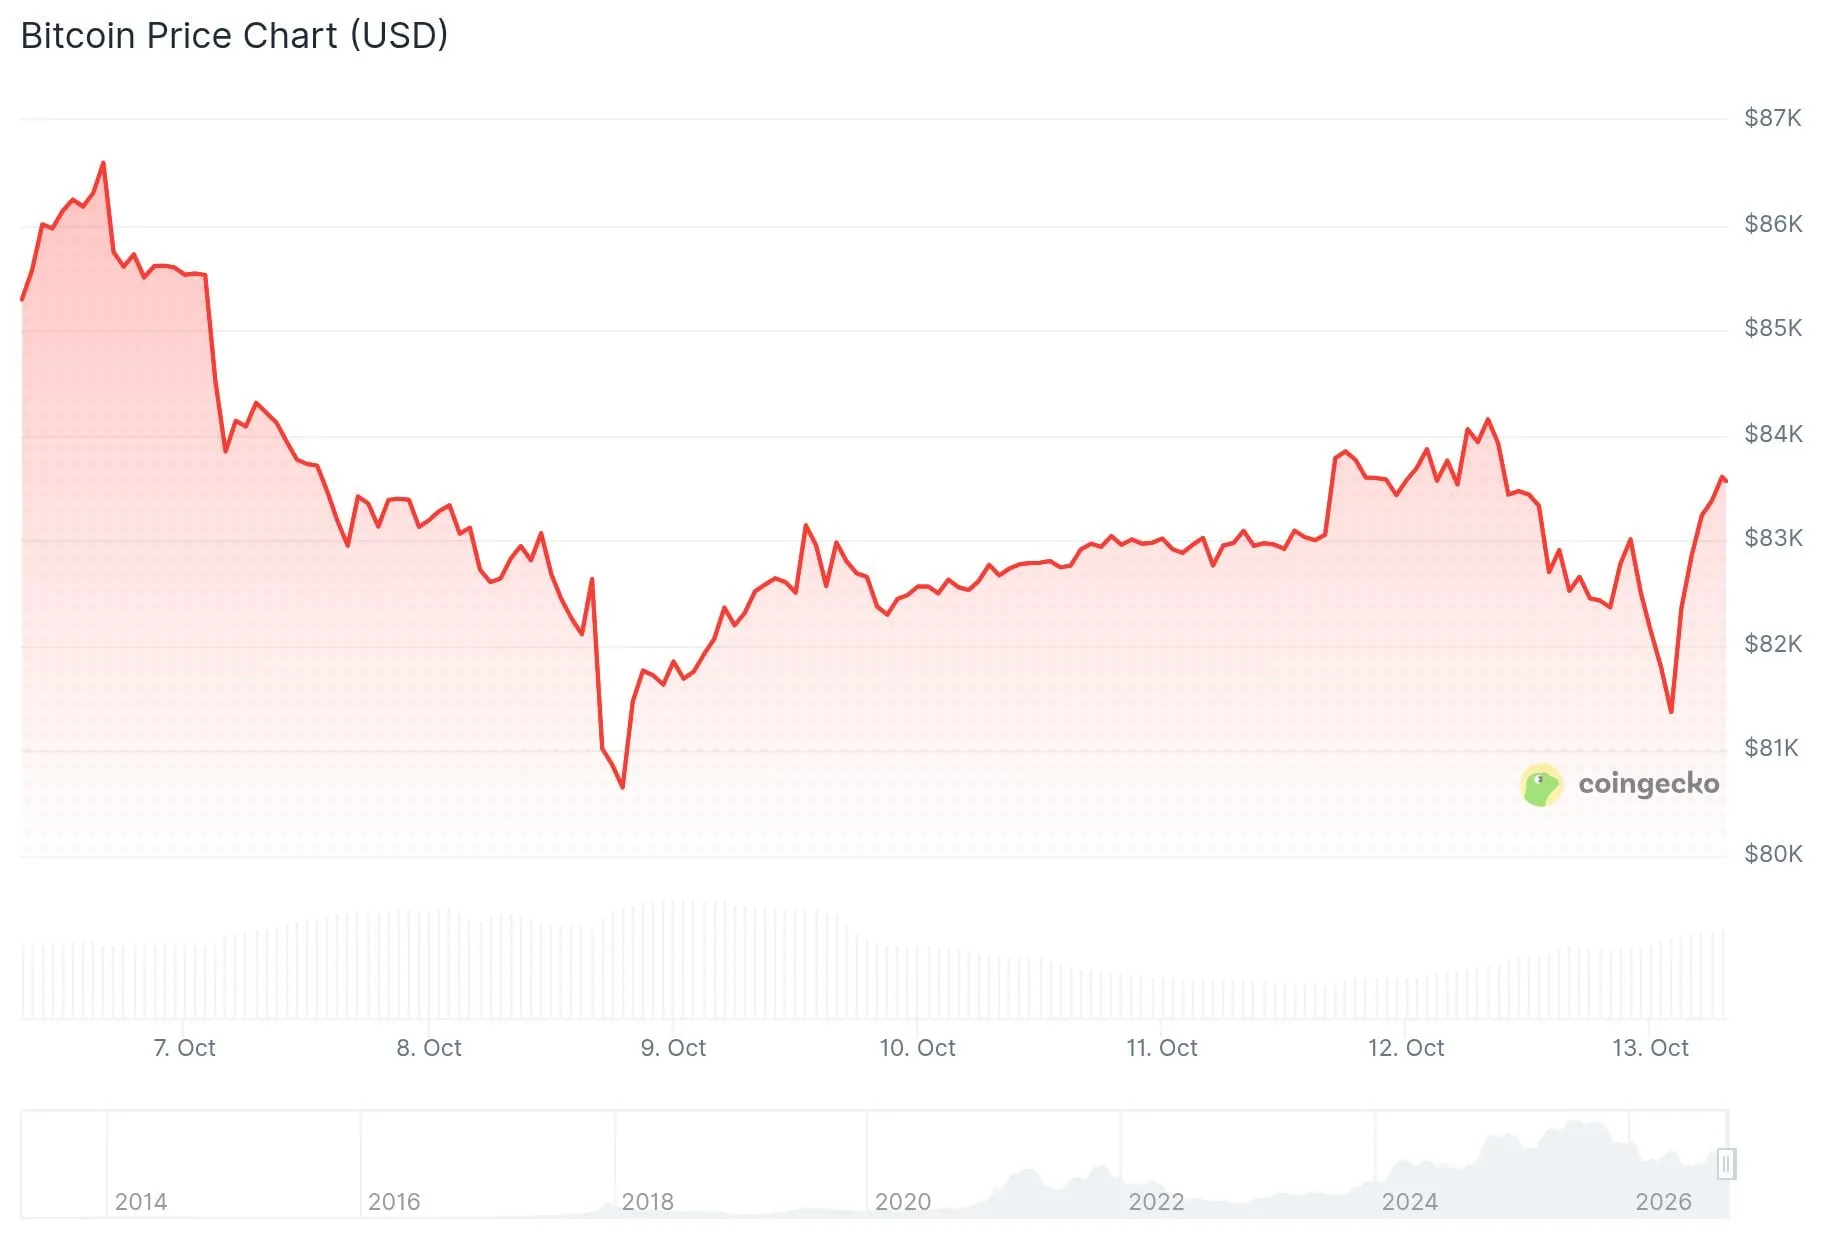
(SeaPRwire) - By: Christian Pierce There is a nasty game of tug-of-war happening right now, and Bitcoin is the rope. On one side you have a brutal selloff in Asian chip stocks, a KOSPI that collapsed more than 6% intraday, and WTI crude parked near $92.67. On the other side you have Michael Saylor’s relentless dip-buying machine and a market that refuses to give up the gains from the May breakout. On Tuesday, Bitcoin fell to just under $81,000 at 00:50 UTC, then snapped back above $83,000. That feels strong until you remember the last time we saw this kind of intraday recovery, it was followed by a slow bleed in ETF flows. The problem isn't the daily candle. It's the $681 million that walked out of spot Bitcoin ETFs in the week to October 9. That was the worst weekly outflow since late June, and it ended a three-week streak of inflows. You don't get a clean trend with that kind of money moving out. Let's put the facts on the table. Samsung Electronics and SK Hynix each fell about 8%, extending losing streaks to five sessions. That dragged the KOSPI to its lowest level since late July. The Hang Seng slipped 0.4%, and Nasdaq futures pointed lower by 0.6%. So the risk-off tone is not a crypto-only story. Oil stays high, Brent hovering near $106 a barrel, after attacks in Saudi Arabia and threats around the Strait of Hormuz. High energy prices feed inflation, which keeps the Dollar Index strong at 102.50. That is a headwind for every risk asset, not just Bitcoin. Meanwhile, Strategy bought another 250 BTC for roughly $21.5 million between October 5 and October 11, at an average price of $86,194 per coin. That is above the current spot price of around $83,530. They now hold 848,250 BTC, worth roughly $70.6 billion, with a reported average cost basis of $75,444. On the technical side, analyst Daan Crypto Trades noted that Bitcoin closed its latest weekly candle above the May highs. That is a useful line in the sand. As long as that holds, the trend looks intact. But he also pointed to the bull market support band as the first level to watch if a larger drawdown occurs. That band is rising about 1% per week. The real question is whether institutions share his patience. The commercial loop here is quite simple. Spot ETF outflows tell you that profit-taking happened after a strong September quarter. The inflows are not continuous. So when you see a bright bounce like Tuesday's, you have to ask who is buying. Strategy bought 250 BTC. That is a single corporate conviction bet, not broad market demand. Market makers like Wincent are apparently telling their clients to hedge exposure ahead of Thursday's US CPI report instead of cutting core positions. That is classic positioning before a binary event. The current rebound is therefore not a new bull narrative. It is a leveraged pause before inflation data. If CPI comes in hot, oil at $106 and the dollar at 102.50 will crush the $83,000 level. If it comes in cool, the May highs hold as a floor and the next leg up starts from a higher low. Do not overthink this. The recovery to $83,530 was built on thin liquidity and a single whale-sized corporate purchase. Watch Thursday's number. If it disappoints, the support band becomes the only thing between you and a real drawdown. Author bio: Christian Pierce, chief financial columnist and markets commentator with a decade of experience dissecting macro capital flows and institutional positioning.
More

A Double Upgrade That Admits Defeat: Why Wall Street Got Salesforce and AI Completely Wrong

(SeaPRwire) - By: Oliver Hawthorne Here is the uncomfortable part nobody at BofA wants to say out loud. The bank just moved Salesforce from Underperform straight to Buy, skipping a notch, and lifted its price target from $160 to $285. The stock responded instantly, trading near $237 in Monday's pre-market, up roughly 3.5% from Friday's close of $229.13. But the real story is not the upgrade. It is the confession buried inside it. Back in May, BofA's bearish case rested on a fashionable thesis, that AI would eat Salesforce alive. The fear was simple enough. Why pay for seats of enterprise software when an AI agent can do the work? That logic sounded smart at dinner parties and on conference panels. Then the analysts actually did their homework. They called CTOs at major companies and asked the question directly. Would you rip out Salesforce? The answer came back almost unanimous. No. Replacing those platforms is highly unlikely, the CTOs said, because they hold business logic, data pipelines, workflows, and compliance frameworks that are brutally hard to move. This is the industry's central anxiety exposed. Everyone predicted AI would kill the incumbent SaaS giants. Nobody bothered to ask the people who would actually sign the migration order. Now look at the numbers behind the reversal, because they matter more than the rating itself. Salesforce's AI-related annual recurring revenue crossed $1.5 billion in the most recent quarter, driven largely by the Agentforce platform. That is not a press release vanity metric. That is real money customers are committing to AI built inside the system they already own, not AI bought to replace it. The August 26 earnings print told the same story. Earnings per share landed at $5.90 against an estimate of $3.27. Revenue grew 10.8% year over year to $11.35 billion, edging past the $11.33 billion consensus. The company guided fiscal 2027 EPS to a range of $16.67 to $16.71 and paid a $0.44 quarterly dividend on October 8, a 0.8% yield. Wall Street's posture was already tilted positive before BofA moved. MarketBeat counts three Strong Buys, 30 Buys, 14 Holds, and three Sells, with a consensus target of $275.14. BMO went to $285 in mid-September, Argus to $300 in late August. Even the insider tape is split in an interesting way. Director Craig Conway sold 4,500 shares on September 4 at $260.61, while Director David Blair Kirk bought 4,176 shares on September 18 at $239.33. Institutions hold 80.43% of the float. So what is the actual commercial loop here, and where does it end? The loop runs like this. Salesforce owns the system of record. The data, the workflows, the compliance scaffolding all live inside it. AI agents only become useful when they can act on that data safely and with context. Which means the agent layer does not replace the system of record, it depends on it. Every CTO BofA interviewed understood this instinctively, because they are the ones who would carry the risk of a failed migration. The market is slowly pricing in the same realization. The stock trades above its 50-day average of $225.66 and far above the 200-day at $192.67, still below the 52-week high of $269.11, with a market cap of $188.03 billion. Wednesday's September CPI report could shake the rate-sensitive tape short term, but it does not touch the structural argument. My read is blunt. The end-game in enterprise AI is not a graveyard of legacy SaaS vendors. It is a toll booth model, where the incumbents who own the data layer collect rent on every agent that runs through it. Watch the migration pipeline, not the demos. The first Fortune 500 company that actually rips out its CRM for a pure AI stack will be the real signal. Until that happens, the bears are arguing with a customer base that has already voted.
More

Snap’s $2,200 Glasses Are Bleeding Cash. An Activist Just Demanded the Board Stop Pretending Otherwise.

(SeaPRwire) - By: Maxwell Vance Snap's board received an open letter from Blue Duck Capital on Tuesday. The message was blunt. The company was quietly burning half a billion dollars a year on Specs without a funding plan that made sense. Blue Duck's solution was simple. Sell a 20 percent stake in the Specs division for one billion dollars. Keep 80 percent ownership. Ring-fence the losses. Snap's shares climbed six percent to near $6.26 on Friday, even as the communication services sector fell one percent across the S&P 500. Volume was thin though. Roughly 13.8 million shares changed hands, about 70 percent below the average daily volume of 45.4 million. This was not a broad institutional conviction trade. It was a speculative pop on a headline. Let me lay out the capital structure argument, because the math tells you everything you need to know about why this fight is happening. Specs costs approximately $500 million per year to develop. Two years of runway requires one billion dollars. Blue Duck's proposal would value the unit at five billion dollars based on that 20 percent stake. That leaves Snap still firmly in control with the majority position intact. The firm also flagged SpaceX as a potential strategic investor, citing possible AI and Starlink connectivity links. Separately, Blue Duck projects Snap's core advertising and subscription business could produce nearly $2 billion in adjusted EBITDA by 2027. That projection is the backbone of the thesis. But the core business numbers are not the only thing that matters here. What happened in the months leading up to this letter is more telling than any activist proposal. Over the past 90 days, insiders sold 2,445,926 shares worth roughly $13.4 million. The largest single transaction came from CTO Robert Murphy, who offloaded two million shares at $5.55 on August 5. That is not noise. That is a signal from someone who knows the balance sheet inside out. Meanwhile Snap announced enterprise partnerships with NVIDIA, Salesforce, and Amazon Web Services in September, pushing the $2,195 Specs glasses toward workplace deployment. The company said it would use NVIDIA's XR AI technology to build agents processing live camera and microphone inputs. You do not need a crystal ball to see the contradiction. The board was publicly hyping enterprise expansion while the CTO was privately cashing out. Those two narratives cannot coexist indefinitely. Blue Duck's letter forces the board's hand in a way that public relations cannot mask. Raising external capital for Specs separates the hardware burn rate from the ad business. It also creates a clean valuation benchmark that Wall Street currently refuses to apply. The consensus rating among 30 covering analysts remains Hold. Price targets cluster between $5.25 and $16, with averages around $7.32 and $7.65. Blue Duck's $12 to $14 target is speculative, yes. But the fact that an outside investor is willing to put a number on it at all highlights the market's discomfort with the current ambiguity. Snap reports earnings on November 4. Analysts expect 16 cents per share on $1.73 billion in revenue. The stock trades above its 20-day SMA at $5.63, its 50-day SMA at $5.48, its 100-day SMA at $5.25, and its 200-day SMA at $5.59. Resistance sits at $6.26. Support at $5.59. A break above resistance could extend the rally. A drop below support would weaken the recovery case significantly. The supply chain for this kind of hardware pivot is unforgiving. Snap needs NVIDIA, Salesforce, and AWS to commit real engineering resources, not just logos on a press release. It needs SpaceX to move beyond being a named possibility in an activist letter. And it needs the board to stop treating Specs as a hidden line item while insiders harvest exits at $5.55. The fundamental question is not whether Specs will succeed. It is whether Snap can fund the thing without subsidizing it with ad revenue that shareholders are already reluctant to trust. Blue Duck just handed the board a clean structure. The only thing left to see is if they take it. Author bio: Maxwell Vance is a hedge fund manager specializing in distressed asset acquisition and proxy fights, with 15 years of experience in corporate governance and activist-driven restructuring.
More

A $100 Fine-Tune Just Embarrassed Frontier AI — Coinbase’s Fraud Model Is the Wake-Up Call Silicon Valley Didn’t Want

(SeaPRwire) -By: Nathaniel Cross Strip away the press release polish and the Coinbase result reads like an indictment of the frontier-model business model. The company took Qwen3.5-9B, an open-weight model with nine billion parameters, fine-tuned it on proprietary fraud records, and beat Anthropic's Opus 4.5 at its own game. The F1 score improved by 9.6 percentage points. Training ran on a single GPU. Total cost, under one hundred dollars. Meanwhile Opus, a model backed by billions in compute and capital, missed more fraud on the same test set. Brian Armstrong posted the result on October 11, framing it as a pattern he expects to repeat inside enterprises. He is right to frame it that way. But the framing deserves harsher scrutiny than the celebration it received. This is not a story about one clever fine-tune. It is a story about who actually owns the intelligence in enterprise AI, and the answer is shifting away from the model labs. Look at the technical architecture first, because the design choices matter more than the benchmark. The Coinbase AI Agent does not judge transactions in isolation. It reviews sequences of recent payments, which lets it catch behavioral patterns that per-transaction classifiers miss. The test covered 16,140 transactions across 7,293 users, with 813 confirmed fraud cases. In a live online experiment, the system cut fraudulent transactions by 30% and fraudulent transaction value by 22%. Latency tells the sharper story. The fine-tuned model answered in 0.683 seconds per request. Opus 4.5 took 1.515 seconds. That is a 55% lower median response time, measured in production, not in a demo. For payment review, where every hundred milliseconds costs conversion, this gap is not academic. It is revenue. Now the uncomfortable part, the part the announcement glosses over. The official claim is that specialized small models beat general frontier models on narrow tasks. True, and proven here. The subtext is about data monopoly. Coinbase's advantage was never the model. Qwen3.5-9B is open weight; anyone can download it tonight. The moat is the historical fraud corpus Coinbase spent a decade accumulating, labeled, and legally entitled to train on. Armstrong says we will see more of this pattern inside companies. Correct, but only inside companies that already hold proprietary labeled data at scale. A fintech startup without that corpus gets none of this benefit. The fine-tune costs a hundred dollars. The data asset behind it is priceless and non-transferable. Frontier labs lose inference revenue; incumbent data owners consolidate power. One monopoly gets swapped for another, quieter one. There is also a governance layer worth watching. The agent returns risk classifications only. Application code applies the actual transaction decisions. It could stop a payment that passed earlier checks, but it could not reverse an existing block. CertiK warned last week that autonomous agents need clear limits and human accountability, and Coinbase's asymmetric permission design shows that warning landing in production. Add Vitalik Buterin's caution about AI and wallet security, and the pattern is clear. The industry is deploying agents fast while bolting on guardrails opportunistically. My prediction is clinical: within eighteen months, every serious payment platform will run fine-tuned open-weight models on private data, frontier API spend on fraud workloads will collapse, and the labs will respond by trying to buy or license the very proprietary datasets that made them obsolete. Author bio: Nathaniel Cross is a former Lead AI Research Scientist and decentralized protocol pioneer who writes on machine learning infrastructure, model economics, and the shifting balance of power between AI labs and data owners.
More

CFTC’s Hidden Authority: Why Crypto Regulation Is Already Here

(SeaPRwire) -By: Elena Rostova Caroline Pham did not say the CFTC needs new permission from Congress. She said it already has the authority. The gap between public understanding and legal reality is the core problem. Most market participants assume regulators must wait for legislation. Pham rejects that delay. She argues existing statutes are broad enough to cover almost everything except onions and movie box office receipts. This is not a proposal. It is a claim of current jurisdiction. The CFTC can regulate most crypto activity without waiting for new laws. The Commodity Exchange Act serves as the legal foundation. Pham notes its principles-based rules accommodate products that did not exist when lawmakers drafted the text. She cited derivatives linked to artificial intelligence computing capacity as a specific example. This flexibility allows the agency to expand oversight beyond traditional futures markets. The CFTC recently proposed new federal rules for leveraged retail crypto trading. These measures aim to improve investor protection. They offer a federal regulatory route instead of relying solely on separate state licensing systems. Pham linked these proposals to the Crypto Sprint initiative she launched in 2025. The goal is to place leveraged retail transactions on regulated exchanges. This provides stronger safeguards than the current patchwork of rules. The distinction between tokenized deposits and stablecoins is critical for compliance. Pham argued that settling an entire trading day instantly would require about $15 trillion in cash. Tokenized bank deposits better suit transactions where banks offset obligations before transferring outstanding balances. Stablecoins remain useful for direct payments between parties lacking mutual trust. She expects major US exchanges to introduce genuine tokenized stocks with shareholder rights within two years. This differs from synthetic products without issuer authorization. An October 6 report described plans for a tokenized stock market involving OKX and Intercontinental Exchange. Pham also predicts renewed interest in NFTs as customer loyalty tools, similar to airline miles. The regulatory framework must distinguish between authorized shares and unapproved tokens. Regulators will not wait for a comprehensive Clarity Act to move forward. The CFTC is building a compliance structure around existing commodities law. Firms must map their products to the Commodity Exchange Act definitions immediately. If your asset fits the description of a commodity, you are already in scope. Legal counsel needs to review position limits and disclosure requirements under the new Regulation CTX and CAM proposals. The era of ambiguity is ending. Action now is cheaper than litigation later. Author bio: Elena Rostova, a public policy expert specializing in compliance assessments for governments or sovereign wealth funds.
More

Sui’s $30M Bet on AI Data: The Infrastructure Play Everyone Is Missing

(SeaPRwire) -By: Ethan Gallagher Let’s cut the PR fluff. This is not a marketing stunt; it is a structural realignment. Sui Foundation is dropping $30 million into DATA Network, becoming the largest institutional holder. They are not just buying tokens; they are buying the plumbing for the next generation of AI training. The move signals that L1 chains are shifting from speculative assets to utility providers for high-value data logistics. If you think this is just another "AI token" rally, you are reading the surface. You are missing the infrastructure layer where the actual value is accumulating. The official release states the facts clearly. DATA tokens will migrate to Sui on a one-to-one basis. Governance rights and vesting schedules remain intact. Walrus becomes the default storage platform for encrypted original training files. The numbers are robust: over 250 million registered contributions and an average of 3 million receipts processed daily. PIP Labs and DATA Foundation keep their stakes. Sui Foundation takes the top spot. The timing is precise, following Sui’s recent offchain speed test that recorded 40.6 million transactions per second. This is not accidental. It is architectural. Now, look at the subtext. The industry whispers about "data silos," but this deal breaks them. By integrating Trace, the registry that tracks data origins and usage permissions, Sui is creating a verifiable supply chain for AI data. It’s not just about storage; it’s about consent and provenance. The partnership with Samsung Wallet for USDC integration on Sui, reaching 82 million devices, adds another layer. This is not just for AI labs. This is for mass adoption. When you combine the speed of Sui’s payment channels with the integrity of Trace’s data tracking, you have a closed loop. Data enters, value is exchanged, consent is verified. No middlemen. No opacity. Just hard infrastructure. The supply chain landscape is shifting from hardware to data integrity. We spent the last two years obsessed with GPU scarcity. Now, the bottleneck is trustworthy training data. Sui and Walrus are building the audit trail. Anyone claiming to have "clean" data will need to prove it on-chain. The blunt reality? If your AI model cannot trace its training sources back to a verified on-chain receipt, it is a liability, not an asset. The market will price in this verification cost. Those who build on Sui’s infrastructure will have a structural advantage in regulatory compliance and model safety. The era of unverified data dumps is over. The era of auditable, on-chain data provenance has begun. Pick your side. Author bio: Ethan Gallagher, a Silicon Valley Hardware Architect and Infrastructure Strategist specializing in decentralized data logistics and on-chain verification systems for large language models.
More

Micron’s $3,000 Dream Hits the $1,100 Wall: What the Buyback and the Contracts Really Say

(SeaPRwire) - By: Reginald Vance Micron's shares sit at $1,029. They have climbed more than 260 percent this year. Wall Street is shouting $3,000 targets from every research desk. The stock cannot break $1,100. That gap between the price the street demands and the price the market will pay is where the real story lives. Investors are not confused by the upside. They are confused by the resistance. And confusion is where capital gets trapped. The numbers behind Micron's bullish case are concrete. D.A. Davidson's Gil Luria raised his target to $3,000 on October 7, keeping a Buy rating. World Trade Securities CEO Nicholas Mugalli put the same price into a two-year horizon, assuming fiscal 2028 earnings of $200 per share and a 15 times earnings multiple. Micron reports over 75 percent of its fiscal 2027 output is already committed. Twenty-six strategic agreements cover more than 35 percent of estimated revenue through 2030. Those contracts include negotiated price floors and ceilings. On October 8 the board authorized a $35.16 billion share buyback, with purchases potentially beginning December 9 under CHIPS Act funding conditions. UBS's Timothy Arcuri estimates buybacks could reach roughly $20 billion per quarter. The counterweight is equally concrete. Micron's stock has traded between $1,000 and $1,100 since mid-September. Samsung posted record profits and still lost ground on October 8. Industry capacity is expected to expand in 2028 as manufacturers scale production. Higher supply will test whether current memory pricing holds and whether the $200 per share earnings forecast survives the cycle shift. OpenAI revenue questions triggered a technology futures selloff that bled into Friday's session. The market is not ignoring demand. It is pricing in the eventual return of supply. What happens next depends on cash flow discipline and cycle timing. Buybacks reduce outstanding shares and mechanically lift earnings per share, but they do not create demand. Micron has not committed to spending the full authorization. The December 9 trigger is conditional. If memory prices soften as capacity comes online, those buyback dollars buy cheaper shares but also signal that management expects a trough. If prices hold, the repurchase program reinforces the floor beneath the stock. The strategic agreements with price collars provide a band of certainty through 2030, but they cannot shield Micron from the broader semiconductor cycle when 2028 volume hits the market. The endgame is simpler than the noise suggests. Micron has locked in revenue visibility and firepower to defend its share price. The question is whether AI memory demand sustains long enough for those commitments to translate into the earnings trajectory analysts are modeling. The supply expansion in 2028 is the variable everyone is quietly discounting. When it arrives, the $3,000 targets will face the same wall the stock has been hitting for months. Author bio: Reginald Vance is a venture partner specializing in semiconductor valuation and advanced materials, with prior roles covering capital allocation strategy at major foundry and memory firms.
More

Miners, Megawatts, and a Mystery Lab: What the Anthropic–IREN Deal Really Tells Us About the Compute Crunch

(SeaPRwire) - By: Ethan Gallagher I have sat in enough datacenter design reviews to know when a market signal matters more than the press coverage around it. The reported multi-year cloud deal between IREN and Anthropic, surfaced by The Information and still unconfirmed by both parties, is one of those signals. IREN stock popped 5% in Monday premarket trading, after an overnight move of roughly 8% on Sunday, according to Stocktwits. That reaction tells me the market is not pricing a single contract. It is pricing a structural shift in who gets to sell compute to frontier AI labs. When I walk client sites these days, the first question is never about GPU models. It is about power delivery timelines. That is the entire story here, compressed into one ticker. Here are the released facts. IREN told investors back in August, on its fiscal fourth-quarter earnings call, that it had signed multi-year cloud contracts with Cohere, Prometheus, Perplexity, Figure AI, Fal AI, and Higgsfield AI. CEO Daniel Roberts also mentioned a deal with "a leading frontier AI lab whose name we're not able to disclose just yet." The new report points to Anthropic as that unnamed customer. The report gave no dollar value and no start date. Anthropic already leans on Amazon and Google for infrastructure. Yet it is reportedly adding miners-turned-cloud-operators, specifically IREN, Hut 8, TeraWulf, and Nscale, to lock in large GPU clusters with more flexibility and at lower cost. The piece also tied the arrangement to Anthropic's planned IPO, noting that cheaper compute could help both its losses and its gross margin in front of public market buyers. Now the industry subtext, and this is where it gets uncomfortable. The first half of the story is that hyperscalers cannot build fast enough, so AI labs are renting from firms that already own power contracts and energized land. That is not a compliment to the miners. It is an admission that the grid, not the chip, is the binding constraint. The second half is rougher. Just last week, SemiAnalysis said on X that multiple customers and end users described IREN's legacy British Columbia sites, Prince George and Mackenzie, as among the worst in the industry, with one called the "#1 worst site in the industry." IREN has not been reported to have responded. The criticism targets the older facilities, not the newer AI buildout, but it underlines the gap between a headline deal and physical execution. A contract on paper does not cool a rack. IREN was also down 1.46% in its most recent regular session before Monday's bounce, so this rally sits on top of real doubt. My blunt read, from the infrastructure side, is this. Compute supply has bifurcated into two tiers: hyperscalers selling premium availability, and former bitcoin miners selling raw megawatts at a discount. Frontier labs will arbitrage between the two as long as GPU demand outruns new construction. Anthropic is not choosing IREN for elegance. It is choosing whoever can energize capacity fastest, because every quarter of delay costs it model progress and IPO optics. The miners that own power will consolidate this new customer class; the ones with creaky legacy sites will get exposed by exactly the kind of scrutiny SemiAnalysis applied. In this supply chain, the electricity bill is the moat, and everything else is marketing. Author bio: Ethan Gallagher is a Silicon Valley hardware architect and infrastructure strategist with two decades designing datacenter power and cooling systems, advising cloud operators and investors on compute capacity economics.
More

The $35 Target Nobody Saw Coming: Fastly’s AI Gamble Isn’t Hype, It’s Infrastructure Math

(SeaPRwire) - By: Lucas Caldwell Fastly isn't having a good month if you go by price action. It traded near $27.88 in early October, still 16.8 percent below its April high of $33.50. The stock has bounced 6 percent in pre-market trading after Oppenheimer upgraded it to Outperform from Perform. A $35 price target landed on the desk of senior analyst Param Singh. The move is not an emotional swing. It is structural. Singh is betting the market is still pricing Fastly like a legacy CDN provider. That pricing model is broken. Oppenheimer projects third-quarter revenue at the very top of Fastly's own guidance range. That means $184 million to $190 million. They expect management to lift its full-year 2026 revenue growth outlook to between 20 and 21 percent. The new number is not made up. It includes roughly $10 million in revenue tied to Grand Theft Auto VI traffic. It also counts early monetization from Fastly's AI Runtime, AI Firewall, and API Enforcement suites, all of which moved to general availability in September. Singh says his firm's own checks show average deal sizes grew during the quarter. Customers are buying more of the newly launched security tools. That is a measurable signal coming from the sales floor. The thesis rests on agentic AI traffic. As AI agents scale, network volumes will climb. Bot management demand follows naturally from that volume growth. Oppenheimer calls it an unpriced revenue ramp. The valuation math is stark. At the $35 target, the stock trades at seven times estimated 2027 enterprise value to sales. The peer median sits at 10.6 times. Fastly has posted three straight quarters of steady revenue growth. BofA raised its target to $22 from $20 for that reason alone. DA Davidson keeps a Neutral rating and cut its target to $23 from $26 on valuation concerns. RBC Capital held a Sector Perform with a $25 target. Eleven analysts have already revised earnings estimates upward. Fastly is expected to reach profitability this year despite not being profitable over the trailing twelve months. This name has been brutal to trade. It recorded 75 moves greater than 5 percent over the past year. Fourteen percent single-day swings are baseline volatility here. The last big move came 15 days ago when the stock fell 4.2 percent as rising yields pressured tech names and investors took profits after the investor day. The day before that, it surged roughly 14.3 percent after management laid out long-term financial targets through 2029, including a revenue growth range of 14 percent to 21 percent. Social media chatter has linked Fastly to traffic from Meta's Muse AI assistant. DA Davidson acknowledges AI agents could add some traffic but does not expect large revenue gains in the near term. A $1,000 investment made five years ago would now be worth $673.67. The stock is up 173 percent this year. Oppenheimer expects high-teens to low-20s growth over the coming years. The market underrates that path and will re-rate the stock if management delivers on growth and margin expansion. That is the bet. The question is whether you trust the edge infrastructure thesis or keep waiting for a cheaper entry. Author bio: Lucas Caldwell is a tech opinion leader with millions of followers on X/Twitter, known for blunt infrastructure plays and zero tolerance for vendor spin.
More
Oracle’s AI Gamble: Why a Director Bought While the CEO Sold Business

Oracle’s AI Gamble: Why a Director Bought While the CEO Sold

(SeaPRwire) - By: Reginald Vance Oracle’s stock sits at $141.56, well below its 50-day moving average of $146.35 and 200-day average of $159.03. The market is nervous. The core issue is not just the price action. It is the massive capital expenditure required to support OpenAI. Reports float around that OpenAI’s annual recurring revenue is between $50 billion and $70 billion. That number swings the stock. Oracle is the infrastructure backbone for that growth. But the cost to build that backbone is eating into cash flow. The company is seeking large private financing to buy AI chips. This is not a software margin story anymore. It is a heavy industrial asset story. The official release paints a picture of steady performance. Oracle beat earnings estimates on Sept. 10. EPS came in at $1.92 against a $1.74 estimate. Revenue rose 29.6% to $19.34 billion. The company guided second-quarter fiscal 2027 EPS to $1.85 to $1.93. Analysts rate the stock Moderate Buy with a $251.72 consensus target. Mizuho added Oracle to its top picks with a $320 price target. The public narrative focuses on cloud infrastructure demand. The subtext is risk. Insiders sold about $5.34 million in the last 90 days. CEO Michael Sicilia sold 22,562 shares at $151.59 on Sept. 22. This was a pre-arranged 10b5-1 plan. Even so, selling into strength signals caution. Mar Vista exited its position. They said the rally reduced their margin of safety. Smart money is taking profits. Contrast this with the buying side. Director Stephen Rusckowski bought 25,000 shares on Sept. 29. He paid between $138.96 and $139.74. That is roughly $3.5 million. This was his first open-market purchase since joining the board nearly a year ago. He is a former CEO of Quest Diagnostics. His trust held 25,390 shares before this buy. Now he owns more. Why buy when the CEO is selling? Rusckowski likely sees value in the data center buildout. Oracle is trucking natural gas to keep construction moving. They have a 2.45 gigawatt project in New Mexico. The hardware is going in. The revenue stream from OpenAI is locked in for years. The risk is the debt load to finance the chips. The technical chart shows a stock that has steadied after its slide from the June peak. Since the $114.50 low in late July, price has made higher lows. The latest close of $141.40 bounced off a support zone near $135 to $140. RSI reads 48.18. That is neutral. MACD is flat. No bullish crossover yet. Resistance sits at $150 to $155. A close below $135 opens the door to $114.50. Holding above it keeps the structure intact. Moving through $155 signals buyers are in control. Oracle is no longer just a database company. It is a utility for AI. The hardware supply chain is the bottleneck. If you cannot secure power and chips, the revenue promise evaporates. The director’s buy is a vote of confidence in the physical assets. The CEO’s sell is a standard risk management move. The market will pay for the gigawatts, not the code. Author bio: Reginald Vance, a venture partner specializing in semiconductor valuation and advanced materials.
More
The Banks Are in Damage Control. SpaceX Just Stole Their Cover Story. Business

The Banks Are in Damage Control. SpaceX Just Stole Their Cover Story.

(SeaPRwire) - By: Robert Kensington The S&P 500 closed Friday at 7,811.54. Up 0.59% on the day. Up 1.2% on the week. The Nasdaq added 0.9%. The Dow gained 0.6%. On the surface, this looks like a strong close. But the picture fractures when you dig one inch below the hood. The five major banks have lost roughly $270 billion in market value. The financial sector dropped about 4% over the past month, making it the second-worst performer among all S&P 500 sectors. Truist Securities found that only 35% of institutional investors expect bank stocks to beat the market. That number was 68% in July. In just two months, conviction has been cut in half. That is not a mood swing or a passing anxiety. That is a structural break in how the market prices banking risk. The street has stopped believing the recovery narrative for big banks, and the upcoming earnings reports will either confirm that skepticism or force a second-guess. On Tuesday, JPMorgan Chase, Goldman Sachs, Wells Fargo, and Citigroup open Q3 earnings season. UnitedHealth and Johnson & Johnson report the same day. Bank of America and Morgan Stanley follow Wednesday. BlackRock and ASML are also on the docket. Analysts expect bank profits to fall from the prior quarter. Trading and investment banking revenue are expected to decline as well. Goldman Sachs CEO David Solomon said in late September that trading in fixed income, currencies, and commodities had been "a little bit softer" than a year earlier. Morgan Stanley co-president Daniel Simkowitz put it bluntly: "I think it's safe to say 3Q is no 2Q." The official narrative is one of caution and cooling. The language is deliberately measured. "A little bit softer." "Safe to say." These are not descriptions of a market in free fall. They are descriptions of a market being managed downward by executives who want to preserve the option of further tightening without looking like they are panicking. The subtext is starker. Banks were the trade engine last quarter. That engine has sputtered. The higher rates that supposedly benefit banking margins through net interest income have started throttling loan demand. The theory says banks earn more on loans compared to what they pay on deposits. In practice, fewer borrowers means narrower revenue. Bank executives described the economy as healthy this summer. Trading volume was up. Merger activity was brisk. But none of that translates to quarter-over-quarter earnings growth. The official announcement reads like a managed retreat. The true commercial intention is damage control. The banks are not in crisis. They are in a period of margin compression that will either be resolved by rate cuts or become permanent structural erosion. This is the central tension of the earnings season. Every bank will try to tell a story of resilience. The street will read every one of them as a story of decline. Taiwan Semiconductor reports Thursday. ASML reports Wednesday. TSMC beat profit estimates last quarter but its shares fell after the report. That pattern tells you everything about market psychology at this stage of the cycle. Wall Street has priced in perfection. Any miss becomes a sell trigger regardless of absolute numbers. The September CPI lands Wednesday. Economists expect prices to rise 3.6% from a year earlier, up from 3.4% in August. Prices for gasoline, food, and computer parts have climbed since the war in Iran began in late February. Fed Chair Kevin Warsh said in September: "The plain fact is that inflation is too high and has been for too long." The Fed raised rates by a quarter point in September. That was the first hike in three years. The target range is now 3.75% to 4%. Most Fed officials projected at least one more quarter-point hike this year. Traders now price in roughly 80% odds of an October increase. Bank of America economist Stephen Juneau said the CPI report may not be strong enough to shift expectations toward an October hike. New York Fed president John Williams has also signaled room to wait. Retail sales and the Producer Price Index arrive Thursday. Industrial production data follows Friday. The CPI number will not change the Fed's mandate. But it will change the market's confidence that the Fed has any room to pivot lower. Telecom stocks dropped Friday after SpaceX said it agreed to buy a nationwide low-band spectrum portfolio from Grain Management. Verizon fell 5%. AT&T dropped nearly 7%. T-Mobile declined more than 6%. SpaceX COO Gwynne Shotwell said in August that Starlink plans to build a wireless network. SpaceX shares closed Friday at $162.57, up 1.25%. This is the canary in the coal mine that nobody wanted to see. The old guard is bleeding market share to entrants that do not play by the same rules. Banks are bleeding to rate pressure and softer trading volumes. Telecoms are bleeding to SpaceX's satellite-to-wireless ambition. The market is not growing evenly. It is consolidating around whoever can move fastest and borrow cheapest. Whoever cannot do both will become acquisition targets or industry footnotes. The earnings season this week will not deliver surprises. It will deliver confirmations. Bank margins will compress. Trading desks will underperform. Chip results will be judged against thresholds set before the earnings even land. The landscape is already set. The question is only how quickly the market will absorb what everyone already knows. Author bio: Robert Kensington, an overseas entrepreneurial veteran with decades of experience in real-economy industrial investment and expansion.
More
The $7B Decart Bet: Why Amazon Is Buying Its Way Out of the Nvidia Trap Business

The $7B Decart Bet: Why Amazon Is Buying Its Way Out of the Nvidia Trap

(SeaPRwire) - By: Ethan Gallagher People are treating this as another standard SaaS acquisition. That view misses the point entirely. Amazon isn’t buying developer tools. It is buying a wedge into the silicon independence war. The gap between Decart’s May valuation of nearly $4 billion and the reported $7 billion talks is stark. Five months. No major product launch. No new revenue stream disclosed. The jump signals scarcity. Competitors want this software. Nvidia knows its lock on the GPU market is eroding. Amazon is paying a premium to secure a lifeline for its Trainium3 chips. The narrative is simple. If developers can easily switch chips, the moat cracks. Let’s look at the facts versus the subtext. The Wall Street Journal reports talks for a $7 billion deal. Decart’s software allows developers to move AI workloads between different chips easily. On the surface, this is a convenience feature. In reality, it is a direct attack on Nvidia’s install base. Amazon gave Decart early access to Trainium3 in 2025. They liked what they saw. Now they want full control. The subtext is clear. Amazon wants to reduce friction for customers moving to its own hardware. Every hour a developer spends porting code is an hour lost to Nvidia’s ecosystem. Decart removes that friction. It makes the switch trivial. That is worth $7 billion to AWS. Consider the technical fit. Decart builds world models called Lucy and Oasis. These generate 3D environments for robotics and autonomous driving. This aligns with Amazon’s broader AI strategy. It is not just about chips. It is about the simulation layer. If you are building the next generation of warehouse robots or delivery drones, you need simulated environments to train them. Decart provides that. The startup was founded in 2023 by Dean and Orian Leitersdorf and Moshe Shalev. They have raised over $400 million from Sequoia Capital, Benchmark, and Radical Ventures. Now Amazon is offering them an exit. Or rather, a merger of operations. The founders get liquidity. Amazon gets the tech stack. The investors get their returns early. The market reaction tells the story. AMZN stock rose 3.29% on the news. Wall Street consensus remains Strong Buy with an average target of $332.35. Analyst Laura Martin keeps her Buy rating, arguing AI shopping agent fears are overstated. The technical indicators support the momentum. RSI is at 59. MACD just crossed positive. The stock is holding the $259 support zone. Resistance sits at $286. If the deal closes, the stock likely tests the upper channel. The supply chain landscape shifts. Chip vendors can no longer rely on software lock-in. The hardware becomes commodity-like. The value migrates to the layer that abstracts it. Amazon is betting that layer is where the long-term margin lives. Amazon is not paying for code. It is paying for the right to make hardware optional. If that fails, the $7 billion price tag becomes a cautionary tale for the rest of the valley. Author bio: Ethan Gallagher, Silicon Valley hardware architect and infrastructure strategist. Specializes in semiconductor supply chain dynamics and cloud computing market structures.
More
Micron at $1,029: Wall Street Screams Buy While the CEO Quietly Walks Out the Side Door Business

Micron at $1,029: Wall Street Screams Buy While the CEO Quietly Walks Out the Side Door

(SeaPRwire) - By: Lucas Caldwell Everyone posting "buy the dip" on Micron right now is ignoring the single loudest signal in the tape: the people running the company are selling it. MU trades near $1,029, down 18% from its June 25 record close of $1,255. CEO Sanjay Mehrotra unloaded $38.8 million of stock on August 21 at an average of $968.90, cutting his stake by 13%. Total insider sales hit $90.9 million over three months. Insiders now own 0.24% of the company. Meanwhile retail traders on my timeline are calling this the entry of the decade. Somebody is wrong here, and my money says it is not the CEO. The bull numbers are real, and they are wild. Fiscal fourth-quarter revenue exploded 379% to $54.23 billion, smashing the $51.33 billion forecast. EPS printed $33.42 against a $31.77 consensus. Net margin sat at 63.8%. Guidance for fiscal Q1 2027 calls for EPS between $37.15 and $39.15. More than 75% of fiscal 2027 shipments are reportedly committed. HBM needs three times the wafer capacity of standard DRAM, which has squeezed DRAM supply across PCs, phones, and servers and pushed prices upward. Analysts model 55% revenue and 67% EPS growth from fiscal 2026 to 2028. The valuation pitch sounds absurd on paper. Roughly six times expected earnings for this year. Wall Street carries one Strong Buy, 41 Buys, four Holds. Consensus target: $1,407.88. Rosenblatt went to $1,900. Zacks upgraded to Strong Buy. Market cap hovers near $1.2 trillion, with the stock miles above its 50-day at $980.05 and 200-day at $841.86. On a spreadsheet, this is the cheapest AI story alive. Spreadsheets, of course, are exactly where memory stocks go to lie to you. Now the part the bulls skip. Memory is a serial killer of portfolios. Micron dropped 73% from 2014 to 2016, 55% in 2018, 43% in 2020, 51% in 2021, 36% in 2024. Shortages become gluts. They always do. Every cycle ends with makers overbuilding capacity into a demand wall. The options market already smells it. Put volume in the SMH ETF far exceeded call volume, signaling heavy hedging across chips. Add softer-than-expected OpenAI revenue data, slower profit growth at Samsung, and a Taiwan union authorizing strike action over bonuses. The anxiety is stacking. The chart confirms the hesitation. MU has churned sideways since the June peak, bounced off $740 in late July, rode a rising trendline to about $1,100 in September, then rolled over. Price closed below the $1,035 level, flipping it to resistance. The trendline sits near $1,016. Next real support is $900. RSI reads 50.20, cooled from the 60s in early October. MACD prints 22.36 versus a 28.68 signal line, histogram at negative 6.32. Bearish crossover, fading momentum, volume running light at 19.9 million versus a 32.5 million average. If $1,016 cracks, $900 comes fast, and the "cheapest AI stock" narrative gets stress-tested against the oldest lesson in semis: insiders sell tops, not bottoms. Author bio: Lucas Caldwell, a tech opinion leader with millions of followers on X/Twitter, known for contrarian semiconductor calls and stripped-down tape analysis.
More
The 11-Cent Peace: Trump’s Energy Ceasefire Is a Diesel Deal in Disguise Business

The 11-Cent Peace: Trump’s Energy Ceasefire Is a Diesel Deal in Disguise

(SeaPRwire) - By: Julian Holbrooke A ceasefire that no party confirms is a press release with oil futures attached. Trump announced Russia and Ukraine agreed to stop attacking energy facilities. Brent fell 11 cents to $104.61 a barrel by 0627 GMT. WTI fell 49 cents to $91.36. Earlier both benchmarks were down more than 1%. Some of that was profit-taking after crude gained nearly 3% last week. But the scale of the drop matters. A real de-escalation would have triggered a far bigger selloff. A peace breakthrough would not produce eleven cents of movement. The market is treating this as a supply announcement, not a strategic turning point. That distinction is the entire story. The official version is simple. Trump says Russia will immediately supply more than 300,000 metric tons of diesel to the US and global markets. Another 500,000 tons arrives in November. One million tons follows after that. ICE gasoil futures dropped 3% to $1,436 per metric ton. The IEA sees global daily diesel demand near 29 million barrels. Executive Director Fatih Birol asked member countries to assess whether more diesel releases are needed. Tim Waterer at KCM Trade says the announcements eased some immediate supply pressure. The geopolitics are murkier. Zelenskiy says he is still waiting for details. Russia has not commented at all. This is not a small omission. Trump announced the same energy ceasefire in mid-September. Neither side confirmed that one either. A pattern emerges. Washington announces, Moscow stays silent, Kyiv waits, and the market moves a little. The actual negotiating track remains invisible. What is visible is a US administration that wants diesel flowing into global markets before winter demand peaks. The ceasefire and the diesel supply announcement landed in the same news cycle. That is not a coincidence. The second half of the story is where the real risk lives. The Houthis claimed a Saturday strike on Riyadh's international airport that killed 13 people and wounded more than 300. Saudi authorities reported injuries from a new attack on Sunday. Trump said the US is considering joining Saudi strikes on the Houthis. Tanker attacks near the Strait of Hormuz are accelerating. The UK Maritime Trade Operations recorded a drone strike on a tanker near Sohar anchorage in Oman. Another tanker was hit by an unknown projectile. Iran says a US proposal to reopen the Strait of Hormuz is insufficient. Iran has stepped up attacks on shipping since late September. That strait is the world's most important energy chokepoint. Any sustained disruption there outweighs a few hundred thousand tons of diesel. Then add Hurricane Isaias. It hit the US Gulf Coast early Saturday. Shell, Chevron and BP are working to restore production. More than 60% of Gulf of Mexico output was still offline last week. Goldman Sachs raised its December Brent forecast to $90 a barrel from $85. The bank estimates a risk premium of just over $20 per barrel. It expects WTI to average $81 in December 2026. That forecast is a bet that the war premium shrinks but does not disappear. What does this add up to? A market that refuses to believe the peace story. Russian diesel volumes are real barrels, but they arrive against a backdrop of airport bombings, tanker drones and hurricane-idled platforms. The energy ceasefire is unverified, unconfirmed and already repeating a failed September script. Every silent hour from Kyiv and Moscow erodes its credibility further. The geopolitical pendulum is not swinging toward peace. It is swinging between Washington's need to cool prices and the Middle East's capacity to ignite them. Brent sitting above $100 is the verdict. The diesel deal treats a symptom. The conflict keeps manufacturing new supply shocks. Oil traders are not naive. They know a trade when they see one. This is a trade, not a truce, and the price action proves it. Author bio: Julian Holbrooke, an international relations analyst who contributes to major European daily newspapers, specializes in energy geopolitics, sanctions and great-power bargaining.
More

UnitedHealth’s $27 Coin Flip: Why Tuesday’s Print Is Really a Verdict on the Whole Medicare Advantage Model

(SeaPRwire) - By: Christian Pierce Here is the uncomfortable truth sitting under UnitedHealth's Tuesday morning report: nobody on Wall Street actually knows what this company is worth right now, and the options market is being unusually honest about it. Traders are pricing a 7% move in either direction, roughly $27 on a stock sitting near $379. That is not conviction. That is a coin flip dressed up in Greek letters. The anxiety is rational. UNH is up about 17% this year, yet it was flat over the past month while healthcare providers and services peers climbed roughly 2%. The market is holding its breath because UnitedHealth is the first insurer to report this season. There is no read-through from rivals. Whatever management says about medical costs before Tuesday's open will set the tone for the entire managed care complex, and everyone knows it. The facts themselves are a study in contradiction. Wall Street expects Q3 earnings of $4.15 per share, a big jump from $2.92 a year ago. Revenue is forecast at $111.31 billion, which is below the $113.20 billion posted last quarter and implies a 2% decline year over year. Profit up, top line down. That is a margin story, and margin stories in managed care live and die on medical cost ratios. The company's own history makes the stakes plain. Its last four post-earnings moves ranged from a 20% collapse to a 7% gain, with an average absolute move of about 7%, exactly what options imply. It beat on both revenue and EPS last quarter, but it has missed revenue estimates several times over the past two years. Analysts have mostly held estimates steady over the past 30 days, which means nobody wanted to plant a flag ahead of the print. The sell-side split is telling. Piper Sandler's Jessica Tassan kept her Buy but trimmed her target to $463 from $475, arguing Medicare Advantage star ratings show resilience and writing flatly, "We would be buyers of the stock into 3Q26." TD Cowen's Ryan Langston went the other way, cutting his target to $402 from $430 and keeping a Hold. He calls consensus estimates for medical costs and earnings "more than achievable," yet flags a real problem in Optum Health, where consensus operating earnings of $299 million sit well above management's own guidance of roughly $150 million. He also warns that lower Medicare Advantage star ratings could create a $1.5 billion revenue headwind in 2028. The broader tape still leans bullish: a Strong Buy consensus on TipRanks, 17 Buys against four Holds, and an average target of $485 implying about 28% upside. A September 28 earnings preview memo circulating among traders adds one more layer, pointing to a 2026 plan of adjusted earnings between $19.50 and $20 per share, raised from an older plan, plus at least $5 billion in buybacks. Now follow the commercial loop, because that is where this report actually matters. UnitedHealth's engine runs on two cylinders: the insurance book, where Medicare Advantage reimbursement and star ratings dictate revenue quality, and Optum, where care delivery margins are supposed to smooth the cycle. Langston's note exposes the tension. The Street is modeling Optum Health earnings at nearly double what management has guided. Either consensus is wrong, or management is sandbagging. Neither outcome is neutral for the stock. Layer on the 2028 star-ratings headwind and you see the real endgame. This is not a debate about one quarter's $4.15 print. It is a repricing of how durable the Medicare Advantage economics are under tighter reimbursement, and whether the Optum flywheel can carry the group while the insurance side absorbs policy pressure. The raised 2026 outlook and the $5 billion buyback commitment are management's counter-argument, a signal that cash generation remains intact. If UnitedHealth delivers on cost discipline Tuesday and holds guidance, it validates the Strong Buy consensus and pulls the whole peer group up with it. If medical costs surprise higher or Optum misses that elevated consensus bar, the stock's recent habit of double-digit post-earnings drops reasserts itself fast. For positioning, the practical read is simple: treat the 7% implied move as fair odds, not an edge, and let the print confirm which side of the 2026 plan is real before adding exposure. Author bio: Christian Pierce is a chief financial columnist and markets commentator covering managed care, healthcare services, and insurance economics, with two decades analyzing earnings cycles and capital allocation across the U.S. health sector.
More
Wall Street’s Earnings High-Wire Act: Why 29.6% Growth Won’t Save You From 5.24% Yields Business

Wall Street’s Earnings High-Wire Act: Why 29.6% Growth Won’t Save You From 5.24% Yields

(SeaPRwire) - By: Logan Pierce The S&P 500 is riding high on AI mania and a winning week, but Wall Street is about to walk a very narrow earnings tightrope. JPMorgan Chase, Goldman Sachs, Wells Fargo and Citigroup are reporting Tuesday. Their results will either validate the current rally or expose how much faith investors have already placed in data center buildouts and speculative momentum. Earnings for the S&P 500 are on track for 29.6% growth this quarter. That is the fourth consecutive quarter above 25 percent. FactSet's John Butters puts it plainly — AI data center demand is the engine behind these numbers. Meanwhile, the 10-year Treasury yield sat near 5.24 percent last week, close to a 24-year high. The Nasdaq has gained for four straight weeks. Capital is chasing growth in a rate environment that should logically punish it. South Korea's Kospi fell 3.65 percent and the Kosdaq dropped 4.83 percent on the same day Wall Street smiled. Brent crude traded above $104 a barrel before sliding on news of a Russia-Ukraine energy ceasefire. President Donald Trump announced the deal and also said he was considering joining Saudi Arabia's fight against Houthis after an attack on Riyadh's airport. Kyiv and Moscow had not confirmed the ceasefire. Washington was reportedly pressuring Kyiv to accept or risk losing U.S. military support. Global capital is pricing in stability that may not yet exist. Taiwan Semiconductor Manufacturing reports Thursday. Investors will scan their numbers for signs of sustained AI chip and data center equipment demand. Johnson & Johnson and UnitedHealth Group report Tuesday alongside the banks. Bank of America, Morgan Stanley, BlackRock and ASML follow Wednesday. Brian Leonard of the Keeley Gabelli Small Cap Dividend Fund put it simply. He said investors want to know whether a company can withstand current conditions and keep growing margins. That question cuts deeper than any quarterly beat. September consumer price data arrives Wednesday with economists forecasting headline inflation at 3.6 percent year over year and core at 2.5 percent. Producer prices come Thursday. Retail sales data is also scheduled this week. The Federal Reserve is navigating a landscape where bond yields hover near 24-year peaks and equity valuations rest on assumptions about perpetual AI-driven expansion. A miss on inflation or a soft earnings read from the majors could reverse the current trajectory faster than anyone expects. JPMorgan, Goldman Sachs, Wells Fargo and Citigroup set the tone this week. If their margin profiles hold against rising borrowing costs and slowing loan demand, the rally continues. If not, the 29.6 percent earnings growth figure becomes a footnote in a much uglier second half. Author bio: Logan Pierce is an independent business researcher and corporate governance writer on Medium, focusing on earnings cycles and macro-financial crosscurrents.
More

The White House Holds 200,000 Bitcoin It Can’t Sell, and That’s the Whole Story

(SeaPRwire) -By: Jonathan Barrett Washington spent eighteen months turning crypto policy into a loyalty test, and the market still fell a third from its peak. That is the uncomfortable fact nobody at the Bitcoin conferences wants to say out loud. Since January 2025, Trump signed a Strategic Bitcoin Reserve order, pushed the GENIUS Act stablecoin law, and ordered a 401(k) rule review. Each move was real, documented, and fast. Yet Bitcoin trades at $83,376.06 as of September 24, 2026, well below the $126,080 record set on October 6, 2025. Friendly government, hostile price action. Something is off in that equation. The reserve came first, on March 6, 2025. Treasury was told to hold forfeited Bitcoin in custodial accounts and never sell it. David Sacks claimed the government owns about 200,000 Bitcoin, but no full audit exists. Then the GENIUS Act landed July 18, 2025, mandating 1:1 reserves, audits, and licensing for payment stablecoin issuers. Full effect waits until January 18, 2027. The 401(k) order followed August 7, 2025. Labor scrapped its Biden-era crypto warning in May, proposed a formal rule in March 2026, and nothing has taken effect. The CLARITY Act passed the House in July 2025 and sits stalled in the Senate. Now examine the private side of the ledger. Trump's June 30 financial disclosure showed more than $1.4 billion from family crypto ventures in 2025, his largest income source that year. Royalties from the $TRUMP memecoin, launched three days before inauguration. Token sales at World Liberty Financial, which he co-founded with his sons in September 2024. The firm issues USD1, its own stablecoin. In August 2026, the OCC gave World Liberty Trust Company preliminary approval for a national trust bank charter. It cannot take deposits yet. But the president's family now stands to profit from the same stablecoin framework his administration wrote. The industry game is equally transparent. The stablecoin market cap hit $314.68 billion by June 2026. Bank of America's CEO publicly committed to entering the business once legal. A cluster of banks is building a joint stablecoin while JPMorgan doubles down on its own Kinexys network. The Treasury's August 2026 proposed rule frames stablecoins as payment infrastructure, not investment products. Meanwhile, Trump Media added Bitcoin to its balance sheet in July 2025, riding the corporate treasury wave that fed ETF demand. Everyone with proximity to the rulemaking found a revenue line. The compliance lane became a toll road. Then the market delivered its verdict. Inauguration Day set an intraday record. October 6 brought the $126,080 peak. Four days later, on October 10, 2025, a record liquidation wave hit, and Bitcoin slid into 2026. By January, institutions were pulling funds out of Bitcoin ETFs. Analysts blame two specific disappointments. The reserve order triggered no actual government buying, only custody of seized coins. And Congress never passed the market structure bill. Policy theater without capital behind it reads, to professional money, as noise. The deregulation rally ran on expectations. Expectations expired. Watch the Senate on CLARITY and the OCC's final charter decision for World Liberty, because the next twelve months will reveal whether crypto won regulatory capture or merely rented it. Author bio: Jonathan Barrett, lead focus editor for an independent overseas public affairs weekly, covering the intersection of financial regulation, executive power, and market structure for over a decade.
More