BofA Drew Five Targets Ahead of Q3 — Here’s What the Aim Line Actually Hides

(SeaPRwire) - By: Robert Kensington Earnings season is not a reporting period. It is a sniper shoot. Every sell-side call placed before the window is a positioning document disguised as homework. Bank of America dropped five buy-rated names ahead of Q3 results. They span sports betting, nuclear energy, healthcare, discount retail, and Southeast Asian online services. The sell-side framing makes each look like a bargain. The word "bargain" itself is the first thing to interrogate. What you are really reading is a risk-appetite inventory. It is a map of where institutional capital is willing to sit this quarter. Sticky rates and stretched multiples make the environment unforgiving. Every one of these five stocks carries a live risk factor that the pitch deck minimizes or leaves to a footnote. Now let me lay out what BofA says on the record. DraftKings was upgraded from Neutral to Buy by analyst Julie Hoover with a $27 price target. Shares are down roughly 47% over the past year. BofA calls that an improved risk-reward balance. The bank projects prediction markets could generate about $400 million in fees by 2027. Market-making could stack additional revenue on top of that number. BWX Technologies keeps a Buy rating from analyst Ronald Epstein after the September investor day. But the price target was cut from $250 to $210. A $189 million contract to supply nuclear reactor fuel to the US Navy anchors the pitch. AI-driven power demand adds a second tailwind to the thesis. AstraZeneca's July 2026 update listed 183 development projects spanning cancer, heart disease, and other conditions. Trial results and possible regulatory approvals are cited as catalysts. Grocery Outlet was upgraded from Neutral to Buy by analyst Robert Ohmes. His price target was raised to $15. The case rests on improved operations and a better product mix. It also cites consistent pricing across delivery platforms like DoorDash, Uber Eats, and Instacart. Investors want to see whether customer spending and same-store sales follow. Grab posted record Q2 results in August and raised its full-year outlook. It also announced a $750 million share buyback. Ride-hailing, food delivery, and financial services span the Southeast Asian market. Currency swings, fuel costs, and competition remain the named risks. Strip the presentation layer and ask what the numbers are actually trying to say. DraftKings' prediction-market thesis rests on a 2027 fee estimate. That estimate is built on top of regulatory uncertainty, competition, and heavy spending commitments. The $400 million figure is not a booked contract. It is a hope wrapped in a forecast. BWX Technologies had its price target cut by forty dollars right before its November 2 earnings date. That is not free conviction. It is an analyst hedging against a number that has already moved against him. AstraZeneca's 183-project pipeline is a spread bet on clinical outcomes. Weak trial results or regulatory friction can erase the upside fast. Competition for approvals is real and brutal. Grocery Outlet's delivery-pricing consistency is a margin defense play, not a growth engine. Same-store sales and profit margins still need to prove the thesis before the price target becomes self-evident. Grab's buyback is treasury management doing marketing work. Currency swings and fuel costs in Southeast Asia can erase a quarter's gains before the next reporting date. Five sectors. Five distinct catalysts. One common thread runs through them all. Each pick is a short-duration thesis that lives or dies inside the next sixty days of reporting. The real reshuffling will not come from the stocks that beat by a margin point. It will come from the ones that guide conservatively, absorb the discount, and force a re-rating. BWX Technologies reports on November 2. If they defend guidance while the target sits at $210, you have a directional signal. If they guide down, the entire list needs a haircut. Position for the outcome, not the narrative. Author bio: Robert Kensington, an overseas entrepreneurial veteran who has spent over two decades advising on industrial capital allocation and cross-border manufacturing investment across Asia, Europe, and the Americas.
More

The Physical Ghost in the Cryptocurrency Machine: Why the Ledger ‘Implant’ Breaks the Trust Model

(SeaPRwire) -By: Ethan Gallagher We built the entire self-custody narrative on a single, fragile promise. You control the keys, you own the assets. The Ledger is the physical embodiment of that trust. It is the black box that sits on your desk. It is the boundary between your digital wealth and the prying eyes of hackers and governments. When that boundary is breached not by a smart contract exploit, but by a physical wire soldered into a circuit board, the panic is visceral. It reminds us that in a world of code, the atom still governs the bit. This is no longer a software bug. It is a hardware betrayal. Ledger confirmed on October 10 that a specific device held an unauthorized hardware implant. This is the official fact. The company stated it has no indication that its broader security infrastructure or services were compromised. They are focusing on one affected customer’s device. The loss estimates from third-party investigators range from $72 million to $93.4 million. Ledger has not verified these figures. They remain in a gray zone. The company is working with authorities and contacting impacted users. The narrative is controlled, cautious, and strictly technical. The industry subtext is darker. Mark Karpelès, the former Mt. Gox CEO, found a modified Ledger Nano X with a hidden circuit. It included cellular equipment. This hardware could intercept recovery phrases during setup. It would send the words over a cellular link. This is not a subtle data leak. It is a stalker chip. The reseller CryptoBilis has stopped selling hardware wallets. They operate in Indonesia, Malaysia, and the Philippines. Ledger asked them to pause shipments on October 9. There is also a fake Ledger website on Google. It asks for 24-word phrases. It had over one million visits in 30 days. These are separate issues, but they tell a story of a supply chain that was wide open for the taking. The supply chain is no longer just about silicon wafers and distribution centers. It is about physical trust. If a reseller can inject a cellular modem into a sealed case, the entire "cold storage" paradigm collapses. Hardware wallets are only as strong as the weakest link in the logistics chain. That link is now the reseller. You cannot verify a chip’s internal wiring with a casual glance. The industry will likely move toward signed firmware and more aggressive physical inspection requirements. Until then, the risk remains. A hardware wallet is not just a device. It is a promise. When that promise is physically broken, the value of every seed phrase created under that threat is compromised. The era of blind trust in the black box is over. Author bio: Ethan Gallagher is a Silicon Valley Hardware Architect and Infrastructure Strategist with two decades of experience in secure computing and physical security auditing for critical infrastructure.
More

The Great Crypto ETF Exodus: Why $1.29 Billion Fled in Five Days

(SeaPRwire) -By: Ethan Gallagher The capital exit from U.S. crypto exchange-traded funds was not a trickle. It was a dam break. Between October 5 and October 9, Farside Investors recorded a collective hemorrhage of $1.29 billion. This is not a standard correction. It is a structural shift in liquidity. Bitcoin funds shed $678.9 million, snapping a three-week inflow run. Ether funds bled $542.2 million, marking nine consecutive days of negative flows. The market is not just retreating. It is purging speculative excess at an industrial scale. Official data presents a clean, mechanical ledger. Farside logs the specific daily drains. Wednesday alone saw $484.9 million leave Bitcoin funds. Thursday added another $244.1 million in exits. By Friday, the bleeding slowed to a mere $21.1 million in inflows. BlackRock’s Bitcoin fund finished the week with a negligible $1.1 million in gains, standing as a stark outlier. The industry subtext, however, reveals a different narrative. This is not just price volatility. It is a flight of trust. Investors are not merely selling assets. They are abandoning the ETF wrapper as a safe harbor. The fact that Fidelity’s Bitcoin fund lost $380.3 million indicates that even the blue-chip vehicles are vulnerable to sudden de-risking impulses. The Ether sector reveals the depth of the anxiety. Outflows extended to nine straight trading days, totaling $697.2 million since September 29. BlackRock’s Ether fund accounted for $477.1 million of the weekly loss, representing 88% of the total drain. This concentration is alarming. It suggests a coordinated institutional exit rather than scattered retail selling. Meanwhile, Solana funds ended a record 14-week inflow streak with a $25 million outflow. The irony is thick. Two weeks prior, these funds drew a record $188.2 million. Now, the tide has reversed completely. Zcash and Hyperliquid funds also saw exits, losing $30.8 million and $9.4 million respectively. The breadth of the sell-off covers the entire spectrum of crypto ETFs. The supply chain for crypto liquidity is now fragile. Institutional capital is no longer the steady underpinning it was last month. When the biggest funds like Fidelity and BlackRock face such massive withdrawals, the underlying asset prices suffer a feedback loop of forced selling. Bitcoin now sits near $82,900. Ether hovers around $2,506. These levels are not supported by robust ETF inflows. They are held up by spot demand alone. The era of passive ETF accumulation is over. The next phase will be dictated by active traders who understand that the ETF wrapper offers no protection against systemic crypto winter. Author bio: Ethan Gallagher is a Silicon Valley Hardware Architect and Infrastructure Strategist who analyzes the intersection of physical infrastructure and digital asset liquidity.
More

China’s Blockchain Decree Isn’t About Innovation—It’s About Control

(SeaPRwire) -By: Julian Vance The language in Beijing's latest tech directive is carefully sanitized. It speaks of markets, openness, and private investment. Read it sideways and the architecture of control becomes obvious. The Communist Party Central Committee and State Council issued a 19-measure opinion on October 9. It calls for a national blockchain network and an integrated computing power network. It covers AI, quantum computing, and data ownership rules. On the surface this reads like a industrial policy playbook. Beneath that surface it reads like a consolidation mandate. The policy places the blockchain network squarely inside a section about linking the real economy to the digital economy. Smart manufacturing, industrial internet projects, and the East Data, West Computing program share the same paragraph. This is not a coincidence. The intent is to route every digitized transaction in Chinese industry through state-designated ledgers. A "national blockchain network" does not mean an open protocol community building tools. It means a single architecture that the state can audit, direct, and shut down at will. Data becomes an economic resource. Authorities were told to improve rules on who owns data and how it is traded. An "open, shared and secure data market" was proposed. The word "secure" does the heavy lifting here. Security in Beijing's policy vocabulary means centralized access points. The pilot projects treating data as a commodity will ultimately create a classified dataset that only licensed entities can enter. Small firms will lease access. Large state-affiliated firms will get priority. The banks are already inside the net. In April, the State Administration of Taxation and the National Financial Regulatory Administration encouraged blockchain-based tax data sharing. The goal was to help banks assess small business borrowers. That program has now scaled up into a nationwide network mandate. Financial inclusion through surveillance is the actual model. A small business in Guangdong gets a loan faster, but its tax records, supply chain movements, and payment history flow through a ledger the state watches. The digital yuan accelerates the same logic. Eight new banking operators were approved on August 17. Ping An Bank, Hengfeng Bank, and Bank of Shanghai joined the rollout. That brings the total to 30 operators. In January, verified digital yuan wallets became eligible for interest and deposit insurance. In July, ICBC branches in Shanghai and Singapore settled nearly 10 million yuan in shipping fees through the platform. Cross-border trials are planned for Guangdong's free trade zone through 2030. Every transaction leaves a permanent record. Every record is queryable. Crypto stays restricted. Stablecoin rules were extended in February. Authorization is required for offshore renminbi-pegged stablecoins. Virtual currency businesses and mining remain limited. The contrast is stark. Permissionless finance is banned. Permissioned finance is being built at scale. The distinction is the entire point. Private investment is encouraged through fiscal policy. This is not a signal of liberalization. It is a signal of directed capital. The state identifies priority sectors, guarantees returns through subsidies and preferential lending, and lets private money fill the gaps. When the network is complete, the data belongs to the state. The private investors get their exits. A sovereign technology stack built on blockchain and digital currency gives Beijing something no other major economy currently possesses at this scale. Full transaction visibility inside a controlled perimeter. That advantage will either become a geopolitical asset or a vulnerability depending on whether the system can scale without becoming a target. The next two years of rollout will show which direction it moves.
More

The Liquidation Squeeze and the Quiet Bank Building in the Ruins

(SeaPRwire) -Bitcoin dropped more than $6,000 in five trading days. That is not a correction. That is a forced march through leverage that accumulated when prices were higher. By Thursday, October 8, the spot price had sunk to roughly $80,400 before a tentative recovery brought it back toward $82,500. The Federal Reserve is not easing. Oil prices spiked on tensions involving Iran. Two major forces pulled risk assets down at the same time. Investors do not trust that either pressure has passed. This was not just a price event. It was a flow event. US spot Bitcoin ETFs shed $678.9 million in net outflows between October 5 and October 9. Ether ETFs lost another $542.2 million over that same stretch. The combined $1.22 billion withdrawal is significant because it comes from institutional accounts, not retail wallets. These are not panic sellers on a phone app. These are pension allocators and treasury desks rebalancing under new macro constraints. The derivatives market amplified the damage. Approximately $1.19 billion in leveraged positions were liquidated in a single 24-hour window leading into Friday. Ether absorbed $356 million of that total. Bitcoin absorbed $298 million. The rest came from altcoins chasing the same downward momentum. What is striking here is the speed at which the institutional side is building parallel infrastructure while the speculative side gets crushed. Samsung announced it will embed USDC transfers directly into Samsung Wallet for eligible US Galaxy devices later this month. Roughly 82 million devices could gain cross-border payment capability without requiring a separate crypto application. That is not a crypto play. That is a hardware company treating stablecoin rails like a logistics utility. OKX completed a funding round valued at $25 billion before new capital entered. The backers include Circle, Ripple, Qube Research & Technologies, and Standard Chartered's SC Ventures. A digital assets exchange is now structurally owned by a bank, a stablecoin issuer, a payments firm, and a quantitative research house. The architecture behind the scene is clearer than the price action on the surface. US regulators moved in opposite directions during the same week. FinCEN withdrew two proposed reporting rules tied to self-custody wallets and mixing services on October 5. The CFTC simultaneously opened a public comment period on a federal framework for leveraged retail crypto trading that could create a nationally regulated category of crypto platforms. The regulatory posture is not converging toward clarity. It is fragmenting into jurisdictional turf wars. Both agencies are signaling they want oversight power. Neither has delivered a coherent consumer protection standard. The CFTC framework depends on legislation that has not passed Congress. This week also highlighted the fragility of trust at the edge of the stack. Hardware wallet maker Ledger began investigating theft reports connected to devices sold through a reseller in Southeast Asia. Researchers flagged potential losses topping $86 million. The figure remains unconfirmed. A single compromised distribution channel can erase enough value to set back enterprise adoption narratives by months. Samsung's move into stablecoin payments and Ledger's supply chain breach are happening in the same week for a reason. One builds rails. The other exposes where the weak joints sit. The Glamsterdam upgrade reached its scheduled test on the Sepolia testnet on October 6. Ethereum continued advancing its roadmap. Sui disclosed more than $500 million in funding commitments for Hashi, a Bitcoin-backed finance platform targeting a phased mainnet launch. These are real technical events. They are also side quests in a market that just liquidated over a billion dollars of leveraged exposure. Capital is rotating away from speculation and toward infrastructure. The price chart shows pain. The structural filings show positioning. The gap between the two is where the next cycle begins. Author bio: Oliver Hawthorne, principal correspondent covering institutional crypto markets and enterprise blockchain infrastructure for an international technology review.
More

35x Faster Isn’t the Story. The Foundry Lock-In Is.

(SeaPRwire) -By: Nathaniel Cross Microsoft-Decision-1 is built from Qwen3.5-9B. That's a 9-billion-parameter base model. It doesn't write paragraphs. It doesn't generate long-form text. It picks between a fixed set of options. Yes or no. Multiple choice. A rating scale. That constraint is the whole game. Open-ended generation burns compute on tokens that never reach a human screen. Decision-1 skips that entirely. The result: 35x faster inference than OpenAI's GPT-6 Sol. Four point five times faster than a rival model called Quyet-1.0-Large. These aren't incremental gains. They're a different category of architecture. A decision model returns a calibrated probability for every option. That runs on a fundamentally different compute profile than a generative model. The latter produces free-form output. The latency difference matters because every decision in a production AI pipeline adds cumulative delay. When an AI system chains five or six model calls to complete a task, each decision point compounds the delay. Total runtime stacks up. Decision-1 exists to collapse that chain. The API documentation calls Decision-1 a model for "fast decision-making." It lists structured decision tasks. Routing. Classification. Agent controls. AI judging. It promises a calibrated probability for every option. But the architecture enables something the documentation undersells. Decision-1 doesn't just classify. It assigns confidence scores that downstream systems can act on. That means any orchestration layer can treat its output as a probability signal. Feed it into a ticket routing pipeline. Chain it with generative models for quality control. Use it as an AI judge checking whether another system's answer meets predefined standards. Microsoft claims it scored the highest accuracy across 36 benchmarks covering nearly 150,000 questions. Those benchmarks matter because they define the decision boundary. The model isn't competing with GPT-6 Sol on essay writing. It's competing on classification speed and calibrated accuracy. The architecture splits cleanly. Generative models produce content. Decision models route content. Both are necessary. But the orchestration layer that connects them is where the real leverage sits. The pricing structure reveals the real commercial strategy. Input tokens cost $0.042 per million. Output tokens are free. Microsoft says that adds up to savings of up to 200 times lower cost in some internal tests. At first glance, this looks like a cost play. But trace the data flow through the pipeline. When a developer routes customer support tickets through Decision-1, the ticket text becomes input data. The routing decision becomes the model's output. That data stays inside Microsoft Foundry. When the Copilot team uses Decision-1 for AI judging, every quality check runs through Microsoft infrastructure. Every calibration loop tightens the dependency. Free output tokens sound generous. They're not. They mean the model's value is locked into its input pipeline. Every ticket, every quality check, every customer comment flows through Microsoft's metering infrastructure. The Xbox research team processed over 10,000 customer comments from surveys, Steam, and social media posts. Quality matched GPT-6 Sol. Speed hit 14x. Cost dropped 200x. The Copilot team saw close to 100x speed gains for response quality checks at similar result quality. These aren't experiments running in a lab. They're active production workloads. Every team that adopts Decision-1 for routing, classification, or quality control becomes dependent on Microsoft's orchestration layer. Not just the model weights. The pipeline around it. Developers should read the Foundry integration path carefully. Decision-1 launches through Microsoft Foundry first. The company also plans to make it available through OpenRouter. That sequencing matters. Microsoft Foundry already hosts enterprise prompts, orchestration logic, and production deployment pipelines. A model that becomes the default decision layer inside that stack creates switching costs that compound with every production deployment. The Wall Street consensus rates Microsoft stock a Strong Buy. That's based on 36 Buy ratings and one Hold rating over the past three months. The average price target sits at $586.14 per share. That reflects about 9.3% upside from current levels. None of that pricing captures the real asset. The asset is the inference pipeline itself. Microsoft has not said when it plans to expand Decision-1 testing beyond its internal teams. But the model is already running in production. The company said it will keep releasing updates to improve speed and accuracy over time. The supply chain of AI inference is about to consolidate. The winner won't be whoever owns the largest model. It'll be whoever owns the orchestration layer. Author bio: Nathaniel Cross, former Lead AI Research Scientist and decentralized protocol pioneer with over a decade of experience building distributed inference systems, adversarial ML infrastructure, and now writing analysis on AI supply chain architecture and inference economics.
More

The $35 Bet: Fastly’s CDN Is Quietly Becoming an Access Control Plane

(SeaPRwire) - By: Nathaniel Cross Oppenheimer just pulled a 16% candle on Fastly. The move came from a single analyst upgrade. Param Singh moved FSLY from Perform to Outperform. He set a new $35 price target. The stock sat near $25.29 at the time. That implies over 38% upside from where the shares traded. Singh ranks 849th out of more than 12,500 analysts tracked by TipRanks. His calls have landed correctly 66% of the time. His average return is 24%. The upgrade rationale matters more than the ranking. Singh made the call based on industry checks. He found growing contract values. The catalyst was rising demand for Fastly's security products. Average deal sizes expanded during Q3. Cross-selling from existing CDN relationships accelerated. Singh expects Q3 revenue near the top of the $184 million to $190 million guided range. He also expects management to raise full-year 2026 guidance. The stock is already up 148% year-to-date. It has returned 196% over the past twelve months. Fastly shares gained 188% since the start of the year as of Friday's trading session. None of this sits on a profitable income statement. Fastly has not turned a profit in the past twelve months. The market is pricing in a future that hasn't materialized on the books yet. For a company building edge infrastructure, the distance between technical delivery and financial delivery has never been wider. Singh expects the expanding security lineup to keep fueling growth into the fourth quarter and through 2027. A single analyst call moved the stock 16%. That tells you how thin the sell-side coverage is and how reactive the positioning has become. Fastly's September GA releases are the technical pivot. Three products landed together. AI Runtime pushes inference execution to the edge. AI Firewall intercepts traffic at the CDN layer. API Enforcement gates access before requests reach the origin server. The product documentation frames these as standalone developer tools. That framing is where the disconnect starts. These aren't independent utilities bolted onto a CDN. They are edge-layer enforcement mechanisms. They transform Fastly from a content delivery network into an access control plane. When a request hits Fastly's network, it passes through runtime execution, firewall inspection, and API enforcement before it ever reaches the origin. That is three layers of control in one path. Singh points to increasing average deal sizes in Q3. The cross-selling trend is not a sales victory. It is an architecture capture play. Companies already buying CDN bandwidth now buy security enforcement bundled into the same contract. The deal size grows. The switching cost rises. The exit path narrows. Fastly's push toward a unified edge platform is the structural goal. BofA Securities noted this in raising its price target from $20 to $22. The firm also flagged three straight quarters of steady revenue growth. Fastly laid out targets through fiscal year 2029 at its investor day. Those targets include revenue growth of 14% to 21% per year. Oppenheimer expects high-teens to low-20s growth over the coming years. The firm believes this pace is underappreciated at current price levels. The product documentation says "developer tools." The architecture says "chokepoint." There is also chatter about Fastly handling traffic for Meta's Muse AI assistant. That speculation has added to investor interest in the stock. The revenue math doesn't tell the full picture. These security products haven't materially moved the revenue needle yet. Singh expects this to change into Q4 and through 2027. But the broader analyst community is more divided than the stock price suggests. RBC Capital kept a Sector Perform rating with a $25 price target after Fastly's investor day. DA Davidson maintained Neutral and trimmed its target to $23 from $26. The firm cited valuation concerns. BofA moved in the opposite direction, raising its target. Eleven analysts have raised earnings estimates for the upcoming period. Wall Street rates Fastly a Moderate Buy. The consensus is built on six Buys, five Holds, and one Sell. The average price target sits at $28.56. That implies 3% downside from current trading levels. The 188% YTD gain has already front-loaded much of the security product upside. Singh expects the GTA VI launch to drive extra traffic and justify raised 2026 guidance. That is pricing a video game release into a CDN security play. The data model shift is real. Whoever controls the edge controls the traffic. Fastly is positioning itself as the infrastructure layer between content origins and end users. The company's valuation already reflects much of this thesis. The risk is whether the edge platform becomes a durable position or just a well-run commodity network. Analysts expect profitability to flip this year. Fastly has never had a twelve-month period in the black. The analyst divergence is telling. Oppenheimer sees $35. DA Davidson sees $23. That is a 52% spread on the same company. The market has not yet converged on which narrative holds. The question is not whether Fastly can grow at high-teens rates. It can. Oppenheimer and Fastly itself both confirm that range. The question is whether an edge platform becomes a defensible position or remains an expensive pass-through. The Meta Muse AI assistant chatter has done the same speculative work at retail investor level. Fastly has 188% YTD momentum. The $35 target from Oppenheimer is a bet on the chokepoint thesis. Every product launch, every contract expansion, and every deal-size increase feeds into that single narrative. If the security product line becomes a self-sustaining revenue engine, the valuation holds. If it remains a cross-sell upsell on legacy CDN contracts, the stock is already too rich. The next earnings call will show which direction the needle points. The product documentation calls it developer tools. The architecture calls it a chokepoint. The market will decide which story is real when Q4 numbers land. Everything else is noise around a binary outcome. Right now, $28.56 is the consensus. $35 is the bull case. $23 is the bear case. The spread between those three numbers is the entire investment thesis. Fastly either owns the edge or it rents it. There is no middle. The company has to choose which platform it is becoming, and the numbers have to prove it. Author bio: Nathaniel Cross, a former Lead AI Research Scientist and decentralized protocol pioneer.
More

The $125 Million Stampede: Why Novavax’s 16% Pop Is a Receipt Trade, Not a Revenue Trade

(SeaPRwire) - By: Robert Kensington Novavax does not trade on product revenue. It trades on contract milestones. On October 9, the market decided those milestones were worth another 16 percent. Sixteen percent without a single dose shipped. Without a single FDA approval. Just three European regulators stamping paperwork for a trial that has not yet started. The stock moved because November is coming. And November carries a $125 million check. This is not how public companies typically generate sustainable value. Most earn revenue from products they ship. Novavax earns revenue from contracts it waits to fulfill. The company has built its entire valuation on partnership receipts rather than operational control. Here is the official record. Belgium, Germany, and Portugal approved Sanofi's Phase 3 trial for a combined COVID-Influenza vaccine. Patient recruitment begins in November. That milestone triggers the payment from Sanofi to Novavax. The announcement came alongside a BofA upgrade of the price target to $8 from $7. Analyst Alec Stranahan kept the Underperform rating. The consensus target sits at $14. Moderna and Pfizer did not move at all on the same day. This was never a sector story. It was always a Novavax-specific trigger. The question is whether a single regulatory stamp in three countries justifies a sixteen percent repricing. You would think the market demands more than procedural paperwork for that kind of move. A Phase 3 approval in one country would not excite investors this much. Three countries together barely seems like enough. This is where the commercial architecture reveals itself. Novavax does not sell vaccines directly. Its entire business model runs on royalties. The company collects in the high-teens to low-20% range on Sanofi's global Nuvaxovid net sales. That is the recurring engine. The milestone payments are supplementary income. Novavax can collect up to $350 million across all combination-vaccine milestones. A separate $75 million payment is due in mid-2027 for manufacturing technology transfer. So the math is straightforward. Three European approvals unlock a $125 million payment. The same payment was always on the horizon. The real question is whether the stock will retrace once the recruitment date passes without any surprise upside attached. The market is pricing optimism about the timeline. Not about the underlying business. The supply chain here is purely contractual. Novavax is not building clinical operations. It is not managing patient enrollment. It is waiting for Sanofi to hit a calendar date. If recruitment starts in November, the cash flows. If it slips, the stock slips with it. Last week demonstrated this mechanic with brutal clarity. Shares spiked more than 20 percent on a suspected plague case in Russia. The WHO downgraded the public health risk to very low on Tuesday. The stock gave back almost all of those gains within forty-eight hours. Today's move is anchored to a commercial contract rather than a contagion panic. That is marginally more rational. It is still not a foundation for a sustained rally. The stock needs more than milestone checks to justify a durable re-rating. Author bio: Robert Kensington is a veteran industrial investor with three decades of experience in real-economy expansion, M&A, and cross-border market positioning across emerging and developed biotech sectors.
More

Apple’s 15% Cut: The First Crack in the Hardware Moat?

(SeaPRwire) - By: Reginald Vance Apple’s recent trim of 15% to 20% in October component orders for the iPhone 18 Pro is not just a supply chain adjustment. It is a signal of panic. The market sees a modest 1% stock dip and shrugs. I see a fundamental limit. Global memory chip shortages are forcing prices up. Apple passes those costs to consumers. The result is a demand shock. This is the first clear evidence that hardware premiums have hit a ceiling. The supply chain is reacting to a reality Apple’s marketing department ignored. The official facts align with a specific set of data points. Nikkei Asia reports that October orders fell 15% to 20% from initial estimates. Two sources confirm the reduction in component production. Apple raised the iPhone 18 Pro price to $1,199 and the Pro Max to $1,299. That is a $100 jump. This hike directly correlates with rising memory costs driven by AI data center demand. Sales in China looked strong at first. Global demand cooled afterward. The company remains silent on these reports. Uncertainty persists over November adjustments. Look at the supply chain reaction. TSMC shares fell 1%. Qualcomm dipped slightly. The impact is uneven. Tata Electronics, a major manufacturer, feels the pinch. Gene Munster from Deepwater Asset Management provides a clearer view. Lead times for the iPhone 18 Pro dropped 31%. Lead times for the Pro Max rose 1%. These numbers now match last year’s iPhone 17 Pro launch trajectory. Munster argues this softens the case for a strong December quarter. The latest data points matter most when reading trends. The foldable iPhone Duo is a wildcard. It ships on October 23 at $1,999. Munster predicts 20 million first-year sales. That is double current estimates of 10 million. This device could pull buyers away from the Pro lineup. Morgan Stanley holds a different view. Erik Woodring’s team sees no meaningful supply chain adjustments yet. They keep earnings estimates unchanged. EPS for fiscal 2027 stays near $10. For 2028, it is close to $11. They trimmed the price target from $360 to $355. This reflects uncertainty in services monetization. Woodring calls the product roadmap exciting. But the data tells a different story. The capital is flowing toward chips. The consumer is hesitating on price. This gap will widen. Watch the foldable launch. If Duo sales miss, the Pro lineup weakens further. The hardware moat is eroding under cost pressure. Apple’s next move defines its valuation. Author bio: Reginald Vance, a venture partner specializing in semiconductor valuation and advanced materials, providing sharp insights on hardware supply chains and market dynamics.
More

A 657% Rally, a Government Checkbook, and One Question Moderna Bulls Refuse to Ask

(SeaPRwire) - By: Christian Pierce Here is the contradiction nobody on the trading floor wants to say out loud. Moderna is now priced like a company that has already cured something. It has not. The stock surged more than 14% on Friday and touched $225.00 during the session. That set a fresh 52-week high. Over the past year, the shares have climbed 657%. The trigger was not a clinical breakthrough. It was a newspaper report. The New York Times said the National Institutes of Health plans to launch a cancer research campaign in December. The program would copy the public-private model that accelerated Covid-19 vaccine development. Early work would target pancreatic, liver, and colorectal cancers. Pediatric tumors are also on the list. Notice what is missing. There is no signed contract. There is no named partner. There is no committed budget line for Moderna. The market priced in the revenue before the government has even announced the program formally. That tells you the rally is running on narrative momentum, not cash flow. The anxiety underneath is real, too. Covid vaccine revenue is a melting asset. Every investor holding this stock knows it. So the market is desperately hunting for the next story big enough to replace it. Cancer vaccines are that story. Whether the science or the funding can carry a valuation this stretched is a different question entirely. Now consider what is actually verifiable. In August, Moderna and Merck released data on their combined cancer therapy. The regimen pairs Moderna's mRNA-based treatment with Merck's Keytruda. In high-risk melanoma patients, the combination extended the time before cancer returned or spread. That is genuine progress. It is also an intermediate endpoint, not an approval. UBS is explicitly waiting for Phase III melanoma results before changing its Neutral stance. Bernstein holds a Market Perform rating, pointing only to the long-term potential of the platform. These are polite ways of saying the proof is not in yet. Meanwhile, artificial intelligence has entered the pitch. Researchers are using AI to design cancer treatments matched to a patient's own immune system. Moderna's mRNA infrastructure fits that workflow well. Fair enough. But the company has no monopoly on this idea. BioNTech and others are building in the same direction. Then there is the legal overhang. A federal judge in Delaware recently declined to dismiss patent lawsuits filed by Bayer's Monsanto unit against Moderna, Pfizer, and BioNTech over mRNA technology. That case did not go away while the stock doubled. The Nasdaq-100 inclusion on October 9 added mechanical buying pressure. Index funds tracking the benchmark had to purchase shares regardless of valuation. Moderna replaced Warner Bros. Discovery after that company's acquisition by Paramount-Skydance. A chunk of Friday's move was forced flow, not conviction. Strip that out, and the organic bid looks thinner than the headline suggests. InvestingPro's analysis already flags the stock as overvalued at current levels. So how does the commercial loop actually close here. The NIH initiative, if it launches as reported, would pull drug companies and nonprofits into a shared research structure. Government funding would lower Moderna's R&D burn on early-stage cancer programs. That is a real benefit. But public-private programs spread money across many partners. They do not hand one company a franchise. The durable value sits in the melanoma Phase III readout with Merck. If that trial confirms the August signal, Moderna gains a credible path to the first approved personalized mRNA cancer therapy. That would justify a premium. If the data disappoints, the NIH headline becomes wallpaper. My read on the endgame is simple. This stock has become a referendum on whether mRNA is a platform or a one-product accident. The 657% run says the market has already voted platform. The Phase III data will deliver the recount. For anyone holding at $225, the practical move is not to chase the NIH headline. It is to size the position around a single binary event. The melanoma readout is the only number on this calendar that cannot be spun, indexed, or fast-tracked. Author bio: Christian Pierce is a chief financial columnist and markets commentator covering pharmaceutical valuations, healthcare capital flows, and the intersection of government research funding with public equity pricing.
More
Delta’s Warning and the AI Revenue Gap: Why Friday’s Market Rally Is a Trap Business

Delta’s Warning and the AI Revenue Gap: Why Friday’s Market Rally Is a Trap

(SeaPRwire) - By: Robert Kensington The Dow closed up 0.8 percent on Friday. The S&P 500 added 0.6 percent. The Nasdaq climbed another 0.6 percent. All three indexes finished the week in the green after touching fresh highs earlier in the session. The headlines read like a victory lap. But the details underneath do not support the celebration. Delta Air Lines released its third-quarter results on Friday morning. The airline missed earnings expectations. Premium travel bookings were solid. Fuel costs ate the margin right out from under them. Delta has always been the barometer for this season. When the carrier signals pressure, it is usually not limited to one industry. Gas prices have stayed near $4 per gallon this month. The University of Michigan's consumer sentiment survey came out on Friday afternoon. Confidence dropped to its lowest point in five months. The two data points belong to the same story. Households are feeling the cost. They do not have room to absorb another round of pressure when the earnings reports begin. Wall Street wants to believe the artificial intelligence narrative still has endless runway. A report from the Financial Times on Thursday shattered that assumption, at least temporarily. OpenAI's annualized revenue reached $50 billion. Analyst estimates had been $70 billion. The gap was $20 billion. Tech stocks sold off. Investors worried the boom was slowing down. Bloomberg published a follow-up on Friday. OpenAI expects annualized revenue to reach or exceed $70 billion by the end of the year. The revision eased the immediate panic. Tech shares recovered. The Nasdaq benefited from the rebound. But the original report revealed something important about market psychology. A single numbers miss can shake conviction across the entire sector. Confidence in AI demand is brittle. Oil prices fell on Friday. Brent crude traded near $104 a barrel. President Trump announced that Russian President Vladimir Putin agreed to release diesel supplies to the United States. A tweet from The Kobeissi Letter confirmed the claim of 3 million tons. The supply promise pushed prices lower. It did not rewrite the fundamental tension between consumer costs and corporate margins. The S&P 500 closed at 7,811.54 on Friday. That is 46.18 points higher. The Dow finished at 51,654.95, up 423.31 points. The Nasdaq closed at 27,366.17, gaining 172.83 points. The numbers look impressive. They also carry next week's earnings into a fragile environment. Jeff Blazek, co-chief investment officer of multi-asset strategies at Neuberger Berman, said the market tends to react quickly to any signs of slowing growth. He was describing behavior, not prediction. But his observation matters. Major Wall Street banks report their results next Tuesday. Every sector will face scrutiny. Companies that miss guidance by even a narrow margin will feel disproportionate pressure. The OpenAI discrepancy between $50 billion and $70 billion is the exact kind of gap that precedes revised projections. Companies that priced in steady AI-driven revenue growth may need to recalibrate. Delta's fuel-cost warning applies across industries. Airlines are not unique. Manufacturers, retailers, and logistics providers all buy diesel. The consumer sentiment decline means demand-side pressure is real, not theoretical. Earnings season begins Tuesday. The market arrives with momentum and high expectations. The data suggests those expectations may be misaligned with current conditions. Delta set the tone. Oil prices fell on a geopolitical announcement, not structural relief. Consumer sentiment declined for a fifth consecutive month. Tech stocks rebounded on revised guidance, not strengthened fundamentals. The weekly gains are mathematically accurate. The strategic reading is not encouraging. Author bio: Robert Kensington is an overseas entrepreneurial veteran with decades of experience in real-economy industrial investment and expansion.
More
Why Smart Money Ignores Bitcoin While Betting on XRP’s Quiet Comeback Business

Why Smart Money Ignores Bitcoin While Betting on XRP’s Quiet Comeback

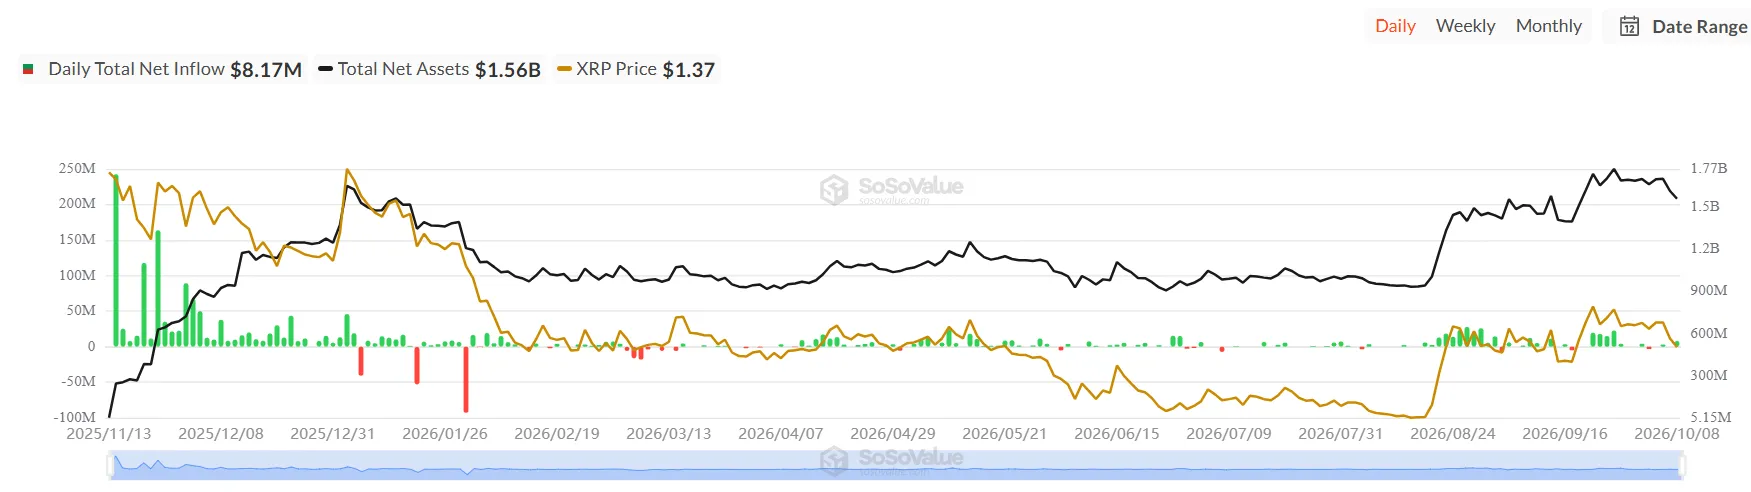
(SeaPRwire) - By: Oliver Hawthorne Everyone is staring at the red screens, but the real story is hidden in the flow data. Bitcoin dropped, yet XRP held its ground against a broader market bleed. That disconnect tells you something important about where institutional interest is actually going right now. It is not about hype. It is about risk management. Traders are rotating out of the biggest assets into those that show relative strength during fear. XRP is leading that specific sub-sector move. The numbers back up this rotation. On October 8, XRP spot ETFs pulled in $8.17 million. Franklin’s XRPZ took it all. Meanwhile, U.S. spot Bitcoin ETFs lost $244 million that day. Fidelity’s FBTC saw $197 million leave. Ethereum funds bled $72.544 million, marking their eighth straight day of outflows. XRP’s price rose 2.82% to $1.38. It bounced from $1.35 but struggled to clear $1.40. The Relative Strength Index sits at 36. That is not oversold territory yet, but momentum is fading. Analyst ChartNerd argues $5 to $8 is achievable. Others see support breaking at $1.35 as a risk to $1.30. This divergence exposes a broken correlation in crypto markets. Bitcoin acts as the index. When it wobbles, capital flees to cash or altcoins with perceived utility edges. XRP now earns prime brokerage fees after Ripple bought Hidden Road for $1.25 billion. That changes the revenue model. It is no longer just a token. It is a revenue-generating asset for the parent company. The Batch amendment vote on XRP Ledger will bundle transactions, cutting costs. XRP’s market cap is $88.14 billion. It is down 50.3% over a year, but only 1.8% over the last month. The stabilization is real. The outflows from BTC and ETH are not a sign of bearishness across the board. They are a sign of capital rotation. The ultimate end-game is a decoupling of performance metrics. Bitcoin will remain the macro barometer. But for high-conviction institutional desks, XRP offers a cleaner narrative of utility adoption. The Hidden Road acquisition provides a tangible financial link that Bitcoin lacks. The ETF inflows, even if small, prove the bid is still there. If $1.40 holds, the path to $1.45 opens. If $1.35 breaks, we test $1.30. The market is waiting for a confirmation. The rotation from BTC to XRP is the signal. Watch the ETF flows, not the price chart. That is where the real institutional vote lies. The divergence is the market’s way of saying the narrative has changed. Author bio: Oliver Hawthorne, a Principal Correspondent permanently stationed at an international technology review, specializes in dissecting global capital flows and the structural shifts within digital asset markets.
More
Barclays Just Slotted MSTR Into the Same Report as Visa. That’s the Real Move Hiding Inside a 3% Stock Pop Business

Barclays Just Slotted MSTR Into the Same Report as Visa. That’s the Real Move Hiding Inside a 3% Stock Pop

(SeaPRwire) - By: Christian Pierce Here's a question most retail traders never ask themselves. When a Wall Street bank moves a stock around its internal sector model, what are they actually changing? Barclays didn't just raise a price target on Strategy from $160 to $175. That's the surface-level story. The deeper move is that analyst Nik Cremo put Strategy in the same third-quarter earnings preview as Visa and Mastercard. He stopped treating MSTR as a Bitcoin proxy and started treating it like a payments infrastructure play. That reclassification is the real story hiding under the 3% pop. The stock traded around $157 on Friday after Barclays dropped the note to clients. Barclays raised the target to $175 from $160 and kept the Overweight rating, which is Buy-equivalent. This is the third adjustment this year. They started at $130, cut to $125 after Q2 results, then raised to $160, and now $175. The new target implies roughly 11% upside. Now look at the broader Street picture. Thirteen analysts give MSTR a consensus Strong Buy. Every single one of those thirteen was a Buy call in the last three months. The average target sits at $236. That implies 52% upside from the current level. All 13 ratings were positive. Not one sell. That unanimity is either a signal of genuine conviction or a sign that nobody wants to be the contrarian on a $73 billion Bitcoin balance sheet. Let me walk through the numbers because most coverage glosses over them. Strategy, led by Chairman Michael Saylor, now owns 848,000 BTC. The average purchase price sits at $75,441 per coin. At current prices, those holdings are worth approximately $72.93 billion. Last week the company added another 334 BTC for roughly $28.7 million. In the third quarter, Strategy booked a $20.91 billion gain on Bitcoin holdings. They ramped purchases in September after spending the summer shoring up preferred stock STRC, which pays 12% yield twice monthly. Over the past 30 days, MSTR has gained more than 18%. Over six months, it's up about 22%. The RSI sits at 55.38, which is neutral-to-bullish with room to run before overbought territory. MACD shows the blue line holding above the orange signal line but the histogram is shrinking. Momentum is cooling slightly after the recent run but hasn't turned negative. The stock carved out a clear higher-low structure since bottoming near $100 in August. It reclaimed the $150 support zone that had capped price action back in July. A break below $150 could open the door back to $125. Holding above $150 keeps the uptrend intact. The $120 to $125 band is the nearest support on a pullback. The $160 to $165 area is the first resistance before a retest of prior highs near $200. Here's the part nobody's talking about. Cremo pointed to Strategy's resilience through the "crypto winter" that ran from October 2025 through the end of June. He cited strong sector fundamentals and steady consumer demand heading into earnings season. But think about that logic. Strategy is a payments company because they survived a crypto winter? That's the argument being sold to institutional investors. Meanwhile, Cremo attributed September's market volatility to rising interest rates and capital rotation into AI stocks. Bitcoin itself recovered to around $82,700 after dipping to a 24-hour low near $80,300. That BTC rebound helped drive the MSTR pop on Friday. Separately, Trump disclosed adding Strategy shares to his portfolio in a recent ethics filing. That disclosure may have added to the stock's gains this week. These are not independent events. They form a feedback loop where crypto sentiment, political signal, and analyst reclassification all feed into the same price action. Now let me put the framing clearly because this is where the institutional game is being played. Strategy's entire corporate treasury is built around one asset. MSTR is structurally tethered to Bitcoin's price swings. Every dollar move in BTC flows through MSTR's balance sheet and then through the stock price. Calling this a payments company doesn't change the mechanics. It just changes who gets to underwrite the risk. When Barclays puts MSTR alongside Visa and Mastercard, they're asking traditional institutional money to treat a Bitcoin treasury vehicle the same way it treats a 40-year-old cross-border payment processor. Those are not the same risk profile. One charges interchange fees on consumer card transactions. The other holds 848,000 BTC and hopes the price stays above $75,441. The STRC preferred stock paying 12% yield twice monthly is the bridge product that makes this palatable to income-oriented allocators. But bridge products don't remove the underlying exposure. They just wrap it. The real end-game here is about access and distribution. Strategy needs Wall Street to accept MSTR as a payments-sector holding so that pension funds and institutional allocators who can't touch pure crypto vehicles can park capital in the stock. The 12% yield STRC preferred stock is the on-ramp. It gives income-oriented buyers a crypto-linked exposure that looks like a bond fund position on paper. The 3% pop on Friday was just the surface reaction to one analyst note. The deeper structural play is getting 848,000 BTC into the hands of institutional money that wouldn't otherwise touch the asset. If MSTR cracks the payments-sector classification with more banks following Barclays, the $236 average target suddenly stops looking like a dream number. If Bitcoin drops back toward the low $80,000s and the crypto winter narrative re-emerges, that same classification protection evaporates in a single week. The market structure favors whichever narrative has more institutional distribution channels. Right now, that's the payments angle. But the stock is still trading at $157. The Bitcoin wallet says otherwise. Author bio: Christian Pierce, a chief financial columnist and markets commentator who specializes in dissecting Wall Street analyst models and uncovering the institutional repositioning hidden inside routine sector reclassifications.
More
Wall Street Can’t Decide If Coinbase Is a Crypto Broker or a Serious Financial Platform—And That’s Exactly the Problem Business

Wall Street Can’t Decide If Coinbase Is a Crypto Broker or a Serious Financial Platform—And That’s Exactly the Problem

(SeaPRwire) - By: Christian Pierce Coinbase is being treated like it has already won a war that nobody finished. Morgan Stanley lifted its price target by eight dollars and suddenly the stock is up over 4%. Eight dollars. That is not conviction. That is a bank adjusting its spreadsheet before earnings week. You do not call that a thesis. You call it noise wrapped in a research note. The real story here is not the price target bump. It is the chasm opening up between Coinbase's official narrative and what the numbers actually show. Morgan Stanley raised its target from $250 to $258 but kept an Equal Weight rating. That is a bank saying the stock is worth more but still not worth buying. Citizens JMP dropped its target from $325 to $280. That is a cut of forty-five dollars. They kept Market Outperform anyway. Two firms, same stock, completely opposite framing of the same data point. Goldman Sachs holds a Buy at $244. Barclays, despite raising its target from $95 to $149, stays firmly at Underweight. Wells Fargo started coverage at Equal Weight with a $200 target. The average across all tracked analysts sits at a flat Hold with a target of $224.29. This is not disagreement. This is fundamental confusion about what business Coinbase actually runs. Last quarter told the uncomfortable truth. Revenue came in at $1.22 billion. The consensus had expected $1.29 billion. That is an 18.5 percent drop year over year. Adjusted losses hit $1.36 per share against a forecast of just $44 cents. The guidance miss was not close. It was wide enough to make any portfolio manager nervous. And yet the stock climbed 4.30 percent on a single analyst moving a target by a margin that would barely cover trading costs. The market is pricing in something the quarterly report did not say. What the quarterly report did say is that Coinbase is trying very hard to become something other than a crypto trading venue. More than 40 percent of revenue now comes from outside spot trading. Subscription and services revenue reached $555 million, with $292 million flowing from stablecoins alone. Average USDC balances on Coinbase products stood at $20 billion. Trading volume share hit a record 10.3 percent, up from 9.1 percent the prior quarter. That is the third straight quarter of gaining ground. Adjusted EBITDA came in at $207.8 million, the 14th consecutive quarter in positive territory. CFO Alesia Haas confirmed expenses came in below the midpoint of guidance across every major category. On paper, the cost discipline looks real. On paper. The problem is that the paper diversification story has real limits. Coinbase filed paperwork in September to bring single-stock futures to American customers. That requires sign-off from both the SEC and the CFTC. Nothing guarantees approval. In Michigan, a federal judge denied Coinbase's request to block the state from enforcing its sports betting law against the company's prediction market contracts. The judge ruled Coinbase had not shown it was likely to win its argument that federal rules override state law. The lawsuit remains open. The company is not a securities exchange. It is not a bank. It is a crypto platform trying to wear multiple financial identities at once, and regulators are not folding. The chart tells you what the analysts cannot agree on. COIN broke out of a consolidation range between $163 and $203. It is now testing the $200 zone after pulling back from highs near $208. The rising trendline from the August low around $145 is holding. Buyers defended the $160s support shelf with a 4.30 percent jump. RSI sits at 48, a neutral reading with room to run either direction. MACD shows the signal line curling back toward the zero line after a recent bearish cross. Momentum has cooled. It has not reversed. A close above $203 opens a path to $220. A break below the $163 trendline support sends shares back toward $145. Here is what happens when a financial platform cannot convince the street whether it is a brokerage, a banking substitute, or a tech company. It trades on momentum until momentum runs out. The next earnings report will decide which version of Coinbase Wall Street finally accepts. Until then, that four percent rally was just a technical bounce in a stock nobody knows how to value. Author bio: Christian Pierce is a chief financial columnist and markets commentator with over fifteen years covering institutional equity research and public company earnings cycles.
More

The Death of the Yield Illusion: How Mashinsky’s Ban Seals Crypto’s “Get Rich Quick” Era

(SeaPRwire) -By: Ethan Gallagher The release of Alex Mashinsky from active duty is not a legal formality. It is the final nail in the coffin for the "DeFi as a savings account" narrative that fooled millions. New York Attorney General Letitia James has secured a settlement worth up to $35 million. Mashinsky is now permanently barred from the cryptocurrency, securities, and commodities industries in New York. This follows his 12-year federal prison sentence for fraud tied to Celsius’s 2022 collapse. The message is stark. The era of trading user deposits like a private hedge fund is over. On the surface, the official release emphasizes restitution. The deal closes a civil fraud lawsuit filed in 2023. James accused Mashinsky of misleading investors about Celsius's safety. The payment structure is conditional. Mashinsky must pay $25 million if he does not forfeit an extra $10 million in gains to federal authorities. He must pay another $10 million if he fails to complete his full prison sentence. These are hard numbers. They represent a direct hit to the founder's personal assets. The state is no longer treating him as a disruptive innovator. They view him as a criminal who drained a public trust. Strip away the legal jargon and look at the commercial reality. Celsius promised yields as high as 17 percent. By early 2022, the company held about $20 billion in digital assets. It could not generate enough revenue to keep paying promised returns. So, Celsius took riskier bets. The company froze withdrawals in June 2022. It filed for bankruptcy the following month. At that time, a shortfall of more than $1 billion was disclosed. As of August 2026, creditors have received over $3.4 billion back through the bankruptcy process. This is not a recovery story. It is a salvage operation. The $35 million settlement is a drop in the bucket compared to the $20 billion hole. Mashinsky is not the only one facing consequences. The FTC settled with him in April, barring him from crypto and finance work. That deal included a $10 million payment and a largely suspended judgment of $4.72 billion. The CFTC also permanently barred him in June. The SEC reached its own agreement in September. Mashinsky is currently serving 12 years in federal prison. He pleaded guilty to securities and commodities fraud in December 2024. The regulatory pile-on is systematic. It is designed to make an example. The industry subtext is clear. If you cannot guarantee liquidity, you do not get to call yourself a bank. The supply chain landscape for compliant crypto infrastructure is now bifurcated. One side holds actual reserves and audits. The other side remains a black box. Investors will migrate to the former. The latter will continue to bleed users into the next collapse. There is no middle ground. Author bio: Ethan Gallagher, a Silicon Valley Hardware Architect and Infrastructure Strategist specializing in decentralized systems and capital efficiency.
More

The CFTC’s Gambler’s Fallacy: How Washington Stole the Prediction Market War Before It Started

(SeaPRwire) -By: Julian Holbrooke The CFTC is not securing a jurisdiction; it is carving out a legal no-man’s-land. By rushing an interim final rule to classify event contracts as swaps, the agency is playing a desperate game of chicken with the states and the Supreme Court. This move ignores the fundamental nature of these products. They are not complex derivative instruments traded by institutional desks. They are digital wagers on sports scores and election outcomes. The agency is treating a casino lobby problem as a financial stability crisis. That mischaracterization is the core error. It creates a regulatory loophole that benefits only the tech platforms involved, while shutting out the traditional gambling industries that have been regulated for decades. The result is not clarity. It is a mess of conflicting legal theories that will take years to untangle in the courts. Look at the official release. The CFTC issued an interim final rule effective immediately. It explicitly excludes casino-style gambling, like blackjack or roulette, from the swap definition. Then, it proposed a second rule to classify event contracts as swaps under the Commodity Exchange Act. This dual-track approach is confusing on purpose. On one side, they are saying, "We don't touch casino gambling." On the other, they are saying, "But if you bet on a Super Bowl score, that's a swap, and we own it." This distinction is arbitrary. A sports bet and a casino bet are functionally identical to the user. Both are wagers on uncertain outcomes. The CFTC is drawing a line in the sand that makes no economic sense, but it makes perfect political sense. It allows them to claim exclusive federal authority over a new, lucrative digital market while leaving the old, organized casino industry alone. Now look at the industry subtext. Who is backing this? Kalshi and Robinhood. These are tech companies, not gambling operators. Robinhood is a brokerage. They have zero interest in the long-term stability of the gambling regulatory framework. They have every interest in bypassing state licensing fees and state regulatory oversight. States like New York are suing Polymarket. They argue that if the CFTC has jurisdiction, state gambling laws are preempted. That is a massive risk for states that rely on gaming revenue. The states are fighting back. They have gone to the Supreme Court. The NFL is on their side. Why? Because the NFL wants to maintain its exclusive licensing deals with legal sportsbooks. The CFTC’s move threatens to dismantle the entire state-regulated sports betting industry overnight. The "subtext" is that the CFTC is acting as a shield for Silicon Valley tech entrants, protecting them from the heavy regulatory burden that has traditionally plagued the gaming industry. The endgame is clear, but it is not good for democratic governance. The Supreme Court has a 31% chance of taking up the case by year-end. That is a high probability, but not a certainty. If they don’t, the CFTC’s interim rule stays in effect. That means a federal agency, currently operating with a single commissioner, effectively controls the regulation of digital gambling nationwide. That is a concentration of power we have not seen since the New Deal. The states have lost their leverage. The traditional gambling operators are stuck in the middle. The tech platforms are winning. They get to operate under a lighter touch, with federal oversight instead of state-by-state licensing. It is a deregulation disguised as regulation. The pendulum has shifted. The next time you want to place a digital bet on a political outcome, you are no longer dealing with your state gaming commission. You are dealing with the CFTC. And they are not interested in responsible gambling. They are interested in market structure. The war is over. The tech platforms won. Author bio: Julian Holbrooke, an overseas international relations analyst who frequently contributes to major European daily newspapers, focusing on the intersection of technology, governance, and geopolitical power dynamics.
More

Bessent’s Billion-Dollar Theater: Why Washington’s Crypto Sanction Numbers Never Add Up

(SeaPRwire) -By: Helena Brooks The dollar sign is doing a tremendous amount of heavy lifting in Scott Bessent's latest press conference. One billion dollars. That is the figure he tossed at Newsmax's Policy Summit in Washington on Thursday, October 9th, delivered casually, as if ordering a double espresso at a corner café. In May, he made the same claim about a billion already seized. Treasury's own release that same month quietly cited a total near five hundred million. The discrepancy sat unexplained for months, a half-billion-dollar ghost haunting the sanctions ledger. Now he is back with another billion, and this time, he insists, it is happening this week. What we are watching unfold in Washington is not enforcement. It is performance, and the audience is the markets. The official narrative is sweeping. Bessent declared an "absolute isolation campaign" against Iran, framing it as an upgrade from the previous "maximum pressure" framework that defined the prior administration's Iran policy. He spoke of blockades in the Strait of Hormuz, grounded international flights to and from Iranian airspace, and severed land corridors along Iran's borders with its neighbors. The conflict between the US and Iran has dragged on since February, and sanctions on Iran's financial networks have been the central weapon in Washington's response arsenal. On the crypto front, the rhetoric is equally aggressive. Treasury has sanctioned seven Iranian exchanges since June. Nobitex, Wallex, Bitpin, and Ramzinex were hit in the first wave. Shelbit and Aban Tether followed in August. BitBank received its sanction in September, with Treasury accusing the platform of funneling hundreds of millions of dollars in bitcoin to the Islamic Revolutionary Guard Corps between June and July of this year. But strip away the conference hall rhetoric and the actual enforcement record is considerably thinner than the summit remarks suggest. In July, Treasury announced wallet sanctions that froze one hundred thirty million dollars. An onchain analyst known by the handle Specter traced those funds to four Tron addresses holding roughly one hundred thirty-one million in USDT. Tether later blacklisted those addresses, confirming the freeze. That is real enforcement. It is also reactive enforcement, found by an independent researcher, not by Treasury's own surveillance apparatus. Tether's broader compliance report for 2026 shows five hundred fifty million dollars in USDT frozen across the year as part of US sanctions enforcement. Of that total, a staggering three hundred forty-four million was frozen in April alone. That single month accounts for nearly two-thirds of the annual figure. It is a meaningful number. But it is not a billion. It is not two billion. The May discrepancy between Bessent's claimed seizure total and Treasury's own released figure has never been publicly addressed or reconciled. And for the latest billion-dollar claim, Bessent names no specific wallets, no specific exchanges, and no identifiable targets. Treasury has released absolutely nothing beyond his remarks at the summit. Not a single detail. There is a pattern here that demands closer scrutiny from anyone tracking sanctions enforcement with analytical rigor. Every time the claimed dollar figure outruns the available evidence, Treasury retreats to a lower, unbranded press release. Bessent claims one billion. The release says five hundred million. Nobody is held accountable for the discrepancy. The cycle repeats. Meanwhile, the seven sanctioned exchanges represent genuine disruption to Iran's crypto infrastructure. The damage is real. The platforms listed have played actual roles in Iran's shadow financial system. But the enforcement mechanism is fundamentally reactive. Wallets get traced after the fact. Addresses get blacklisted after the money has already moved through the system. The July freeze worked only because Specter, operating entirely independently of any government agency, identified the Tron addresses first. Treasury did not surface those wallets through its own investigative capacity. That gap between ambition and operational capability is not a bug. It is the architecture of the problem. Here is where the structural reality of crypto sanctions collides with the political ambitions of a Treasury Secretary running numbers in public. Every sanctions regime eventually encounters the hard limitations of its own architecture, and crypto sanctions hit those limits faster than any traditional financial embargo. Wallet addresses can be frozen, yes. Exchanges can be blacklisted, absolutely. But funds reroute through privacy coins, decentralized mixers, tumbling services, and jurisdictions with no legal obligation to comply with OFAC directives. Tether's compliance apparatus is only as robust as its dependence on US dollar reserve backing and its willingness to cooperate with American regulators. The company froze three hundred forty-four million in April alone. That suggests coordination, but also dependence on a single issuer playing ball with Washington. The next legislative patch is not going to target more wallets or more exchanges. It is going to target the stablecoin issuers themselves at the infrastructure layer. Expect a bill forcing USDT and USDC to embed mandatory compliance backdoors into their protocol code, giving Treasury direct authority to freeze funds at the smart contract level before they can move across any chain. That is where the billion-dollar number stops being rhetoric and starts being policy. The billion-dollar seizure figure is not a forecast of operational capability. It is a political incentive designed to drive the legislation that makes such seizures possible at scale. Author bio: Helena Brooks, a financial intelligence tracking expert specializing in illicit capital flows, sanctions architecture, and state-level enforcement operations across traditional and decentralized financial systems.
More
Telegram’s $1.50 Bet: How a Messaging App Became a Crypto Superhighway Business

Telegram’s $1.50 Bet: How a Messaging App Became a Crypto Superhighway

(SeaPRwire) - By: Lucas Caldwell Telegram just moved the goalposts. They stopped treating crypto as a feature and started treating it as the infrastructure. The "Money" wallet rollout is not a minor update. It is a structural shift that touches over one billion users. This is the moment the messaging app became a financial terminal. The 9% jump in GRAM to $1.56 was the market reacting to this new reality. Let’s look at the raw numbers. GRAM hit $1.56. Market cap is $4.12 billion. Trading volume spiked 41% to $132.4 million in twenty-four hours. The bearish trend from the last seven days is gone. The token used to be called Toncoin. It changed its name in June. The blockchain stays TON. The wallet is now Money. It is non-custodial. You own your keys. No network fees for transfers. Instant settlement. This is where the game theory gets interesting. Money is separate from Walt. Walt handles the heavy lifting. It trades over 300 assets. It lists 200 crypto coins. It even offers tokenized stocks and ETFs. It covers perpetual futures on oil and gas. Money is the entry point. It is simple. It sits inside the chat. Walt is the casino. It is complex. It handles custodial and decentralized finance. The separation is clean. Durov outlined this plan back in July. He wanted self-custody inside the app. Validators approved the smart contract. Upgrades happen without moving assets. This architecture protects the user. It also protects the platform. If the code breaks, the fix is seamless. No mass migrations. No liquidity traps. The design is robust. It removes the friction that kills most consumer crypto apps. The real play is distribution. One billion users. That is a moat no DeFi protocol can dig alone. Telegram solves the user acquisition problem. It is the biggest hurdle in Web3. They bypassed it by embedding finance into a tool people already use daily. Gifts and usernames are the hook. Trading is the engine. The supply chain of trust flows through the messenger. Watch the volume. If daily active traders on Walt do not sustain, the price is a hallucination. Author bio: Lucas Caldwell, a tech opinion leader with millions of followers on X/Twitter, specializing in decentralized finance narratives and consumer platform shifts.
More

The 11-Year-Old XRP Ledger Bug That Could Have Printed Billions—and Wasn’t Even Found by the Right People

(SeaPRwire) -By: Silas Sterling There is a quiet rhythm to how crypto networks rot from the inside out. You build something on open code. You assume it has been reviewed. Then an AI research firm stumbles across a decade-old arithmetic mistake that could mint currency out of thin air. That is exactly what happened on the XRP Ledger this past September. The fix dropped on September 25. No press conference. No fanfare. Just a software patch note that most users probably scrolled past without reading. Cayden Liao and the team at Veria AI reported the flaw privately on September 22, 2026. RippleX engineers reproduced the exploit on a private test server. They could generate new XRP and spend it. The protocol's own accounting checks failed to catch it because the vulnerability lived in the very math those checks depended on. A secondary safeguard designed to cap how much XRP a single account could hold was bypassed simply by spreading the minted tokens across hundreds of small accounts. The attacker only needed a handful of XRP to open those accounts and pay basic transaction fees. No sophisticated tooling required. The 100 billion XRP hard cap could have been shredded for almost nothing. What happened next tells you everything about how responsible disclosure works in practice. There is no evidence anyone used this exploit on the main network. The vulnerability dated back to 2015. The entire XRP supply of 100 billion tokens was created at launch in 2012. The ledger was engineered so no additional coins could ever be issued. Yet the exchange mechanism that allowed token swaps contained this fatal gap in how it tallied large orders. The bug sat dormant. Unseen. A ticking time bomb that never detonated. This is the third major crypto infrastructure flaw uncovered this year through AI-assisted discovery. Coldcard wallets. Core Lightning software. And now XRP Ledger. The pattern is unmistakable. AI tools are finding weaknesses that human auditors missed for years. The XRP Ledger developers chose to ship the fix quietly through xrpld 3.4.1 without publicly describing what the update addressed. That silence itself is a data point. It suggests a sector still learning how to handle discoveries that come from outside its traditional circles. Meanwhile, the same network activated a new feature called Batch on mainnet. Thirty of 35 validators approved the change after a two-week supermajority vote. The feature bundles up to eight transactions into a single action with an atomic execution option. It is designed for trades and settlements that require multiple steps to succeed or fail together. The XRP Ledger continues to evolve alongside its security posture, even when that evolution is partly reactive to external pressure. Evernorth, a company linked to XRP, is also preparing for a Nasdaq listing under the ticker XRPN, delayed from October 8 to October 12 due to administrative reasons. SEC filings indicate it will hold roughly 473 million XRP post-listing. Another chapter in the ongoing story of how this ecosystem scales beyond the blockchain itself. Author bio: Silas Sterling is a veteran kernel contributor and editor-in-chief of an open-source security digest focused on critical infrastructure vulnerabilities.
More

Blockchain.com Is Betting a $4 Billion IPO on a License the CFTC Hasn’t Finished Writing

(SeaPRwire) -By: Jonathan Barrett Blockchain.com just asked Washington for a green light to run prediction markets and crypto derivatives inside American borders. The filing targets two CFTC licenses. One is a designated contract market charter that would let the company run its own futures exchange. The other is a futures commission merchant license that would let it broker derivatives contracts to customers in the US. CNBC reported the filing on Friday. CEO and co-founder Peter Smith framed the goal plainly. Users should be able to trade assets, derivatives, and event contracts in one place, under proper regulatory rules. The ask is clean on its face. What makes it sharp is the timing. The regulatory window is open, and competitors are already moving. The CFTC is not waiting on Congress. Chair Michael Selig said this week the agency is moving forward with rulemaking on its own authority. He pointed to the 2022 FTX collapse as the justification for the push. FTX filed for bankruptcy that year. Criminal charges followed for several former executives, including Sam Bankman-Fried. Selig told Fox Business the proposed rules would bring safeguards to crypto spot markets. In a Friday social media post, he added that the rules aim to prevent theft of customer funds. He is currently the CFTC's only commissioner and chair. Four seats sit empty. No White House nominees as of Friday. The rulemaking is proceeding with a single voice at the helm. Blockchain.com already runs prediction markets outside the US. That business launched in July through a partnership with Polymarket. The company also offers perpetual futures contracts powered by Hyperliquid, currently limited to international users. If the CFTC licenses clear, the firm can operate its own marketplace for event contracts alongside the existing Polymarket deal. Other crypto firms have moved in the same direction. Crypto.com and Gemini Space Station both run their own event contract marketplaces. Coinbase offers event contracts mainly through a partnership with Kalshi. Kalshi and Polymarket have also launched perpetual futures contracts for traders. The competitive field is building. Blockchain.com wants to be in it before the rules are final. Blockchain.com is one of twelve companies that have filed for a designated contract market license this year. The CFTC has approved six new designated contract markets so far in 2026. The approval pipeline is moving. Meanwhile, the company is preparing for a possible IPO. It filed confidentially with the SEC in May. Bloomberg reported last month that the firm is targeting a valuation between $4 billion and $6 billion. It aims to raise $500 million through the offering. Public markets will demand a clean regulatory profile before pricing the stock. The company wants American users to trade event contracts and crypto derivatives on a single platform. Capital and regulation are moving on parallel tracks. The prediction market industry is not sitting still on legal questions either. New Jersey officials filed a petition with the US Supreme Court last month. It concerns a case against Kalshi over state and federal oversight boundaries. The state-federal friction over event contracts is live and unresolved. Selig has also stated the CFTC has sole authority over prediction markets. He has said he intends to carry out President Donald Trump's crypto policy goals. Private capital is hedging across regulatory outcomes. Firms are buying licenses, building partnerships, and preparing public market stories at the same time. The question is which regulatory thread pulls first. The stakes are too high for any of them to wait. The CFTC will approve the next batch of designated contract markets before the state-federal prediction market dispute reaches the Supreme Court, and the firms already in the queue with clean balance sheets and international user bases will capture the bulk of American retail flow. Author bio: Jonathan Barrett, lead focus editor for an independent overseas public affairs weekly covering regulatory policy, financial oversight, and institutional power dynamics across three continents, with two decades reporting on Washington and Brussels.
More