The 8:30 a.m. Guillotine: Why Wall Street’s Calm Before CPI Is a Rotational Trap, Not a Pause
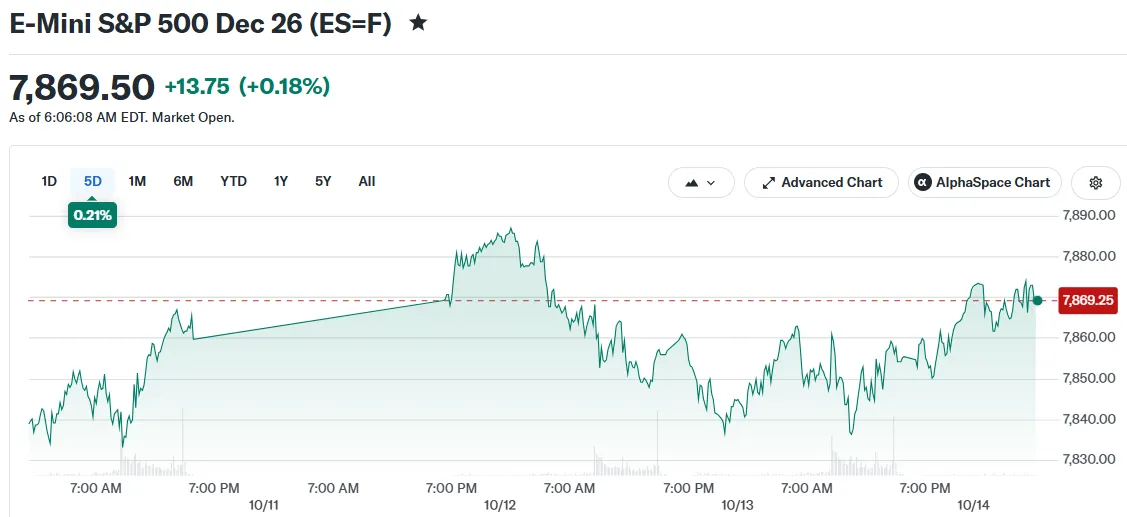
(SeaPRwire) - By: Christian Pierce Markets do not go quiet because investors feel confident. They go quiet because they are afraid to be wrong. That is exactly what Wednesday's tape was telling us. Dow futures climbed roughly 236 points, about 0.5%, while S&P 500 futures managed only a 0.2% gain and Nasdaq 100 futures sat flat. That is not optimism. That is hesitation dressed up as a green open. Every desk on the Street is staring at the same clock. The September Consumer Price Index lands at 8:30 a.m. Eastern, and economists expect headline inflation to print at 3.6% year over year, lifted by gas and energy costs. The real anxiety sits in the core number, which strips out food and energy. That is the figure the Federal Reserve actually trades off of. A hot reading, and the October 27 to 28 meeting stops being a formality. A rate hike goes back on the table. That single possibility explains why a quarter-point of futures movement felt like the loudest signal of the week. Growth deadlocks rarely announce themselves with a crash. They announce themselves with a market that refuses to commit, a 10-year Treasury yield pinned near multiyear highs, and a rotation out of tech into defensive and healthcare names that nobody wants to call risk-off yet. The Dow's edge over the Nasdaq is the tell. Money is not leaving equities. Money is hiding inside them. The facts, taken in order, paint a market being squeezed from three directions at once. First, earnings season opened with a crack. JPMorgan posted a rare quarterly miss. Adjusted EPS came in at $5.75 against a $5.90 estimate, and fixed income markets revenue of $5.4 billion missed the $5.89 billion consensus. Equity markets revenue was the bright spot at $5.0 billion, up 49% year over year, and managed revenue still grew 8% to $50.9 billion. But bank stocks fell anyway. Investors sold the miss and ignored the beat. Then came the second wave. BlackRock, Bank of America, Morgan Stanley, and State Street all report on Wednesday, and the earlier results suggested consumers are still holding up under higher rates. That is the one thread of relief in an otherwise tense session. Second, the semiconductor complex is under the microscope. ASML reports Wednesday and Taiwan Semiconductor follows Thursday. The Street wants proof that AI demand is intact, because the sector just took real damage. South Korea's KOSPI fell 12% over five days before bouncing, and Nasdaq futures hovered barely above flatline as the chip sell-off eased. Third, energy is the wildcard that feeds straight into the CPI math. Brent crude held above $105 a barrel while Houthi attacks on Saudi Arabian energy facilities continued. Higher oil feeds headline inflation. Higher headline inflation feeds the Fed narrative. Higher rates feed the multiple compression already visible in tech. The bond market knows it. Treasury yields steady near multiyear highs is the bond market's way of saying it does not believe the inflation fight is finished. Every one of these threads connects. Oil drives CPI. CPI drives the Fed. The Fed drives bank net interest income, chip valuations, and the consumer credit that JPMorgan's results just put on trial. So what does the commercial loop actually look like from here. The big banks are the transmission mechanism. If Bank of America and Morgan Stanley confirm JPMorgan's pattern, where consumer resilience coexists with trading revenue misses, then the market learns that the financial sector cannot carry the index alone. If BlackRock shows fee pressure and State Street shows custody outflows, the asset management side confirms margin stress across the whole financial stack. Meanwhile, the AI trade is on probation. ASML and TSMC are the two companies that can either validate or puncture the capex supercycle thesis. One weak guide on lithography orders or foundry utilization, and the rotation into defensives accelerates. One strong print on AI demand, and Nasdaq futures stop hovering at flatline. The endgame here is bifurcation. The market is splitting into companies that can fund growth with free cash flow at a 10-year yield near multiyear highs, and companies whose valuations assumed rates would be lower by now. The first group absorbs $105 oil and a hawkish CPI print. The second group cannot. My practical read for anyone positioning this week is simple. Do not chase the Dow's premarket strength into the 8:30 release. Wait for the core CPI number, then watch the bank earnings reaction rather than the headline beats. The number that matters is not what JPMorgan missed yesterday. It is whether the Fed's October meeting turns into a live one. If core prints hot, the rate hike conversation returns, and the defensive rotation stops being a trade and becomes the trend. Author bio: Christian Pierce, a chief financial columnist and markets commentator who has covered earnings seasons, Federal Reserve cycles, and cross-asset rotations for major financial publications over two decades.
More